|
시장보고서
상품코드
2121624
에탄올아민 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Ethanolamines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
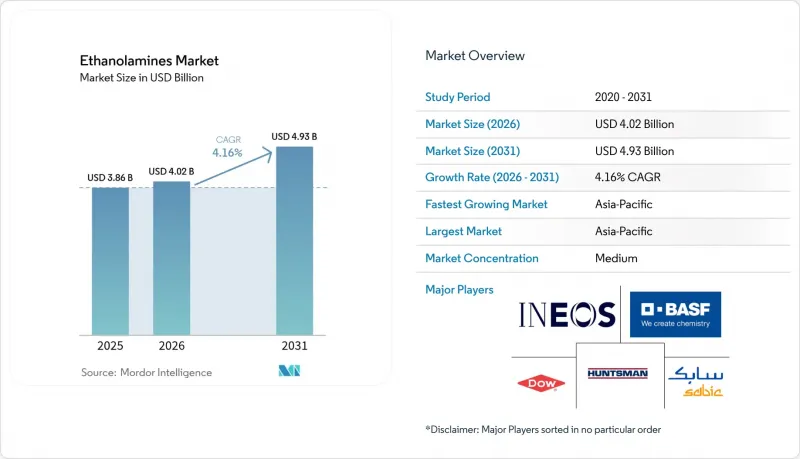
에 의하면, 2026년 에탄올아민 시장 규모는 40억 2,000만 달러로 추정되며, 2025년 38억 6,000만 달러에서 2031년에는 49억 3,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 4.16%를 기록할 전망입니다.
본 보고서는 제품 유형(모노에탄올아민, 디에탄올아민 등), 기술(에틸렌옥사이드법 및 바이오에탄올법), 용도(가스 처리, 제초제 등), 최종 사용자 산업(석유 및 가스, 농업 등),지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 에탄올아민 시장 동향 및 인사이트
신흥국의 급속한 산업화
중국, 인도, 인도네시아, 베트남에서의 고정자산 투자가 급증함에 따라, 가스 탈황, 시멘트 첨가제, 공정용 화학약품용 에탄올아민의 새로운 소비가 촉진되고 있습니다. 첨단 배터리 원료를 대상으로 한 중국의 정책 패키지는 전해액 정제 프로젝트를 위한 모노에탄올아민 수요를 직접적으로 끌어올리고 있습니다. 인도의 바이오에탄올 생산 능력 확대는 재생 가능 에탄올아민 플랜트를 위한 미래의 원료 공급을 강화하고 수입 의존도를 낮추는 동시에, 수출 지향형 특수 화학제품 클러스터를 지원하고 있습니다. 동남아시아의 건설 프로젝트 확대는 시멘트 분쇄 보조제로서의 트리에탄올아민 수요를 끌어올리고 있는 반면, 동 지역 전력 회사들은 석탄 및 가스 화력 발전소의 탈탄소화를 위해 아민계 CO2 포집 기술을 도입하고 있습니다. 도시화로 인해 세제 및 개인 위생 용품의 1인당 구매량이 증가하고 있으며, 계면활성제 등급의 에탄올아민에 대한 구조적 수요가 정착되고 있습니다. 이러한 동향들이 맞물려 에탄올아민 시장에는 광범위하고 중기적인 급격한 성장이 예상됩니다.
제초제 내성 작물을 위한 글리포세이트 생산 급증
잡초 내성에 대한 논쟁이 격화되는 가운데에도, 브라질, 아르헨티나, 미국에서는 제초제 내성 대두와 옥수수의 재배 면적이 계속 확대되고 있어, 에탄올아민을 이용한 중화 공정에 의존하는 글리포세이트의 합성량은 계속해서 높은 수준을 유지하고 있습니다. 다국적 제제 제조업체들은 비용 경쟁력이 있는 아시아 거점으로 생산 거점을 옮기고 있으며, 이로 인해 전 세계 총 소비량을 변화시키지 않으면서도 에탄올아민 시장에 새로운 수요원이 생겨나고 있습니다. 개발도상국에서는 노동력 절약으로 이어지는 제초제가 수작업 제초보다 여전히 저렴하기 때문에 농업 기계화의 추진으로 글리포세이트 사용량이 증가하고 있습니다. 글리포세이트와 상호 보완적인 유효 성분을 혼합한 새로운 ‘더블 녹(Double Knock)’ 프로그램은 많은 경우 1헥타르당 아민의 총 수요량을 증가시킵니다. 유럽연합(EU) 규제 당국은 합성 화학물질의 사용량 감축을 추진하고 있지만, 이러한 규제는 일반적으로 절대적인 생산량을 억제하기보다는 제조 거점을 규제가 완화된 지역으로 이전시키는 결과를 낳고 있습니다. 그 결과, 글리포세이트에 기인한 단기적인 호조는 에탄올아민 시장의 성장에 계속해서 긍정적인 요인으로 작용하고 있습니다.
변동성이 큰 에틸렌옥사이드 원료 가격
에틸렌옥사이드의 현물 가격은 여전히 나프타와 천연가스 가격 변동에 매우 민감하며, 급격한 가격 상승 국면에서는 개별 에탄올아민 생산 업체에 압박을 가하고 있습니다. 2025년 초, 올레핀 마진의 악화로 인해 가동이 불경제적이 되자 한국의 여러 크래커가 가동을 중단했고, 아시아태평양 전체의 에틸렌옥사이드 공급이 부족해졌습니다. BASF나 다우와 같은 통합형 대기업은 에틸렌옥사이드 생산 라인을 마진이 가장 높은 파생 제품으로 재분배함으로써 가격 변동에 대한 내성을 높이고 있으며, 시장 집중을 뒷받침하는 구조적 우위가 부각되고 있습니다. 수에즈 운하와 파나마 운하를 통과하는 화물 운송의 혼란은 원료 차익 거래 흐름에 추가적인 불확실성을 더하고 있습니다. 중소규모의 배합 제조업체들은 생산량 감축이나 추가 비용 전가를 통해 대응하고 있지만, 가격 충격이 장기화될 경우 범용 세제와 같이 가격에 민감한 용도에서 수요 감소로 이어질 위험이 있습니다. 그 결과, 원료 시장 동향이 정상화될 때까지 에탄올아민 시장에는 단기적인 하락 압력이 가해질 전망입니다.
부문 분석
모노에탄올아민은 안정적인 가스 스위트닝 가동, 급증하는 이산화탄소 포집 시범 프로젝트, 그리고 세제 분야의 폭넓은 용도에 힘입어 2025년 매출의 44.62%를 차지했습니다. 이 부문은 2031년까지 연평균 성장률(CAGR) 6.32%를 나타낼 것으로 예측되어, 에탄올아민 시장에서 핵심적인 역할을 더욱 공고히할 것입니다. 모노에탄올아민은 반응성이 높기 때문에 배합 설계자가 광범위한 pH 범위에 대응하는 제품을 조정할 수 있어, 산업 전반에 걸쳐 중요한 위치를 유지하고 있습니다. 한편, 디에탄올아민은 금속 가공액 및 제초제 중화 분야에서 확고한 틈새 시장을 유지하고 있으며, 부식 방지 성능의 향상으로 제품별 가치도 높아지고 있습니다. 트리에탄올아민은 시멘트 분쇄 보조제로서 발전하고 있으며, 최대 5 MPa의 압축 강도 향상을 가져와 주요 인프라 프로젝트의 경화 시간을 단축하고 있습니다.
3가지 주요 등급에 걸친 다각화를 통해 공급업체는 특정 하류 부문 수요 변동으로부터 보호받고 있습니다. 정유시설 및 제철소의 탄소 포집 설비 개보수로 인해 모노에탄올아민의 주문량이 급증할 가능성이 있는 반면, 퍼스널케어 제품의 프리미엄화는 트리에탄올아민의 견실한 이익률을 뒷받침하고 있습니다. 이러한 동향들이 맞물려 에탄올아민 시장은 제품 수준에서 양호한 균형을 유지하고 있습니다.
기존의 에틸렌옥사이드 공법은 2025년 세계 생산량의 91.75%를 차지하고 있으며, 이는 수십 년에 걸친 최적화와 매몰 자본의 우위를 반영합니다. 그럼에도 불구하고, 재생 가능 원료 함유율 의무화 및 기업의 탄소 중립 목표에 힘입어 바이오에탄올 경로는 연평균 성장률(CAGR) 7.12%로 확대될 것으로 예측됩니다. 태국과 브라질의 초기 상업 플랜트는 농업 잔여물 유래 바이오에틸렌이 기존의 아미네이션 공정에 원활하게 통합될 수 있음을 보여줌으로써, 다운스트림 공정에서의 적합성 장벽을 낮추고 있습니다. 유럽의 탄소 국경 조정(CBA) 제도는 내재된 배출량에 가격을 책정함으로써 비용 격차를 줄이고, 향후 지출을 저탄소 경로로 유도하고 있습니다.
연속 반응 시스템, 막 분리, 촉매를 이용한 재배열과 같은 공정 고밀도화 노력을 통해 기존 기술도 현금 비용 측면에서 경쟁력을 유지하고 있습니다. 그럼에도 불구하고, 인증된 저탄소 분자에 대해 프리미엄을 지불할 의사가 있는 브랜드 소유자의 존재는 바이오 공급업체에게 매력적인 발판을 제공합니다. 그 결과 탄생한 이중 경로(dual pathway) 프레임워크는 충분한 공급을 확보하는 동시에 에탄올아민 시장 전체의 기술 혁신을 촉진합니다.
지역별 분석
아시아태평양은 통합형 석유화학 단지, 경쟁력 있는 노동력, 그리고 확대되는 하류 제조 허브에 힘입어 2025년에는 매출 점유율 46.35%를 차지하며 시장을 독점했습니다. 중국의 정유사들은 국내 세제 및 전자 화학제품 고객에 대한 공급을 목적으로 모노에탄올아민 생산 라인의 병목 현상 해소를 지속적으로 추진하고 있습니다. 한편, 인도의 바이오에탄올 급증으로 인해 이 대륙은 재생 가능 에탄올아민의 미래 수출 거점으로서의 입지를 확립해 가고 있습니다. 태국과 베트남에 집중된 동남아시아의 농약 제제 제조업체들은 지역 내 작물 보호 관련 지출 증가에 따라 추가적인 수요를 견인하고 있습니다.
북미에서는 텍사스주와 루이지애나주의 산화물 유도체 클러스터를 핵심으로 하는 견고한 생산 기반이 유지되고 있습니다. INEOS가 7억 달러에 LyondellBasell 시설을 인수한 것은 가스 정제 기술 라이선스 제공 기업과의 장기 공급 계약을 위한 원료 확보로 이어지고 있습니다. Huntsman사가 더 우드랜즈에서 추진 중인 E-GRADE 확장 사업은 반도체용 정제라는 틈새 시장을 목표로 하고 있으며, 이 지역에 일반 상품의 이익률 주기에 대한 부가가치 있는 헤지를 제공합니다.
유럽의 엄격한 탄소 정책으로 인해 투자는 저배출 설비로 향하고 있으며, BASF가 앤트워프에서 진행한 14만 톤 규모의 설비 확장이 그 대표적인 예입니다. 누리용(Nuryong)사의 스테누ング스운드(Stenungsund) 공장에서 획득한 ISCC PLUS 인증은 추적성을 확보한 재생 가능 원료의 사용을 가능하게 하여 퍼스널케어 분야 수요를 자극하고 있습니다. 탄소 국경 조정 가격 제도로 인해 배출량이 많은 에탄올아민의 수입 프리미엄이 상승할 것으로 예상되며, 간접적으로 인증을 받은 유럽산 제품이 우위를 점하게 될 것입니다. 이러한 지역적 동향이 종합적으로 작용하여, 에탄올아민 시장의 안정적인 유통을 뒷받침하는 균형 잡힌 세계 네트워크를 유지하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, ethanolamines market size in 2026 is estimated at USD 4.02 billion, growing from 2025 value of USD 3.86 billion with 2031 projections showing USD 4.93 billion, growing at 4.16% CAGR over 2026-2031.
This report is Segmented by Product Type (Monoethanolamine, Diethanolamine, and More), Technology (Ethylene Oxide Route and Bio-Ethanol Route), Application (Gas Treatment, Herbicides, and More), End-User Industry (Oil and Gas, Agriculture, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Ethanolamines Market Trends and Insights
Rapid industrialisation in emerging economies
Surging fixed-asset investment across China, India, Indonesia and Vietnam stimulates fresh consumption of ethanolamines for gas sweetening, cement additives and process chemicals. Chinese policy packages that target advanced battery raw materials directly raise monoethanolamine offtake for electrolyte purification projects. India's widening bio-ethanol capacity reinforces future feedstock availability for renewable ethanolamines plants, lowering import dependence while supporting export-oriented specialty chemicals clusters. Expanding construction programs in Southeast Asia lift triethanolamine demand for cement grinding aids, while regional utilities deploy amine-based CO2 capture to decarbonize coal and gas-fired plants. Urbanisation unlocks higher per-capita purchases of detergents and personal-care items, embedding a structural pull for surfactant-grade ethanolamines. Collectively, these trends embed a broad-based, medium-term uplift in the ethanolamines market.
Surging glyphosate production for herbicide-tolerant crops
Even as weed-resistance debates intensify, acreage sown with herbicide-tolerant soybean and maize varieties keeps expanding in Brazil, Argentina and the United States, sustaining large synthesis volumes for glyphosate that rely on ethanolamines neutralisation steps. Multinational formulators are relocating production to cost-competitive Asian hubs, giving the ethanolamines market fresh demand corridors without altering global consumption totals. In developing economies, farm-mechanisation campaigns elevate glyphosate usage because labour-saving herbicides remain cheaper than manual weeding. New double-knock programs that mix glyphosate with complementary actives often boost total amine requirements per hectare. Although regulators in the European Union push for reduced synthetic loads, these restrictions typically shift manufacturing to friendlier jurisdictions rather than curbing absolute tonnage. Consequently, near-term momentum from glyphosate maintains a positive swing factor for ethanolamines market growth.
Volatile ethylene oxide feedstock prices
Spot ethylene-oxide quotes remain highly sensitive to naphtha and natural-gas swings, squeezing standalone ethanolamines producers during sudden upcycles. Several South Korean crackers idled in early 2025 because negative olefin margins rendered operations uneconomic, tightening ethylene-oxide supply in the wider Asia-Pacific basin. Integrated majors such as BASF and Dow weather volatility better by reallocating oxide streams to the highest-margin derivatives, underscoring structural advantages that reinforce market concentration. Freight disruptions through the Suez and Panama canals add further unpredictability to feedstock arbitrage flows. Smaller formulators respond by trimming run rates or passing through surcharges, yet prolonged price shocks risk demand destruction in price-sensitive applications like commodity detergents. Net impact is a near-term drag on the ethanolamines market until feedstock trends normalise.
Other drivers and restraints analyzed in the detailed report include:
- Rising demand for water-based metal-working fluids in EV manufacturing
- Increasing utilization in the agrochemical industry
- Increasing weed resistance to weaken glyphosate demand
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Monoethanolamine held 44.62% of 2025 revenues, supported by steady gas-sweetening runs, burgeoning carbon-capture pilots and broad detergent usage. The segment is forecast to post a 6.32% CAGR to 2031, reinforcing its anchor role in the ethanolamines market. Monoethanolamine's high reactivity allows formulators to tailor a wide pH spectrum, sustaining cross-industry relevance. Meanwhile, diethanolamine retains a solid niche in metal-working fluids and herbicide neutralisation, with coproduct value uplift from improved corrosion-inhibition performance. Triethanolamine advances in cement grinding aids, delivering up to 5 MPa compressive-strength gains that shorten curing times on major infrastructure projects.
Diversification across three primary grades protects suppliers from demand swings in any one downstream sector. Carbon-capture retrofits in refineries and steel mills could sharply raise monoethanolamine call-offs, whereas personal-care premiumisation supports triethanolamine margin resilience. Together, these dynamics keep the ethanolamines market well balanced at the product level.
The legacy ethylene-oxide process represented 91.75% of global throughput in 2025, reflecting decades of optimisation and sunk-capital advantages. Even so, the bio-ethanol pathway is predicted to accelerate at a 7.12% CAGR, propelled by renewable-content mandates and corporate net-zero targets. Early commercial plants in Thailand and Brazil demonstrate that agricultural-residue-derived bio-ethylene can integrate seamlessly into existing amination trains, reducing downstream qualification hurdles. Carbon-border-adjustment schemes in Europe tighten the cost gap by pricing embedded emissions, tilting future expenditures toward low-carbon routes.
Process intensification efforts-continuous reaction systems, membrane-based separations and catalysed rearrangements-keep legacy technology competitive on cash cost. Still, brand owners willing to pay premiums for certified-low-carbon molecules grant bio-based suppliers an attractive foothold. The resulting dual-pathway framework ensures ample supply while catalysing technology upgrades across the wider ethanolamines market.
Complete Report Scope:
- By Product Type
- Monoethanolamine (MEA)
- Diethanolamine (DEA)
- Triethanolamine (TEA)
- By Technology
- Ethylene Oxide Route
- Bio-ethanol Route
- By Application
- Gas Treatment
- Herbicides (Glyphosate)
- Surfactants & Detergents
- Cement & Concrete Additives
- Personal-care Formulations
- Metal-working Fluids
- Other Applications
- By End-user Industry
- Oil and Gas
- Agriculture
- Construction
- Personal Care
- Textile
- Metallurgy and Metalworking
- Other End-user Industries
- By Geography
- Asia-Pacifc
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacifc
Geography Analysis
Asia-Pacific dominated with a 46.35% revenue share in 2025, buoyed by integrated petrochemical complexes, competitive labour and expanding downstream manufacturing hubs. Chinese refiners continually debottleneck mono-ethanolamine lines to serve domestic detergent and electronic-chemicals customers, while India's bio-ethanol surge positions the subcontinent as a future export base for renewable ethanolamines. Southeast Asia's agrochemical formulators, concentrated in Thailand and Vietnam, offer further pull as regional crop-protection spending climbs.
North America retains a robust production backbone anchored by Texas and Louisiana oxide-derivative clusters. INEOS's USD 700 million purchase of LyondellBasell's facility secures feedstock for long-term supply contracts with gas-sweetening licensors. Huntsman's E-GRADE expansion in The Woodlands targets semiconductor-purification niches, giving the region a value-added hedge against commodity margin cycles.
Europe's stringent carbon agenda steers investment toward low-emission units, exemplified by BASF's 140,000-ton upgrade in Antwerp. Nouryon's ISCC PLUS accreditation at Stenungsund spurs personal-care demand by enabling traceable renewable content. Carbon-border-adjustment pricing is expected to elevate import premiums on high-emission ethanolamines, indirectly favouring certified European output. Collectively, these regional dynamics sustain a balanced global network that underpins steady flows in the ethanolamines market.
- Amines & Plasticizers ltd.
- BASF
- Dow
- Huntsman Corporation
- INEOS
- NIPPON SHOKUBAI CO., LTD.
- Nouryon
- OUCC
- SABIC
- Sintez OKA Group
- Thai Ethanolamines Co.
- Tosoh Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid industrialisation in emerging economies
- 4.2.2 Surging glyphosate production for herbicide-tolerant crops
- 4.2.3 Rising demand for water-based metal-working fluids in EV manufacturing
- 4.2.4 Increasing utilization in the agrochemical industry
- 4.2.5 Growth in bio-based surfactant formulation in personal-care
- 4.3 Market Restraints
- 4.3.1 Volatile ethylene oxide feedstock prices
- 4.3.2 Increasing Weed Resistance to Weaken the Demand for Glyphosate
- 4.3.3 Emergence of greener bio-solvents challenging ethanolamines
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Monoethanolamine (MEA)
- 5.1.2 Diethanolamine (DEA)
- 5.1.3 Triethanolamine (TEA)
- 5.2 By Technology
- 5.2.1 Ethylene Oxide Route
- 5.2.2 Bio-ethanol Route
- 5.3 By Application
- 5.3.1 Gas Treatment
- 5.3.2 Herbicides (Glyphosate)
- 5.3.3 Surfactants & Detergents
- 5.3.4 Cement & Concrete Additives
- 5.3.5 Personal-care Formulations
- 5.3.6 Metal-working Fluids
- 5.3.7 Other Applications
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Agriculture
- 5.4.3 Construction
- 5.4.4 Personal Care
- 5.4.5 Textile
- 5.4.6 Metallurgy and Metalworking
- 5.4.7 Other End-user Industries
- 5.5 By Geography
- 5.5.1 Asia-Pacifc
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacifc
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Amines & Plasticizers ltd.
- 6.4.2 BASF
- 6.4.3 Dow
- 6.4.4 Huntsman Corporation
- 6.4.5 INEOS
- 6.4.6 NIPPON SHOKUBAI CO., LTD.
- 6.4.7 Nouryon
- 6.4.8 OUCC
- 6.4.9 SABIC
- 6.4.10 Sintez OKA Group
- 6.4.11 Thai Ethanolamines Co.
- 6.4.12 Tosoh Corp.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment