|
시장보고서
상품코드
2121646
농업용 계면활성제 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Agricultural Surfactants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
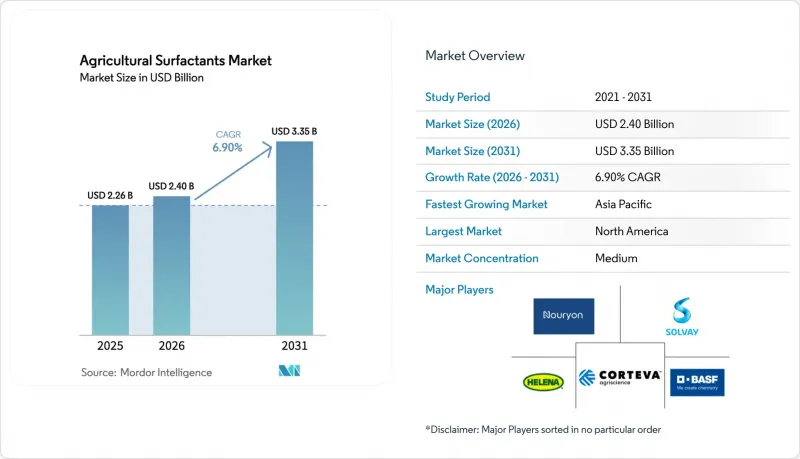
에 의하면, 농업용 계면활성제 시장 규모는 2025년 22억 6,000만 달러에서 2026년에는 24억 달러에 이르고, 2026-2031년 CAGR 6.90%로 성장을 지속하여 2031년까지 33억 5,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 제품 유형(음이온계 등), 용도(살충제 등), 기질(합성계 및 바이오), 작물 용도(작물 기반 등), 형태(액체 및 분말/과립), 기능(습윤제 등), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
전 세계 농업용 계면활성제 시장 동향 및 인사이트
농약 수요 증가가 작물 수확량을 끌어올리고 있습니다.
기후 변화와 해충의 내성화로 인해 각 시즌에 여러 차례 살포가 필요하게 되었으며, 그 결과 1헥타르당 계면활성제 사용량이 증가하고 있습니다. 브라질에서는 2024년 8월에 100종의 새로운 작물 보호 제품이 승인되어, 이로 인해 대두 및 옥수수용 보조제 수요가 증가할 것으로 예측됩니다. 인도에서는 2024년에 농약 매출이 크게 증가했으나, 경수 시장 진출이 과제로 남아 있어 계면활성제의 성장률이 유효 성분을 상회했습니다. 중국에서는 2025년, 쌀과 밀의 노동력 부족을 배경으로 제초제 매출이 증가하면서, 잎 표면에 부착하기 위해 보조제가 필요한 화학적 잡초 방제에 대한 수요가 높아졌습니다. 표면 장력이 30다인/cm 미만이어야 하는 발아 후 제초제 수요가 급증함에 따라, 소규모 농가에서는 비이온성 및 유성계 화학 물질이 선호되고 있습니다.
정밀 농업의 도입으로 계면활성제 사용 증가
가변 살포량식 분무기는 현재 수관 밀도, 토양 수분, 풍속에 따라 보조제 투여량을 조정하고 있습니다. 2024년에는 북미 농장에서의 보급률이 상승할 전망이며, 2024년 11월 코르테바(Corteva)가 공개한 알고리즘은 개별적으로 최적화된 계면활성제 혼합물을 권장하고 있어, 이를 통해 총 살포량을 20% 줄이고 장비 가동 시간을 연장하고 있습니다. 유럽의 드리프트 저감 규제로 인해, 액적 크기를 좁은 범위 내로 유지하는 노즐 기술 및 보조제 제형에 대한 투자가 가속화되고 있습니다. 호주의 곡물 지대에서는 GPS 붐과 인라인식 계면활성제 주입 장치를 연동하여, 시즌당 보조제 낭비를 15% 줄이고 있습니다.
바이오 유래 원료의 높은 생산 비용
발효 유래 지방 알코올은 석유계 원료에 비해 비용을 최대 40%까지 끌어올리고 있습니다. 인도네시아가 수출 규제를 강화함에 따라 2025년 초 팜유 가격이 22% 상승하여 비이온성 원료의 비용을 상승시켰습니다. 2024년부터 2025년에 걸쳐 에틸렌옥사이드 가격이 30-35% 변동함에 따라, 장기 계약을 맺지 않은 소규모 제제 제조업체들은 곤경에 처하게 되었고, 통합형 대기업에 대한 경쟁력이 약화되었습니다. 팜유와 대두유 가격의 급등은 밸류체인 전반에 파급되어, 바이오계 계면활성제 중간체의 계약 가격을 한 분기 만에 두 자릿수 비율로 끌어올렸습니다. 수직 통합을 실시하지 않은 배합 제조업체는 이러한 가격 변동을 흡수하거나 생산자에게 전가할 수밖에 없으나, 후자의 전략은 가격에 민감한 농작물 수요를 잠식하게 됩니다.
부문 분석
2025년에는 비이온성 화합물이 41%의 점유율을 차지했습니다. 이는 폭넓은 혼용성과 경수에 대한 내성이 높이 평가되었기 때문입니다. 발아 후 제초제에는 큐티클 깊숙이 침투하는 능력이 요구되므로, 유계 대체재 시장은 연평균 성장률(CAGR) 13.2%로 확대되고 있습니다. 노닐페놀 에톡실레이트의 규제 및 단계적 폐지에 따라 1억 8,000만-2억 2,000만 달러 규모의 대체 수요가 발생하고 있습니다. BASF사의 ‘Sokalan CP 301’과 같은 바이오 유래 비이온성 계면활성제는 재생 가능 원료로의 전환을 주도하고 있습니다.
농업용 계면활성제 시장은 시즌 초반의 한파에도 합성 제품의 내구성이 강점으로 작용하는 반면, 하이브리드 블렌드는 비용과 지속가능성의 균형을 맞추고 있습니다. 양성이온성 및 양이온성 제품은 여전히 틈새 시장으로 자리 잡고 있지만, 수생 잡초 방제 프로그램 및 pH 완충 탱크 혼합을 통해 성장을 이어가고 있습니다. 클라리언트(Clariant)사의 수화제용 ‘디스파소젠 TP 100 T’와 같은 분산제 분야에서는 혁신이 계속되고 있으며, 이 성숙한 부문에서의 지속적인 혁신이 강조되고 있습니다. 한편, 애슈랜드(Ashland)사가 2024년 9월에 상용화한 초습윤제 ‘이지? 300 n’은 정밀 살포 분야의 저표면장력 용도를 목표로 하고 있습니다.
2025년에는 제초제 용도가 계면활성제 소비량의 46%를 차지할 것으로 예상되며, 이는 연작 농업에서 글리포세이트, 글루포시네이트 및 디캄바 프로그램이 주류를 이루고 있음을 반영합니다. 살균제용 보조제는 고부가가치 작물의 생육 후기 병해 압력 증가와 미생물의 생존성을 유지하기 위해 비이온성이며 저독성인 보조제가 필요한 생물학적 살균제의 보급에 힘입어 연평균 성장률(CAGR) 12.4%로 성장하고 있습니다. 살충제용 보조제는 아시아태평양의 면화 및 벼 재배에서 수요가 확대되고 있으며, 이는 통합 해충 관리(IPM)에 따라 살포 피복률 향상이 요구되고 있기 때문입니다.
BASF가 2024년 10월 AgroSpheres사와 체결한 생물학적 살충제 전달 플랫폼에 관한 제휴는 생물학적 작물 보호 분야에서 계면활성제의 적합성이 갖는 전략적 중요성을 보여주고 있으며,이 부문은 2030년까지 전 세계적으로 120억 달러에 달할 것으로 예측됩니다. 트리아졸계 및 스트로빌린계 살균제와의 적합성이 제품 설계를 좌우하고 있으며, 누리욘의 ‘Adsee Flex 960’이 그 대표적인 예입니다. 드론 살포기의 보급으로 전신성 제초제 수요가 증가함에 따라 침투 촉진제에 대한 수요도 강해지고 있습니다. 또한, 탱크 혼합의 간편함 덕분에 습윤, 침투, 드리프트 억제 기능을 겸비한 다목적 제제의 개발도 진행되고 있습니다.
지역별 분석
2025년에는 북미가 38%의 점유율을 차지하며 시장을 선도했습니다. 대규모 줄 재배 농업에서는 수관 지도에 맞추어 보조제 투여량을 조정하는 정밀 살포기가 도입되어, 이를 통해 물 사용량을 최대 30%까지 절감하고 있습니다. 미국 환경보호청(EPA)의 ‘농약 등록 개선법’에 따른 규제의 영향으로, 기존 계면활성제의 재조성이 시급해지고 있습니다. 멕시코 농업 부문에서는 아보카도와 베리류 생산에 계면활성제 사용이 확대되고 있으며, 이러한 수출 시장에서는 엄격한 잔류 기준치를 충족하는 무잔류 농산물이 요구되고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 11.5%로 가장 빠른 성장세를 보이고 있습니다. 인도의 경수 조건과 중국의 노동력 부족으로 인해 보조제 수요가 증가하고 있으며, 드론을 이용한 살포 프로그램으로 적재량이 75% 감소했습니다. 중국에서는 2024년에 항공 살포에 관한 규제 승인 절차가 간소화됨에 따라, 드론 살포용 초고농도 제제가 급속히 보급되고 있습니다. 열대 지역에서는 습도로 인한 식물 독성 문제로 나노 에멀젼의 도입이 지연되고 있지만, 한편으로는 쌀과 대두에 적합한 수분 반응성 블렌드의 개발이 가속화되고 있습니다.
유럽에서는 생분해성 자재를 장려하는 REACH 규정과 탄소세를 지침으로 삼아 진전이 보이고 있습니다. 독일, 프랑스, 영국이 드리프트 억제 기술에 대한 투자를 주도하고 있습니다. 남미에서는 브라질이 작물 보호제 등록을 늘리고, 확대되는 대두 재배 면적에서 전신성 제초제의 보급을 추진하고 있어 시장이 성장하고 있습니다. 아프리카 및 중동의 성장은 농업의 집약화와 정밀 관개에 힘입고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the agricultural surfactants market size is anticipated to grow from USD 2.26 billion in 2025 to USD 2.40 billion in 2026 and is forecast to reach USD 3.35 billion by 2031 at a 6.90% CAGR over 2026-2031.
This report is Segmented by Product Type (Anionic, and More ), by Application (Insecticide, and More), by Substrate (Synthetic, and Bio-Based), by Crop Application (Crop-Based, and More), by Form (Liquid, and Powder/Granular), by Function (Wetting Agent, and More), and by Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Agricultural Surfactants Market Trends and Insights
Rising Demand for Agrochemicals to Boost Crop Yield
Climate swings and pest resistance necessitate multiple spray passes each season, resulting in increased surfactant kilograms per hectare. Brazil cleared 100 new crop-protection products in August 2024, which is anticipated to lift demand for soybean and corn adjuvants. India's pesticide sales increased significantly in 2024, with surfactants outpacing actives due to challenges in penetrating hard water. China experienced growth in herbicide sales in 2025, amid labor shortages in rice and wheat, which led to increased demand for chemical weed control that relies on adjuvants for leaf adhesion. The spike in post-emergence herbicides that need surface tension below 30 dynes/cm favors nonionic and oil-based chemistries on smallholder farms.
Precision-Farming Adoption Increasing Surfactant Usage
Variable-rate sprayers now modulate adjuvant dose by canopy density, soil moisture, and wind speed. North American farm penetration increased in 2024, and algorithms showcased by Corteva in November 2024 recommend bespoke surfactant blends, trimming total spray volume by 20% and extending equipment uptime. Europe's drift-reduction rules accelerate investment in nozzle technology and adjuvant formulations that hold droplet size within tight bands. Australia's grain belt links GPS booms with inline surfactant injectors, cutting adjuvant waste by 15% per season.
High Production Cost of Bio-Based Raw Materials
Fermentation-derived fatty alcohols raise costs by up to 40% versus petroleum feedstocks. Palm oil rose 22% in early 2025 after Indonesia tightened exports, inflating nonionic input costs. Ethylene oxide volatility of 30-35% from 2024-2025 hampered small formulators that lack long contracts, undermining competitiveness against integrated majors. Price spikes in palm and soybean oil cascade through the value chain, lifting contract prices for bio-surfactant intermediates by double digits within a single quarter. Formulators without vertical integration must absorb this volatility or pass it to growers, a strategy that erodes demand in price-sensitive row crops.
Other drivers and restraints analyzed in the detailed report include:
- Growing Focus on Sustainable and Bio-Based Surfactants
- Nano-Surfactant Innovations Enabling Ultra-Low Doses
- Stringent Regulations on Chemical Residues
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Nonionic chemistries controlled 41% share in 2025, favored for broad compatibility and hard-water tolerance. Oil-based alternatives rise at 13.2% CAGR as post-emergence herbicides need deeper cuticle penetration. Regulatory phase-outs of nonylphenol ethoxylates open a USD 180-220 million replacement pool. Bio-based nonionics, such as BASF's Sokalan CP 301, anchor the pivot toward renewable content.
The agricultural surfactants market benefits from synthetic robustness in early-season cold spells, while hybrid blends balance cost and sustainability. Amphoteric and cationic options stay niche yet grow with aquatic weed programs and pH-buffered tank mixes. Innovation continues in dispersants such as Clariant's Dispersogen TP 100 T for wettable powders, underscoring ongoing innovation in this mature segment, while Ashland's easy-wet 300 n super wetting agent, commercialized in September 2024, targets low-surface-tension applications in precision spraying.
Herbicide applications commanded 46% of surfactant consumption in 2025, reflecting the dominance of glyphosate, glufosinate, and dicamba programs in row-crop agriculture. Fungicide-friendly adjuvants grow at 12.4% CAGR driven by late-season disease pressure in high-value crops and the proliferation of biological fungicides that demand non-ionic, low-toxicity adjuvants to preserve microbial viability. Insecticide adjuvants rise in Asia-Pacific cotton and rice, where integrated pest management boosts coverage needs.
BASF's October 2024 partnership with AgroSpheres on bioinsecticide delivery platforms illustrates the strategic importance of surfactant compatibility in biological crop protection, a segment forecast to reach USD 12 billion globally by 2030. Compatibility with triazole and strobilurin fungicides steers product design, as evidenced by Nouryon's Adsee Flex 960. Drone sprayers elevate systemic herbicide needs, reinforcing demand for penetrant agents. Tank-mix simplicity also drives multipurpose formulations that combine wetting, penetration, and drift control.
Complete Report Scope:
- By Product Type
- Anionic
- Nonionic
- Cationic
- Amphoteric
- Oil-based Surfactants
- By Application
- Herbicide
- Insecticide
- Fungicide
- Other Applications
- By Substrate
- Synthetic
- Bio-based
- By Crop Application
- Crop-based
- Grains and Cereals
- Oilseeds
- Fruits and Vegetables
- Non-crop-based
- Turf and Ornamental Grass
- Other Crop Applications
- Crop-based
- By Form
- Liquid
- Powder/Granular
- By Function
- Wetting Agent
- Dispersant
- Penetrant/Adjuvant
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America dominated with 38% share in 2025. Large row-crop operations embrace precision sprayers that align adjuvant dose with canopy maps, reducing water use by up to 30%. Regulatory influence from the EPA's Pesticide Registration Improvement Act is forcing reformulation of legacy surfactants. Mexico's agricultural sector is expanding surfactant usage in avocado and berry production, where export markets demand residue-free produce that meets stringent maximum residue limits.
Asia-Pacific represents the fastest expansion at 11.5% CAGR. India's hard-water conditions and China's labor shortages elevate adjuvant requirements, and drone programs compress payload volume by 75%. Ultra-high-concentration formulations for drone spraying are advancing rapidly in China, where regulatory approvals for aerial application were streamlined in 2024. Humidity-driven phytotoxicity in tropical zones slows nano-emulsion rollouts but accelerates development of moisture-responsive blends suited for rice and soybean.
Europe advances, guided by REACH and carbon taxes that reward biodegradable inputs. Germany, France, and the United Kingdom lead investments in drift-control technology. South America is growing as Brazil adds crop-protection registrations and pushes systemic herbicide penetration in its expanded soybean acreage. Africa and the Middle East's growth is supported by intensification and precision irrigation.
- Corteva Agriscience
- BASF SE
- RAG-Stiftung
- Croda International Plc
- Solvay SA
- Nouryon
- Clariant International Ltd.
- Wilbur-Ellis Company LLC
- Nufarm
- Kao Corporation
- Lamberti S.p.A.
- Brandt, Inc.
- GarrCo Products, Inc.
- Bionema
- Innospec Inc.
- Stepan Company
- Loveland Products, Inc. (Nutrien)
- Norac Concepts Inc.
- Marubeni Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for agrochemicals to boost crop yield
- 4.2.2 Precision-farming adoption increasing surfactant usage
- 4.2.3 Growing focus on sustainable and bio-based surfactants
- 4.2.4 Nano-surfactant innovations enabling ultra-low doses
- 4.2.5 Biological crop-protection compatibility requirements
- 4.2.6 Ultra-high-concentration formulations for drone spraying
- 4.3 Market Restraints
- 4.3.1 High production cost of bio-based raw materials
- 4.3.2 Stringent regulations on chemical residues
- 4.3.3 Feed-stock supply volatility for specialty ethoxylates
- 4.3.4 Phytotoxicity concerns with nano-formulations in humid tropics
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size And Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Anionic
- 5.1.2 Nonionic
- 5.1.3 Cationic
- 5.1.4 Amphoteric
- 5.1.5 Oil-based Surfactants
- 5.2 By Application
- 5.2.1 Herbicide
- 5.2.2 Insecticide
- 5.2.3 Fungicide
- 5.2.4 Other Applications
- 5.3 By Substrate
- 5.3.1 Synthetic
- 5.3.2 Bio-based
- 5.4 By Crop Application
- 5.4.1 Crop-based
- 5.4.1.1 Grains and Cereals
- 5.4.1.2 Oilseeds
- 5.4.1.3 Fruits and Vegetables
- 5.4.2 Non-crop-based
- 5.4.2.1 Turf and Ornamental Grass
- 5.4.2.2 Other Crop Applications
- 5.4.1 Crop-based
- 5.5 By Form
- 5.5.1 Liquid
- 5.5.2 Powder/Granular
- 5.6 By Function
- 5.6.1 Wetting Agent
- 5.6.2 Dispersant
- 5.6.3 Penetrant/Adjuvant
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.1.4 Rest of North America
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Spain
- 5.7.2.5 Italy
- 5.7.2.6 Russia
- 5.7.2.7 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 India
- 5.7.3.3 Japan
- 5.7.3.4 Australia
- 5.7.3.5 Rest of Asia-Pacific
- 5.7.4 South America
- 5.7.4.1 Brazil
- 5.7.4.2 Argentina
- 5.7.4.3 Rest of South America
- 5.7.5 Middle East
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Turkey
- 5.7.5.4 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Nigeria
- 5.7.6.3 Rest of Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Corteva Agriscience
- 6.4.2 BASF SE
- 6.4.3 RAG-Stiftung
- 6.4.4 Croda International Plc
- 6.4.5 Solvay SA
- 6.4.6 Nouryon
- 6.4.7 Clariant International Ltd.
- 6.4.8 Wilbur-Ellis Company LLC
- 6.4.9 Nufarm
- 6.4.10 Kao Corporation
- 6.4.11 Lamberti S.p.A.
- 6.4.12 Brandt, Inc.
- 6.4.13 GarrCo Products, Inc.
- 6.4.14 Bionema
- 6.4.15 Innospec Inc.
- 6.4.16 Stepan Company
- 6.4.17 Loveland Products, Inc. (Nutrien)
- 6.4.18 Norac Concepts Inc.
- 6.4.19 Marubeni Corporation