|
시장보고서
상품코드
2121654
생분해성 포장 솔루션 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Biodegradable Packaging Solutions - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
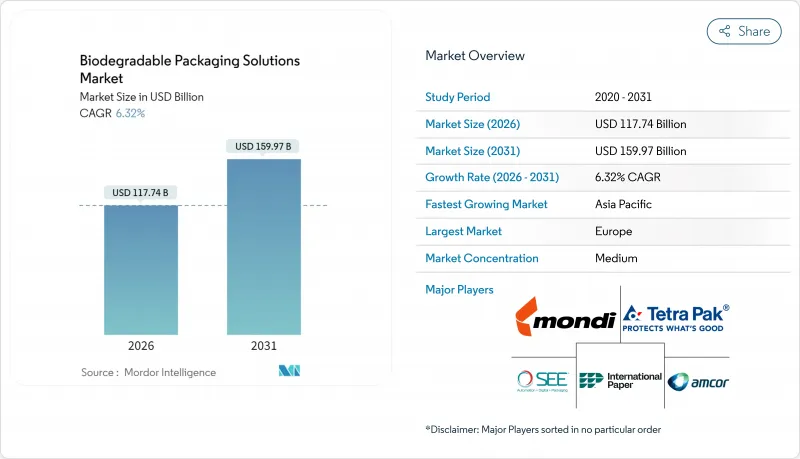
에 따르면 생분해성 포장 솔루션 시장 규모는 2026년에 1,177억 4,000만 달러에 달하고, 2031년까지 1,599억 7,000만 달러에 달할 것으로 예측됩니다.
이는 2026년부터 2031년까지 연평균 성장률(CAGR)이 6.32%를 기록할 것임을 나타내며, 해당 부문의 꾸준한 성장 추세를 뒷받침합니다.
본 보고서는 소재 유형(바이오플라스틱, 종이, 성형 펄프 섬유, 식물 유래 복합재), 포장 형태(경질, 연질), 최종사용자 산업(식품, 음료, 헬스케어, 퍼스널케어, E-Commerce 등), 유통 채널(직접, 간접), 지역(아메리카 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 생분해성 포장 솔루션 시장의 동향 및 인사이트
순환형·제로 웨이스트 포장에 대한 소비자 수요 증가
2025년에 실시된 소비자 조사에 따르면, 유럽 및 북미 쇼핑객의 67%가 구매 결정 시 제품 수명 종료 후의 폐기를 고려하고 있으며, 이는 2023년의 52%에서 증가한 수치입니다. 특히 밀레니얼 세대와 Z세대 구매자들은 지속가능성에 대한 주장이 불충분하다고 느끼면 브랜드를 바꾸는 경향이 있으며, 이에 따라 패스트푸드점에서는 시범 도입 도시에서 플라스틱 폐기물을 15-20% 줄인 퇴비화 가능한 식기 및 클램쉘 용기의 시범 운영을 시작했습니다. 이에 대응해 각 컨버터 기업들은 브랜드가 인증 절차나 포장재의 폐기 방법에 관한 표시 요건을 충족할 수 있도록 지원하는 기술 지원 팀을 강화하고 있습니다. 소매업체들은 신소재의 저위험 시험 무대로 자체 브랜드를 활용하고 있으며, 이를 통해 상업적 실증 주기가 가속화되고 있습니다. 이러한 행동의 변화는 바이오폴리머의 비용 상승을 상쇄하는 안정적인 가격 프리미엄을 뒷받침하며, 생분해성 포장 솔루션 시장에 대한 장기적인 수요를 촉진하고 있습니다.
도시 지역의 퇴비화 인프라 확충
유럽연합(EU)은 2024-2025년도 결속 기금에서 23억 유로(26억 달러)를 배정하여,동유럽 전역에 혐기성 소화 시설 및 풍건 퇴비화 시설을 건설하여, 2030년까지 유기 폐기물의 자원화율을 50%로 높이는 것을 목표로 하고 있습니다. 샌프란시스코나 토론토 등 북미의 도시에서는 가정에서 발생하는 유기성 폐기물의 문 앞 수거가 의무화되어 있어, 이를 통해 퇴비화 사업자에게 안정적인 원료 공급이 확보될 뿐만 아니라 실제 사용 환경에서의 포장 성능이 입증되고 있습니다. 중국의 주택도시농촌발전부는 46개 도시에서 음식물 쓰레기 분리수거 프로그램을 시범적으로 시행하고 있으며, 한편 인도의 ‘스마트 시티 미션’에서는 지자체의 보조금 지급을 퇴비화 실적과 연계하고 있습니다. 인프라 밀도가 높아짐에 따라 브랜드 소유자의 평판 리스크가 감소할 뿐만 아니라, 퇴비화 거점에 가까운 컨버터에게는 폐쇄형 회수 체계를 통해 물류상의 우위가 제공됩니다.
바이오폴리머용 농업 원료 공급량의 변동
2024년부터 2025년까지 옥수수와 사탕수수 가격은 18-24% 변동했으며, 심각한 가뭄의 영향으로 미국의 옥수수 수확량은 12% 감소했습니다. 브라질 생산자들은 사탕수수 재배 면적을 대두로 전환함에 따라 사탕수수 생산량이 7% 감소하여 PLA 생산자를 위한 공급이 부족해졌습니다. 헤지 능력이 부족한 중소 규모의 가공업체들은 이러한 가격 변동을 흡수하는 데 어려움을 겪고 있으며, 브랜드 출시를 지연하거나 토탈 코비온(Total Corbion)과 같은 대규모 수직 통합 경쟁사들에게 시장 점유율을 내주기도 합니다. 원료 가격의 불안정성은 퇴비화 가능한 포장재의 비용이 브랜드 소유자의 비용 상한선을 초과할 경우, 대체화 추세를 둔화시키고 생분해성 포장재 솔루션 시장의 단기적인 확장을 억제할 가능성이 있습니다.
부문 분석
2025년, 생분해성 포장 솔루션 시장 규모에서 바이오플라스틱은 48.21%의 점유율을 유지했습니다. 이는 주로 PLA가 기존의 압출 성형 및 열 성형 설비와 호환되어 전환 시 자본 지출을 최소화할 수 있기 때문입니다. 전분계 폴리머는 느슨한 충전재나 농업용 멀칭과 같은 저성능 틈새 시장을 차지하고 있는 반면, 셀룰로오스 유도체는 투명성과 인쇄성을 요구하는 고급 퍼스널케어 브랜드에서 채택되고 있습니다. PHA는 해양 생분해성을 이유로 가격 프리미엄이 붙어 있으며, 해안 지역의 호텔·레스토랑 업계와 해산물 체인점에서 선호되고 있습니다. PBS 등급은 뛰어난 내열성을 갖추고 있어 상온 보관이 가능한 소스나 즉석식사의 개발을 가능하게 합니다.
버섯 균사체, 해조류 필름, 사탕수수 찌꺼기 섬유 등의 식물 유래 복합 소재는 고급 전자기기 및 화장품 제조사들이 질감이 풍부하고 스토리성이 있는 기재를 요구함에 따라 2031년까지 연평균 성장률(CAGR) 7.42%로 성장할 것으로 예측되며, 이는 모든 소재 중 가장 높은 성장률입니다. Ecovative Design사의 균사체 완충재는 플라스틱을 사용하지 않는 보호 포장을 원하는 전자기기 브랜드들로부터 지지를 얻고 있습니다. 물에 녹는 해조류 유래 소형 봉지는 조미료 팩에 참신한 사용자 경험을 제공하고 있는 반면, 바가스 트레이는 스티로폼 사용을 배제하려는 패스트푸드점으로부터 지지를 얻고 있습니다. 이러한 다양성은 기능적 성능과 스토리성 있는 마케팅이 결합되어 생분해성 포장 솔루션 시장이 얼마나 큰 혜택을 누리고 있는지를 여실히 보여줍니다.
2025년에는 유연한 형태의 제품이 56.32%의 점유율을 차지했습니다. 이는 E-Commerce 배송 포장이나 패스트푸드점 포장에서 매우 중요한, 제품에 대한 낮은 질량비와 높은 운송 효율을 반영한 것입니다. 바이오 배리어 코팅을 통해 산소 투과성 문제가 개선됨에 따라 반려동물 사료 및 커피용 파우치가 널리 보급되었습니다. 한편, 경질 용기는 음료 및 유제품 제조업체들이 PET의 대안으로 시범 도입하고 있는 성형 펄프 병과 용기에 힘입어 2031년까지 연평균 성장률(CAGR) 7.89%라는 견실한 성장세를 보일 것으로 예측됩니다.
스트라 엔소(Stora Enso)사의 목질 섬유 복합 병은 섬유로 만든 본체와 얇은 바이오 라이너를 결합함으로써 발전을 보이고 있습니다. 병과 항아리는 바이오폴리머 사용에 있어 여전히 용융 강도라는 과제에 직면해 있지만, 이러한 과제를 해결하기 위한 활발한 연구 개발이 진행되고 있습니다. 유연 포장재의 장점과 경질 포장재의 급속한 보급이 공존하는 상황은 생분해성 포장 솔루션 시장에서 재료 효율성과 사용 후 분리 수거 용이성 사이의 상충 관계를 반영하고 있습니다.
지역별 분석
2025년, 유럽은 생분해성 포장 솔루션 시장 점유율의 40.21%를 차지했습니다. 이는 2030년까지 재활용성 또는 퇴비화성을 의무화하는 ‘포장 및 포장 폐기물 규정’에 더해, 독일, 프랑스, 네덜란드의 확립된 퇴비화 네트워크에 힘입은 결과입니다. 독일의 ‘포장법(Verpackungsgesetz)’은 재생 재료 함유율 기준을 더욱 엄격히 강화한 반면, 프랑스는 2025년에 일회용 플라스틱 금지 대상을 신선 식품 포장까지 확대하여 소재 대체를 가속화했습니다. 영국은 브렉시트 이후 ‘플라스틱 포장세’를 조정하여 유럽 대륙과의 규제 일관성을 유지했습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.85%라는 가장 높은 성장 궤도에 올라 있습니다. 중국의 2024년 지침은 2030년까지 일회용 플라스틱을 40% 감축하는 것을 목표로 하고 있으며, PLA 및 PHA 생산능력에 대한 투자를 촉진하고 있습니다. 인도의 개정된 ‘플라스틱 폐기물 관리 규정’은 퇴비화 가능한 대체재의 사용을 장려하고 있으나, 그 시행 상황은 주마다 다릅니다. 일본의 ‘녹색 조달법’은 공공 조달 분야의 수요를 뒷받침하고 있으며, 호주의 2025년 포장 목표는 국내 브랜드들이 퇴비화 가능한 형태로 전환하도록 촉진하고 있습니다. 중산층의 확대와 E-Commerce의 급속한 성장이 소비에 호재로 작용하며, 생분해성 포장 솔루션 시장에 대한 지역적 수요를 더욱 높이고 있습니다.
북미에서는 캘리포니아주, 오리건주, 콜로라도주, 메인주에서 EPR(확대 생산자 책임) 제도가 도입되어 긍정적인 영향을 미치고 있지만, 연방 차원의 통일된 기준이 없어 규정 준수 상황은 지역마다 제각각입니다. 캐나다의 2024년 연방 EPR 체계는 주별 차이를 해소하고 퇴비화 가능한 제품의 채택률을 높일 것입니다. 멕시코는 미국 브랜드와 가까운 지리적 이점을 활용하여 가공업체를 위한 니어쇼어링 거점으로서의 입지를 확고히 하고 있습니다. 남미 시장은 아직 발전 단계에 있으며, 브라질과 아르헨티나에서는 퇴비화 인프라의 불균형과 가격에 대한 민감성이 장벽으로 작용하고 있습니다. 중동 및 아프리카에서는 산발적인 도입 사례가 나타나고 있습니다. 특히 아랍에미리트와 남아프리카공화국에서는 관광업 및 수출 지향형 부문이 지속가능성 노력을 중시하고 있지만, 시장이 더 폭넓게 발전하기 위해서는 인프라 구축이 시급합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액 기준)
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.07According to Mordor Intelligence, the biodegradable packaging solutions market size reached USD 117.74 billion in 2026 and is projected to advance to USD 159.97 billion by 2031, reflecting a CAGR of 6.32% over 2026-2031 and confirming the sector's steady upward trajectory.
This report is Segmented by Material Type (Bioplastics, Paper, Molded Pulp Fiber, and Plant-Based Composites), Packaging Format (Rigid, and Flexible), End-User Industry (Food, Beverage, Healthcare, Personal Care, E-Commerce, and More), Distribution Channel (Direct, and Indirect), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Biodegradable Packaging Solutions Market Trends and Insights
Growing Consumer Demand for Circular, Zero-Waste Packaging
Consumer surveys conducted in 2025 indicate that 67% of shoppers in Europe and North America now consider end-of-life disposal when making purchasing decisions, up from 52% in 2023. Millennials and Gen Z buyers, in particular, switch brands when sustainability claims appear weak, prompting quick-service restaurants to pilot compostable cutlery and clamshells that trimmed plastic waste by 15-20% in trial cities. Converters are responding by bolstering their technical-support teams, which help brands navigate certification processes and on-pack disposal messaging. Retailers use private-label lines as low-risk test beds for new materials, accelerating commercial validation cycles. This behavioral shift underpins stable price premiums that offset higher biopolymer costs and reinforces long-run demand for the biodegradable packaging solutions market.
Expansion of Composting Infrastructure in Urban Centers
The European Union allocated EUR 2.3 billion (USD 2.60 billion) from the 2024-2025 cohesion funds to build anaerobic digestion and windrow facilities across Eastern Europe, targeting a 50% organic waste diversion rate by 2030. North American cities, such as San Francisco and Toronto, mandate curbside organics collection, ensuring a steady feedstock for compost operators and validating packaging performance under real-world conditions. China's Ministry of Housing and Urban-Rural Development is piloting food-waste separation programs in 46 cities, while India's Smart Cities Mission ties municipal grants to composting performance. Greater infrastructure density lowers reputational risk for brand owners and grants converters near composting hubs a logistics advantage through closed-loop take-back schemes.
Volatile Availability of Agricultural Feedstocks for Biopolymers
Corn and sugarcane prices fluctuated 18-24% during 2024-2025, with U.S. corn yields down 12% after severe droughts. Brazilian growers diverted acreage from sugarcane to soybeans, cutting cane output by 7% and tightening supply for PLA producers. Smaller converters lacking hedging capacity struggle to absorb these swings, sometimes delaying brand rollouts or ceding share to larger, vertically integrated rivals such as Total Corbion. Feedstock price instability can dampen substitution momentum if compostable formats exceed brand owners' cost ceilings, potentially moderating near-term expansion of the biodegradable packaging solutions market.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory Extended Producer Responsibility Schemes Globally
- Advances in High-Barrier Bio-Based Coatings Unlocking New Applications
- Inadequate Sorting and Certification Standards Across Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bioplastics retained a 48.21% share of the biodegradable packaging solutions market size in 2025, largely due to PLA's compatibility with existing extrusion and thermoforming assets, which minimizes capital outlay during the transition. Starch-based polymers occupy low-performance niches such as loose-fill and agricultural mulch, while cellulose derivatives satisfy premium personal-care labels that demand transparency and printability. PHA fetches a price premium for marine biodegradability, appealing to coastal hospitality and seafood chains. PBS grades offer superior heat resistance, unlocking shelf-stable sauces and ready meals.
Plant-based composites, such as mushroom mycelium, seaweed films, and bagasse fibers, are forecast to grow at a 7.42% CAGR through 2031, the fastest among materials, as luxury electronics and cosmetics adopters seek texture-rich, story-driven substrates. Ecovative Design's mycelium cushioning wins with electronics brands seeking plastic-free protective formats. Seaweed-based sachets that dissolve in water offer a novel user experience for condiment packets, while bagasse trays are gaining favor with quick-service restaurants seeking to eliminate expanded polystyrene. This diversity underscores how the biodegradable packaging solutions market benefits when functional performance and narrative marketing intersect.
Flexible formats commanded a 56.32% share in 2025, reflecting their lower mass-to-product ratio and transport efficiency, which are crucial for e-commerce mailers and quick-service wraps. Pouches for pet food and coffee gained traction as bio-barrier coatings narrowed oxygen-permeation gaps. Conversely, rigid formats are projected to track a robust 7.89% CAGR to 2031, driven by molded-pulp bottles and jars that beverage and dairy players are piloting to replace PET.
Stora Enso's wood-fiber composite bottle demonstrates progress, pairing a fiber body with a thin bio-liner. Bottles and jars still face melt-strength hurdles with biopolymers, but active R&D is aimed at closing these gaps. The coexistence of flexible leadership and rigid acceleration reflects trade-offs between material efficiency and post-use sorting clarity within the biodegradable packaging solutions market.
Complete Report Scope:
- By Material Type
- Bioplastics
- Starch-Based Plastics
- Cellulose-Based Plastics
- Polylactic Acid (PLA)
- Polyhydroxyalkanoates (PHA)
- Polybutylene Succinate (PBS)
- Other Compostable Polymers
- Paper
- Molded Pulp Fiber
- Plant-Based Composites (Mushroom, Seaweed, Bagasse)
- Bioplastics
- By Packaging Format
- Rigid Packaging
- Bottles and Jars
- Trays and Clamshells
- Boxes and Cartons
- Other Rigid Packagings
- Flexible Packaging
- Films and Wraps
- Pouches and Bags
- Other Flexible Packagings
- Rigid Packaging
- By End-User Industry
- Food
- Beverage
- Healthcare and Pharmaceuticals
- Personal Care and Cosmetics
- E-Commerce and Retail
- Other End-user Industries
- By Distribution Channel
- Direct Sales
- Indirect Sales
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Europe contributed 40.21% of the biodegradable packaging solutions market share in 2025, driven by the Packaging and Packaging Waste Regulation, which mandates recyclability or compostability by 2030, and by well-established composting networks in Germany, France, and the Netherlands. Germany's Verpackungsgesetz further tightened recycled-content thresholds, while France extended its ban on single-use plastics to fresh produce packaging in 2025, accelerating material substitution. The United Kingdom aligned its Plastic Packaging Tax post-Brexit, maintaining regulatory coherence with continental Europe.
Asia-Pacific is on track for the fastest 8.85% CAGR through 2031. China's 2024 guidelines aim for a 40% reduction in single-use plastics by 2030 and spur investments in PLA and PHA capacity. India's amended Plastic Waste Management Rules encourage the use of compostable alternatives, although enforcement varies by state. Japan's Green Purchasing Law boosts demand in public procurement, and Australia's 2025 packaging targets push national brands toward compostable formats. An expanding middle class and rapid e-commerce growth add consumption tailwinds, amplifying regional pull for the biodegradable packaging solutions market.
North America benefits from EPR rollouts in California, Oregon, Colorado, and Maine, yet lacks federal harmonization, creating patchwork compliance terrain. Canada's 2024 federal EPR framework simplifies provincial divergence and elevates compostable adoption rates. Mexico's proximity to U.S. brands positions it as a near-shoring hub for converters. South America remains nascent, with Brazil and Argentina hindered by uneven compost infrastructure and price sensitivity. The Middle East and Africa show sporadic adoption most notably in the United Arab Emirates and South Africa, where tourism and export-oriented sectors value sustainability credentials, though broader market development awaits infrastructure build-out.
- Amcor plc
- Mondi Group
- Smurfit WestRock
- Tetra Pak International SA
- Sealed Air Corporation
- International Paper Company
- Ranpak Holding Corporation
- Huhtamaki Oyj
- Stora Enso Oyj
- NatureWorks LLC
- BASF SE
- Novamont SpA
- Total Corbion PLA
- Elevate Packaging Inc.
- BioPak Pty Ltd (Duni Group)
- Kruger Inc.
- Greenpack Limited
- Berkley International Packaging Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Consumer Demand for Circular, Zero-Waste Packaging
- 4.2.2 Expansion of Composting Infrastructure in Urban Centers
- 4.2.3 Mandatory Extended Producer Responsibility Schemes Globally
- 4.2.4 Advances in High-Barrier Bio-Based Coatings Unlocking New Applications
- 4.2.5 Rapid Capacity Additions for PLA and PHA in Asia-Pacific
- 4.2.6 Retailers' Private-Label Sustainability Targets Accelerating Adoption
- 4.3 Market Restraints
- 4.3.1 Volatile Availability of Agricultural Feedstocks for Biopolymers
- 4.3.2 Inadequate Sorting and Certification Standards Across Regions
- 4.3.3 Performance Gaps in Moisture and Oxygen Barrier vs Conventional Plastics
- 4.3.4 Risk of Greenwashing Litigations Increasing Compliance Costs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS ( VALUE)
- 5.1 By Material Type
- 5.1.1 Bioplastics
- 5.1.1.1 Starch-Based Plastics
- 5.1.1.2 Cellulose-Based Plastics
- 5.1.1.3 Polylactic Acid (PLA)
- 5.1.1.4 Polyhydroxyalkanoates (PHA)
- 5.1.1.5 Polybutylene Succinate (PBS)
- 5.1.1.6 Other Compostable Polymers
- 5.1.2 Paper
- 5.1.3 Molded Pulp Fiber
- 5.1.4 Plant-Based Composites (Mushroom, Seaweed, Bagasse)
- 5.1.1 Bioplastics
- 5.2 By Packaging Format
- 5.2.1 Rigid Packaging
- 5.2.1.1 Bottles and Jars
- 5.2.1.2 Trays and Clamshells
- 5.2.1.3 Boxes and Cartons
- 5.2.1.4 Other Rigid Packagings
- 5.2.2 Flexible Packaging
- 5.2.2.1 Films and Wraps
- 5.2.2.2 Pouches and Bags
- 5.2.2.3 Other Flexible Packagings
- 5.2.1 Rigid Packaging
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceuticals
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 E-Commerce and Retail
- 5.3.6 Other End-user Industries
- 5.4 By Distribution Channel
- 5.4.1 Direct Sales
- 5.4.2 Indirect Sales
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Nigeria
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Mondi Group
- 6.4.3 Smurfit WestRock
- 6.4.4 Tetra Pak International SA
- 6.4.5 Sealed Air Corporation
- 6.4.6 International Paper Company
- 6.4.7 Ranpak Holding Corporation
- 6.4.8 Huhtamaki Oyj
- 6.4.9 Stora Enso Oyj
- 6.4.10 NatureWorks LLC
- 6.4.11 BASF SE
- 6.4.12 Novamont SpA
- 6.4.13 Total Corbion PLA
- 6.4.14 Elevate Packaging Inc.
- 6.4.15 BioPak Pty Ltd (Duni Group)
- 6.4.16 Kruger Inc.
- 6.4.17 Greenpack Limited
- 6.4.18 Berkley International Packaging Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment