|
시장보고서
상품코드
2121658
포병용 탄약 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Artillery Ammunition - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
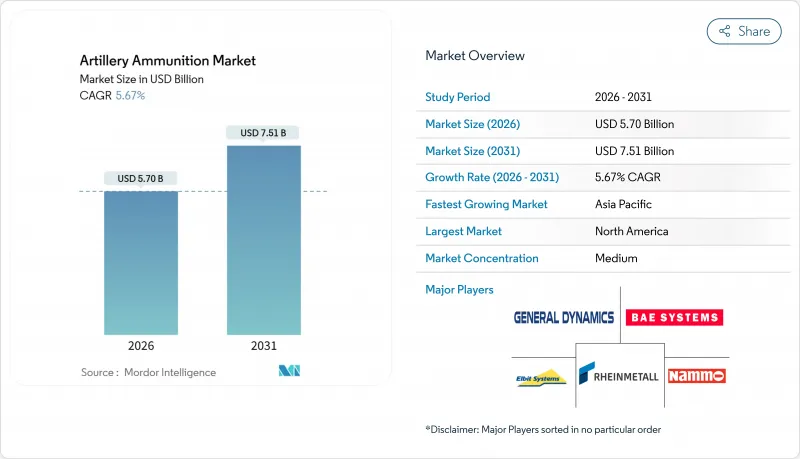
에 따르면 포병용 탄약 시장 규모는 2026년에 57억 달러에 달하고, 2031년까지 75억 1,000만 달러에 달할 것으로 예측되며, 예측 기간 동안 CAGR 5.67%로 확대될 전망입니다.
본 보고서는 탄두 유형(고폭탄, 발연·조명용 등), 유도 방식(비유도, GPS 유도 등), 추진/장약 유형(기존형 장약, 모듈식 포탄 장약 시스템 등), 플랫폼 유형(견인식 곡사포, 자주식 곡사포 등), 및 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 포병용 탄약 시장의 동향 및 인사이트
격화되는 강대국 간 경쟁과 높은 수준의 탄약 지출
2024년 중반까지 러시아의 생산량이월 25만 발에 달하고, NATO가 2025년 3월까지 우크라이나에 155mm 포탄 200만 발을 공급하겠다고 약속함에 따라 역사적인 비축량 부족이 드러났으며, 이것이 현재의 조달 우선순위를 결정짓고 있습니다. 미국만 해도 스크랜턴과 레이크시티 시설 확장에 30억 달러를 배정하여, 월간 생산량을 2023년 초의 2만 8,000발에서 2025년 말까지 10만 발이라는 목표로 끌어올리고 있습니다. 1억 1,700만 달러 규모의 ASAP 기금 등 EU의 자금 조달 수단은 회원국 내 신규 생산 라인 건설에 공동 출자하고 있으며, 한편 대만과 한국도 지역적 분쟁의 불씨에 대비하기 위해 예산을 증액하고 있습니다. 장기적인 다년 계약을 통해 평시 소비 패턴으로는 상업적으로 수익성을 확보할 수 없었던 자본 집약적인 추진제 및 신관(신관)에 대한 투자가 현재 뒷받침되고 있습니다. 따라서 포병용 탄약 시장은 적어도 하나의 완전한 계획 주기에 걸친 전례 없는 수요 확실성의 혜택을 누리고 있으며, 이는 현재 5년에 걸친 생산능력 확대 추세를 확고히 하고 있습니다.
장거리 정밀 사격 프로그램의 급증
2024년에 명칭이 변경된 미국의 ‘장사거리 포병(Extended Range Cannon Artillery)’계획에서는 XM1113 로켓 보조형 및 XM1155-SC 정밀탄을 통합하여 사거리 70킬로미터를 실현하고 있으며, 2027년에 초기 작전 능력(IOC) 달성이 예정되어 있습니다. BAE 시스템즈는 세미액티브 레이저 시커를 탑재한 ‘엑스칼리버 S’ 시리즈를 출하했으며, 한편 레오나르도사의 ‘불카노’ 시리즈는 NATO 인증 획득 후 국내에서 2억 3,500만 달러 규모의 수주를 확보했습니다. 제너럴 아토믹스사는 10만 달러 미만의 비용으로 사거리 150킬로미터를 실현하는 램젯 추진식 포탄의 실증에 성공하여, 전술 미사일이 가진 ‘표적당 비용’ 측면에서의 우위를 훼손하는 결과를 낳았습니다. 이러한 프로그램들은 전반적으로 ‘효과당 발사 탄수’를 줄이고, 가치의 중심을 금속 부품에서 유도 서브시스템으로 전환하는 동시에, GPS 차단 대책으로서의 하이브리드 유도 기술 연구 개발을 촉진하고 있습니다. 신관이나 시커의 생산을 자체 제작할 수 있는 공급업체는 더 높은 이익률을 확보할 수 있을 뿐만 아니라, 수출 규제의 영향도 경감됩니다.
신관 및 베이스 블리드 어셈블리에 대한 엄격한 ITAR/바세너 규제
카테고리 I 규제로 인해 라이선스 취득까지의 기간이 최대 18개월로 연장되어, 미국산 GPS 신관이 장착된 튀르키예 및 한국산 제품의 수출이 지연되고 있습니다. 로케잔사는 ITAR 규제 대상 부품을 회피하기 위해 HE-ERFB 포탄의 재설계를 진행하며 사거리를 희생했습니다. 한편, 바라트 일렉트로닉스는 포탄용 신관의 현지 생산을 위해 푸네에 8,500만 달러를 투자하고, NATO 준수 시험을 2027년까지 연장했습니다. 수출 규제를 둘러싼 마찰은 공급 기반을 분열시키고, 2차 제조사들이 성능은 떨어지지만 라이선스가 필요 없는 대체품을 채택하도록 유도함으로써, 우량 공급업체의 단위당 가치 상승을 제한하고 있습니다.
부문별 분석
고폭탄(HE)은 제압, 지역 봉쇄, 신속 대응 임무에 필수적이기 때문에 2025년 포병용 탄약 시장 점유율의 51.74%를 차지했습니다. 정밀 유도탄은 여전히 소수이지만, 전술의 전환으로 인해 ‘첫 발사 효과’와 탄약 절약이 중시됨에 따라 연평균 성장률(CAGR) 5.58%로 성장할 것으로 예측됩니다. 2024년부터 2026년까지 미 육군이 36,000발의 ‘엑스칼리버’ 탄약을 12억 달러에 구매한 것은, 표적 1개당 여러 발의 비유도탄을 대체하는 GPS 유도형 탄약으로의 예산 배분 전환을 여실히 보여줍니다. 발연탄, 조명탄, 연습탄은 계속해서 통합 병과 훈련 주기를 뒷받침하고 있지만, 집속탄 금지 협약(CCW)의 발효로 인해 DPICM의 판매는 감소하고 있습니다. 베이스블리드 탄약과 로켓 추진식 탄두는 인도 등 아시아태평양 사용자들로부터 주목을 받고 있으며, 인도는 2027년에 사거리 48킬로미터의 베이스블리드 탄약 양산을 승인했습니다.
정밀유도탄(PGM)은 내장 센서의 높은 부가가치로 인해 제조업체의 이익률을 높여주지만, 한편으로는 ITAR(국제무기거래규정)에 노출될 위험과 공급망의 복잡성도 증가시킵니다. 예산 제약이 있는 아프리카와 라틴아메리카 군은 여전히 고폭탄의 대량 발주를 선호하고 있으며, 이로 인해 기존 생산 라인이 스마트 탄약 조립 라인과 병행하여 계속 가동되고 있습니다. 이러한 양극화된 동향으로 인해 포병용 탄약 시장은 가격대 및 기술 면에서 다양성을 유지하며, 총 수요의 변동을 억제하고 있습니다.
비유도탄은 2025년 매출의 59.05%를 차지했으며, 이는 기존 장비와의 호환성과 발당 1,200달러 미만의 단가를 반영한 것입니다. GPS 유도탄은 레이시온사의 애리조나 생산 라인 확장 및 XM1155-SC 채택을 배경으로, 2031년까지 연평균 성장률(CAGR) 6.41%로 성장할 것으로 예상됩니다. 레이저 유도형은 이동 표적을 공격할 수 있지만, 시선(LOS)에 의한 조준이 필요하기 때문에 전자기 간섭이 심한 환경에서는 사용이 어렵습니다. 하이브리드형 GPS-INS 솔루션은 재밍의 영향을 완화하며, 그 유효성은 엘빗사가 유럽의 NATO 회원국들과 체결한 SIGMA 계약을 통해 입증되었습니다. 우크라이나에서의 전자전은 중복성의 필요성을 부각시키고 있으며, 비용 증가에도 불구하고 공급업체들은 멀티 모드 유도 방식의 채택을 추진하고 있습니다.
비유도 탄약은 특히 정밀 사격의 이점이 제한적인 연약한 표적을 대상으로 한 포화 사격이나 제압 사격에서 여전히 중요한 역할을 하고 있습니다. 그러나 STANAG 4425와 같은 상호운용성 관련 규정에 따라 저가대 구매자조차도 적어도 부분적으로는 GPS 지원 장비를 갖추도록 요구받고 있으며, 대량 구매가 계속되고 있음에도 불구하고 비유도 탄의 시장 점유율은 시간이 지남에 따라 꾸준히 축소될 것으로 확실시되고 있습니다.
지역별 분석
북미는 2025년 매출의 37.61%를 차지했습니다. 이는 주로 미국 국방부(DoD)가 2025년 말까지 155mm 포탄의 월간 생산량을 10만 발로 늘리겠다는 30억 달러 규모의 계획에 힘입은 결과입니다. 2024년 말까지 우크라이나에 200만 발 이상의 포탄이 제공됨에 따라, 즉각적인 분쟁 단계가 종료된 후에도 높은 생산률을 유지하기 위한 보충 주문이 발생하고 있습니다. 괌, 일본, 호주에 전진 배치된 미국 내 포병용 탄약 시장 규모는 태평양 지역 방위 계획이 성숙해짐에 따라 확대될 것으로 예상됩니다. 캐나다가 8억 5,000만 캐나다 달러(6억 2,183만 달러) 규모로 M777A2를 구매하는 계약에는 10년에 걸친 포탄 공급이 포함되어 있는 반면,멕시코의 예산에서는 M101 및 M114 장비를 운용 가능한 상태로 유지하고 있지만, 생산량은 정체된 상태입니다.
아시아태평양은 2027년까지 155mm 포탄 비축량을 24만 발로 두 배로 늘리겠다는 인도의 공약과, 2030년까지 이어지는 한국의 1조 2,000억 원(8억 3,650만 달러)규모의 탄약 계약 포트폴리오에 힘입어 연평균 성장률(CAGR) 5.17%로 성장할 것으로 예측됩니다. 일본의 16% 예산 증액은 19식 곡사포 탄약 조달에 충당되고 있으며, 중국의 노린코는 수출 수주에 대응하기 위해 6개의 전용 포탄·로켓 공장을 운영하고 있습니다. 이러한 수출 수주의 세부 내용은 불투명하지만, 아프리카와 라틴아메리카 전역에서 경쟁을 격화시키고 있습니다. 대만과 호주에서 억지력을 중시한 예산 편성은 장기적인 포탄 조달을 암묵적으로 확보하고 있으며, 정치적 동맹이 변화하는 상황에서도 지역 수요의 회복력을 높이고 있습니다.
유럽의 부활은 514억 4,000만 달러 규모의 SAFE 대출과 라인메탈사의 독일 연방군 대상 기본 계약에 힘입어, 2028년까지 생산량 면에서 북미와 어깨를 나란히 할 태세를 갖추고 있습니다. 폴란드의 파트너십 공장은 2027년까지 연간 15만 발의 포탄 생산을 목표로 하고 있으며, 독일의 20만 발 규모 MACS 발주는 지역 전체의 하청 산업을 활성화시키고 있습니다. 또한, 영국은 글래스코드사에 3억 파운드(4억 489만 달러)를 투자하여 152mm 포탄 생산 라인을 구축하고 있습니다. 프랑스, 스웨덴, 노르웨이는 각각 우크라이나에 대한 재보급을 조건으로 국가 자금을 출연하고 있으며, 이를 통해 예측 가능한 다년간의 수주 잔고를 확보하는 동시에 단일 시설에 대한 의존 위험을 줄이기 위해 생산능력을 분산시키고 있습니다. 러시아에서는 NATO 회원국의 구매층과의 중복을 최소화하는, 제한된 수출처를 대상으로 대규모 생산이 지속되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약 및 주요 조사 결과
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.07According to Mordor Intelligence, the artillery ammunition market size stood at USD 5.70 billion in 2026 and is projected to reach USD 7.51 billion by 2031, expanding at a 5.67% CAGR during the forecast period.
This report is Segmented by Shell Type (High-Explosive, Smoke and Illumination, and More), Guidance Mechanism (Unguided, GPS-Guided, and More), Propulsion/Charge Type (Legacy Charges, Modular Artillery Charge System, and More), Platform Type (Towed Howitzers, Self-Propelled Howitzers, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Artillery Ammunition Market Trends and Insights
Escalating Great-Power Competition and High-Tempo Munitions Expenditure
Russia's output reaching 250,000 shells per month by mid-2024 and NATO's pledge to deliver 2 million 155 mm rounds to Ukraine by March 2025 exposed historic stockpile gaps that now dictate procurement priorities. The US alone appropriated USD 3 billion to expand facilities in Scranton and Lake City, increasing monthly production from 28,000 rounds in early 2023 to a target of 100,000 rounds by late 2025. EU instruments such as the USD 117 million ASAP fund co-finance new lines in member states, while Taiwan and South Korea ramp up budgets to buffer against regional flashpoints. Long-term, multiyear contracts now underwrite capital-intensive propellant and fuze investments that would have been commercially unviable under peacetime consumption patterns. The artillery ammunition market, therefore, benefits from unprecedented demand certainty across at least one complete planning cycle, anchoring the current 5-year capacity-build trend.
Surge in Long-Range Precision-Fire Programs
The US Extended Range Cannon Artillery effort, re-branded in 2024, integrates XM1113 rocket-assisted and XM1155-SC precision rounds to reach 70 kilometers, with IOC slated for 2027. BAE Systems shipped Excalibur S lots featuring semi-active laser seekers, while Leonardo's Vulcano family secured USD 235 million in domestic orders after NATO qualification. General Atomics demonstrated a ramjet-assisted 150-kilometer shell costing under USD 100,000, eroding the cost-per-target advantage of tactical missiles. These programs collectively cut rounds-per-effect ratios, shifting value from metalwork to guidance subsystems and stimulating hybrid-guidance R&D against GPS denial. Suppliers able to internalize fuze and seeker production capture higher margins and face lower exposure to export controls.
Stringent ITAR/Wassenaar Controls on Fuzes and Base-Bleed Assemblies
Category I controls lengthen license cycles up to 18 months, delaying Turkish and South Korean exports that embed US-origin GPS fuzes. Roketsan redesigned its HE-ERFB projectile to circumvent ITAR parts, sacrificing range, while Bharat Electronics invested USD 85 million in Pune to localize artillery fuzes, extending NATO-compliance testing into 2027. Export-control frictions fragment the supply base and incentivize second-tier producers to field lower-performance but license-free alternatives, limiting unit-value upside for premium suppliers.
Other drivers and restraints analyzed in the detailed report include:
- Modernization of 155 mm Logistics Chains and Modular Charge Systems
- Rising Defense Budgets in Asia-Pacific and Eastern Europe
- Volatile Nitrocellulose and Copper Prices Pressuring Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
High-explosive (HE) rounds accounted for 51.74% of the artillery ammunition market share in 2025 as they remain indispensable for suppression, area denial, and quick-response missions. Precision-guided shells, though still a minority, are forecast to grow at a 5.58% CAGR as doctrinal shifts emphasize first-round effects and ammunition conservation. The United States Army's USD 1.2 billion purchase of 36,000 Excalibur rounds between 2024 and 2026 illustrates the budgetary swing toward GPS-guided options that replace multiple unguided rounds per target. Smoke, illumination, and practice rounds continue to support combined-arms training cycles, while DPICM sales shrink under the Convention on Cluster Munitions. Base-bleed and rocket-assisted projectiles are attracting Asia-Pacific users, such as India, which cleared its 48-kilometer base-bleed round for serial production in 2027.
Precision-guided munitions (PGMs) expand manufacturer margins due to the high value of embedded sensors, but they also intensify ITAR exposure and supply-chain complexity. Budget-constrained militaries in Africa and Latin America continue to favor high-explosive bulk orders, ensuring that legacy production lines run in parallel with smart-munition assembly. The dual-speed dynamic keeps the artillery ammunition market diversified across price points and technologies, reducing total demand volatility.
Unguided projectiles represented 59.05% of 2025 revenue, reflecting fleet compatibility and unit cost below USD 1,200 per shell. GPS-guided shells are expected to grow 6.41% CAGR through 2031 on the back of Raytheon's Arizona line expansion and XM1155-SC adoption. Laser-guided variants offer moving-target engagement but require line-of-sight (LOS) illumination, which complicates their use in contested electromagnetic environments. Hybrid GPS-INS solutions mitigate jamming, evidenced by Elbit's SIGMA contract with a European NATO member. Electronic warfare in Ukraine highlights the need for redundancy, prompting suppliers to adopt multi-mode guidance despite increased costs.
Unguided rounds keep relevance for saturation and suppression fire, particularly against soft targets where precision provides marginal benefit. Nevertheless, interoperability rules, such as STANAG 4425, push even value-tier buyers toward at least partially GPS-friendly inventories, ensuring a steady erosion of the unguided share over time, despite ongoing volume purchases.
Complete Report Scope:
- By Shell Type
- High-Explosive (HE)
- Smoke and Illumination
- Dual-Purpose Improved Conventional Munition (DPICM)
- Base-Bleed/Rocket-Assisted Projectile (RAP)
- Sensor-Fuzed/Cluster
- Precision-Guided
- Practice/Blank
- By Guidance Mechanism
- Unguided
- GPS-Guided
- Laser-Guided
- Inertial/Hybrid
- By Propulsion/Charge Type
- Legacy Charges
- Modular Artillery Charge System (MACS)
- Extended Range and Submunition Rounds
- By Platform Type
- Towed Howitzers
- Self-Propelled Howitzers
- Mortars (Greater than 81 mm)
- Rocket Artillery (MRL)
- Naval Guns
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 37.61% of 2025 revenue, primarily driven by the US Department of Defense's (DoD's) USD 3 billion initiative to increase monthly 155 mm output to 100,000 by late 2025. Transfers exceeding 2 million shells to Ukraine by the end of 2024 create backfill orders that sustain high output rates even after the immediate conflict phase. The artillery ammunition market size within the US pre-positioned stocks in Guam, Japan, and Australia is expected to grow as Pacific defense planning matures. Canada's CAD 850 million (USD 621.83 million) M777A2 buy embeds a decade-long ammunition stream, whereas Mexico's budget keeps its M101 and M114 fleets operational but static.
Asia-Pacific is forecasted to grow at a 5.17% CAGR, buoyed by India's commitment to double 155 mm shell capacity to 240,000 rounds by 2027 and South Korea's KRW 1.2 trillion (USD 836.50 million) ammunition contract portfolio extending to 2030. Japan's 16% budget increase funds Type 19 howitzer ammunition, and China's Norinco operates six dedicated artillery-rocket plants that feed export orders, which, although opaque, intensify competition across Africa and Latin America. Deterrence-driven budgets in Taiwan and Australia implicitly lock in long-term shell requisitions, adding resilience to regional demand even under shifting political coalitions.
Europe's resurgence is underpinned by the USD 51.44 billion SAFE loan and Rheinmetall's Bundeswehr framework, positioning the bloc to rival North America in volume output by 2028. Poland's partnership plant aims for 150,000 shells annually by 2027, Germany's 200,000-round MACS order stimulates subcontracting across the region, and the UK invests GBP 300 million (USD 404.89 million) in Glascoed for 152 mm lines. France, Sweden, and Norway each tie national funding to Ukrainian resupply, creating predictable multi-year order books while distributing capacity to mitigate the risk of single-facility reliance. Russian production continues at scale, targeting a narrow export club that limits overlap with NATO buyer pools.
- Rheinmetall AG
- General Dynamics Corporation
- BAE Systems plc
- Nammo AS
- Elbit Systems Ltd.
- KNDS N.V.
- Saab AB
- Thales Group
- MESKO S.A.
- Hanwha Corporation
- Northrop Grumman Corporation
- Poongsan Corporation
- Singapore Technologies Engineering Ltd.
- JUNGHANS Microtec GmbH
- Kaman Corporation
- L3Harris Technologies, Inc.
- Directorate of Ordnance (Coordination & Services)
- Leonardo S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY AND KEY FINDINGS
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating great-power competition and high-tempo munitions expenditure
- 4.2.2 Surge in long-range precision-fire programs
- 4.2.3 Modernization of 155 mm logistics chains and modular charge systems
- 4.2.4 Rising defense budgets in Asia-Pacific and Eastern Europe
- 4.2.5 NATO qualification of insensitive-munitions propellants unlocking new suppliers
- 4.2.6 Additive-manufactured driving bands lowering barrel wear and shell cost
- 4.3 Market Restraints
- 4.3.1 Stringent ITAR/Wassenaar controls on fuzes and base-bleed assemblies
- 4.3.2 Volatile nitrocellulose and copper prices pressuring margins
- 4.3.3 Chronic shortage of triple-base propellant mixing capacity (M31)
- 4.3.4 Fire-safety insurance premiums for ageing ECM magazines
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Shell Type
- 5.1.1 High-Explosive (HE)
- 5.1.2 Smoke and Illumination
- 5.1.3 Dual-Purpose Improved Conventional Munition (DPICM)
- 5.1.4 Base-Bleed/Rocket-Assisted Projectile (RAP)
- 5.1.5 Sensor-Fuzed/Cluster
- 5.1.6 Precision-Guided
- 5.1.7 Practice/Blank
- 5.2 By Guidance Mechanism
- 5.2.1 Unguided
- 5.2.2 GPS-Guided
- 5.2.3 Laser-Guided
- 5.2.4 Inertial/Hybrid
- 5.3 By Propulsion/Charge Type
- 5.3.1 Legacy Charges
- 5.3.2 Modular Artillery Charge System (MACS)
- 5.3.3 Extended Range and Submunition Rounds
- 5.4 By Platform Type
- 5.4.1 Towed Howitzers
- 5.4.2 Self-Propelled Howitzers
- 5.4.3 Mortars (Greater than 81 mm)
- 5.4.4 Rocket Artillery (MRL)
- 5.4.5 Naval Guns
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 France
- 5.5.2.3 Germany
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Rheinmetall AG
- 6.4.2 General Dynamics Corporation
- 6.4.3 BAE Systems plc
- 6.4.4 Nammo AS
- 6.4.5 Elbit Systems Ltd.
- 6.4.6 KNDS N.V.
- 6.4.7 Saab AB
- 6.4.8 Thales Group
- 6.4.9 MESKO S.A.
- 6.4.10 Hanwha Corporation
- 6.4.11 Northrop Grumman Corporation
- 6.4.12 Poongsan Corporation
- 6.4.13 Singapore Technologies Engineering Ltd.
- 6.4.14 JUNGHANS Microtec GmbH
- 6.4.15 Kaman Corporation
- 6.4.16 L3Harris Technologies, Inc.
- 6.4.17 Directorate of Ordnance (Coordination & Services)
- 6.4.18 Leonardo S.p.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment