

|
시장보고서
상품코드
2121659
나노 사물인터넷(IoNT) : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Internet Of Nano Things - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
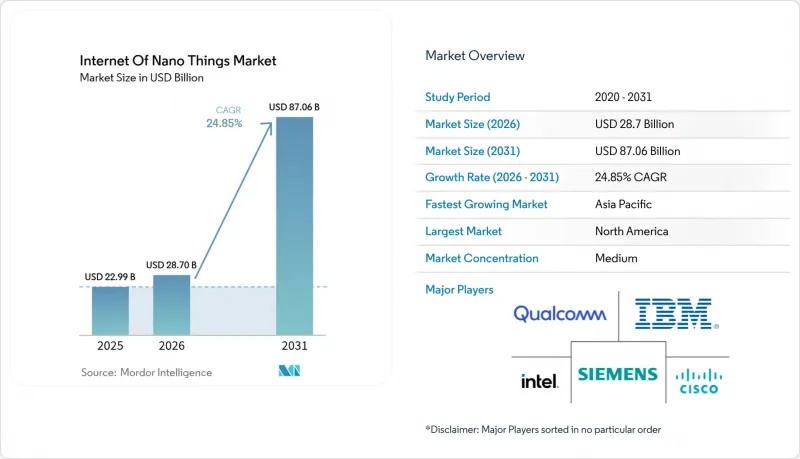
에 따르면 나노 사물인터넷(IoNT) 시장 규모는 2026년에 287억 달러로 추정되며, 2025년 229억 9,000만 달러에서 확대되어 2031년에는 870억 6,000만 달러에 달할 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 24.85%가 될 전망입니다.
본 보고서는 구성요소(하드웨어, 소프트웨어, 서비스), 최종사용자(의료, 물류·운송, 국방·항공우주, 제조, 기타), 통신 기술(전자기 통신, 분자 통신, 나노 RFID/NFC, 기타), 전개 모델(온프레미스, 클라우드, 하이브리드) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 나노 사물인터넷(IoNT) 시장의 동향 및 인사이트
나노기술의 급속한 발전으로 초저전력 센서의 구현이 가능해졌습니다
현재, 탄소나노튜브 기반 장치는 주변 에너지를 회수할 수 있게 되어, 기존 배터리에 의한 제약을 해소하고 유지보수 주기를 대폭 단축하고 있습니다. MIT의 엔지니어들은 광합성을 통해 자가 발전하는 식물 구동형 나노 센서의 실증에 성공하여, 원격지 배포 시 에너지 자급자족이 가능함을 입증했습니다. 질화붕소 나노튜브 섬유는 가혹한 산업 환경에서도 열화되지 않고 견딜 수 있는 내열성 네트워크를 제공합니다. Materials Nexus의 희토류 무함유 영구자석의 획기적인 개발을 대표로 하는, AI를 활용한 소재 발견과의 시너지 효과로 인해 혁신 주기는 수년 단위에서 수개월 단위로 단축되었습니다. 이러한 진전은 정밀 농업에서 위험 환경 모니터링에 이르기까지 폭넓은 응용을 가능하게 하여, 나노 사물인터넷(IoNT) 시장의 장기적인 성장을 뒷받침하고 있습니다.
실시간 건강 모니터링용 웨어러블 기기에 대한 수요 증가
Nanowear사의 나노센서가 탑재된 심장 패치가 FDA 승인을 획득한 것은, 나노기술을 활용한 의료기기에 대한 규제적 타당성이 인정되었음을 보여줍니다. 탄소나노튜브 필름을 기반으로 한 연속 혈당 모니터는 눈에 띄지 않는 피부 패치 형태를 유지하면서도, 현재는 검사실 수준의 정확도를 실현하고 있습니다. 여러 분석 항목을 지원하는 이 패치는 전해질, 젖산, 코르티솔을 동시에 추적하여 만성 질환의 의료비를 절감하는 예방 의료 모델을 뒷받침하고 있습니다. 이러한 기기를 도입한 병원에서는 패혈증의 조기 발견 및 중환자실(ICU) 입원 기간 단축 사례가 보고되고 있어, 의료 분야가 나노 사물인터넷(IoNT) 시장의 확대에 크게 기여하고 있음을 뒷받침하고 있습니다. 2024년에 이 분야가 매출 점유율의 30.3%를 차지할 것이라는 점은, 다른 수직 시장이 과제로 삼아야 할 만큼 확고한 수요가 존재함을 보여줍니다.
나노스케일에서의 심각한 데이터 보안 및 개인정보 보호 위험
나노 센서는 기존의 암호화에 필요한 연산 능력이 부족하여, 병원, 공장 또는 지자체의 네트워크를 위험에 빠뜨릴 수 있는 공격 표면을 노출시키고 있습니다. 특히, 체내에 이식되는 의료용 나노 센서는 취약성이 높아, 혈당 모니터가 해킹당하면 측정값이 조작되어 환자의 안전이 위협받을 가능성이 있습니다. GDPR(일반 데이터 보호 규정)은 나노 센서 데이터를 고위험으로 간주하며, 자율형 서브밀리미터급 장치에서는 구현이 어려운 명시적 동의를 의무화하고 있습니다. 양자 내성을 갖춘 경량 암호화는 여전히 개념 증명(PoC) 단계에 머물러 있어 보안 격차를 확대하고, 나노 사물인터넷(IoNT) 시장의 예상 연평균 성장률(CAGR)을 4.3% 끌어내리는 요인이 되고 있습니다.
부문 분석
하드웨어는 2025년 매출의 46.90%를 차지하며, 나노 사물인터넷(IoNT) 시장을 필수적인 물리적 디바이스, 안테나, 게이트웨이로 뒷받침하고 있습니다. 그러나 분석 플랫폼이 방대한 분자 데이터를 활용함에 따라 소프트웨어 부문은 28.12%의 CAGR로 빠르게 성장하고 있습니다. 서비스 분야는 아직 발전 단계에 있지만, 기업들이 나노 디바이스를 레거시 시스템에 통합하기 위해 컨설팅 전문 지식을 필요로함에 따라 두 자릿수 성장을 기록하고 있습니다. 다우(Dow)사가 카바이스(Carbis)사와 열 인터페이스 소재에 대해 제휴한 사례는 전문적인 노하우가 어떻게 고수익 서비스 라인으로 전환되고 있는지를 보여줍니다.
소프트웨어의 급속한 성장은 가치 창출의 방식을 재정의하고 있습니다. 상품화가 진행됨에 따라 하드웨어의 이익률은 압박받는 반면, 수십억 개의 엔드포인트를 관리하는 오케스트레이션 스택은 고액의 라이선스 비용을 부과하고 있습니다. 클라우드 벤더들은 나노 디바이스의 API를 통합하고, 보안, AI, 라이프사이클 관리를 통합한 플랫폼으로 개발자들을 끌어들이고 있습니다. 예측 기간 동안 소프트웨어 수익과 연동되는 나노 사물인터넷(IoNT) 시장의 규모는 하드웨어와의 격차를 좁힐 것으로 예상되며, 이는 생태계 전체의 경쟁 전략이 재구축될 것임을 의미합니다.
의료 분야는 2025년 매출의 29.90%를 차지하며, 지속적인 생체 신호 모니터링, 임플란트 감시, 스마트 약물 투여에 나노 센서를 활용하고 있어 여전히 가장 큰 도입 분야로 남아 있습니다. 한편, 스마트 시티 사업은 지자체들이 대기질 분석, 누수 감지, 지능형 교통 관리를 위해 나노 센서 메시를 도입함에 따라 2031년까지 연평균 성장률(CAGR) 27.05%로 확대될 전망입니다. 제조업에서는 생산 라인에 통합된 나노 센서가 실시간 분자 데이터를 예측 유지보수 엔진에 제공하며, 물류 기업은 컨테이너 내에 나노 센서를 설치하여 콜드체인 준수 여부를 확인하고 있습니다.
환경 보호 기관은 기존 센서에는 없는 ‘10억 분의 1(ppb)’의 정밀도로 오염 물질을 감지하는 나노 센서 부이를 채택하고 있습니다. 농업 관련 기업들은 영양 결핍을 조기에 알려주는 식물 조직용 나노 센서를 살포하여 비료 사용량과 물 낭비를 줄이고 있습니다. 이러한 도입 사례는 수직적 다각화가 실물 경제 전반에 걸친 나노 사물인터넷(IoNT) 시장의 확산을 얼마나 가속화하고 있는지를 보여줍니다.
지역별 분석
북미는 2025년에도 연방 정부의 보조금, 테라헤르츠 대역의 조기 할당, 그리고 나노급 생산이 가능한 확립된 반도체 제조 공장의 지원에 힘입어 매출 점유율 38.10%를 유지했습니다. NIST(미국 국립표준기술연구소)의 IoT 자문위원회는 표준에 관한 명확한 지침을 제공하여 상용 시범 사업의 가속화에 기여하고 있습니다. 그러나 높은 인건비와 자본 지출이 이익률을 압박하고 있으며, 나노 제조 기술자를 공급할 인재 파이프라인 확보에 어려움을 겪고 있습니다. 미국은 국방, 항공우주 및 첨단 의료용 임플란트에 주력하는 반면, 캐나다는 천연자원 관리를 위한 환경 모니터링에 자원을 투입하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 27.62%를 기록할 전망입니다. 이는 인더스트리 4.0에 대한 적극적인 지원책, 견고한 전자제품 공급망, 그리고 광범위한 5G 보급을 반영한 것입니다. 중국은 제조 분야의 도입을 주도하고 있으며, 팹(fab) 및 화학 플랜트 내에 나노 센서를 통합하여 수율과 안전성을 향상시키고 있습니다. 한편, 일본의 의료 기술 기업들은 생체적합성이 있는 나노 임플란트 개발을 선도하고 있습니다. 한국은 통신 분야의 리더십을 활용하여 6G 대응 나노 메시 네트워크의 시범 운영을 추진하고 있습니다. 각 지역 정부는 나노기술 연구 개발에 보조금을 지원하여 시장 출시 기간을 단축하는 동시에 경쟁을 심화시키고 있습니다. 그 결과 발생하는 규모의 경제로 인해, 향후 10년이 끝날 무렵에는 아시아태평양과 북미 간의 나노 사물인터넷(IoNT) 시장 규모 격차가 줄어들 것으로 전망됩니다.
유럽은 여전히 영향력을 유지하고 있으며, 세계적 기준을 형성하는 데이터 개인정보 보호 및 지속가능성 프레임워크를 주도하고 있습니다. ‘호라이즌 유럽(Horizon Europe)’은 엣지 AI 및 IoT 연구에 1억 유로를 배정하고 있으며, 그 일부는 나노 디바이스의 상호운용성에 할당되고 있습니다. 독일은 정밀 제조에 나노 센서를 도입하고 있으며, 영국은 그래핀 기반 헬스 패치를 시험하고 있습니다. 남미, 중동 및 아프리카와 같은 신흥 지역에서는 수명주기 비용을 절감하면서도 고해상도 데이터를 제공할 수 있는 나노 센서의 장점을 활용해 환경 및 인프라 모니터링에 선택적으로 투자하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 투자 분석
제8장 시장 기회와 향후 동향
KSM 26.09.07According to Mordor Intelligence, the internet of Nano Things Market size in 2026 is estimated at USD 28.7 billion, growing from 2025 value of USD 22.99 billion with 2031 projections showing USD 87.06 billion, growing at 24.85% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, and Services), End-User (Healthcare, Logistics and Transportation, Defense and Aerospace, Manufacturing, and More), Communication Technology (Electromagnetic, Molecular Communication, Nano RFID/NFC, and More), Deployment Model (On-Premise, Cloud, and Hybrid), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Internet Of Nano Things Market Trends and Insights
Rapid Advancements in Nanotechnology Enabling Ultra-Low Power Sensors
Carbon-nanotube-based devices now harvest ambient energy, removing conventional battery constraints and slashing maintenance cycles. MIT engineers demonstrated plant-powered nanosensors that self-energize through photosynthesis, validating energy autonomy for remote deployments. Boron nitride nanotube fibres provide heat-tolerant networks that withstand harsh industrial settings without degradation. Coupled with AI-accelerated materials discovery, exemplified by Materials Nexus' rare-earth-free permanent magnet breakthrough, innovation cycles have shrunk from years to months. These advances unlock applications ranging from precision agriculture to hazardous-environment monitoring, underpinning the long-term growth of the Internet of Nano Things market.
Growing Demand for Real-Time Health Monitoring Wearables
FDA clearance of Nanowear's nanosensor cardiac patch underscores regulatory validation for nano-enabled medical devices. Continuous glucose monitors built on carbon-nanotube films now rival laboratory accuracy while retaining discreet, skin-patch form factors. Multi-analyte patches track electrolytes, lactate, and cortisol simultaneously, supporting preventive care models that lower chronic-disease costs. Hospitals integrating these devices report earlier sepsis detection and shorter ICU stays, reinforcing healthcare's contribution to the Internet of Nano Things market expansion. The sector's 30.3% revenue share in 2024 signals entrenched demand that other verticals must challenge.
Severe Data Security and Privacy Risks at Nanoscale
Nanosensors lack the compute headroom for traditional encryption, exposing attack surfaces that could compromise hospital, factory, or municipal networks. Implantable medical nanosensors are especially vulnerable; a hijacked glucose monitor can falsify readings, endangering patients. GDPR treats nanosensor data as high-risk, mandating explicit consent that is difficult to implement on autonomous sub-millimetre devices. Quantum-resistant lightweight ciphers remain at proof-of-concept stages, widening the security gap and exerting a negative 4.3% pull on forecast CAGR for the Internet of Nano Things market.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Adoption of Industry 4.0 and Smart Manufacturing
- Proliferation of 5G/6G and Edge Computing Infrastructure
- High Capital Costs and Complexity of Nano-Fabrication
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware generated 46.90% of 2025 revenue, anchoring the Internet of Nano Things market in essential physical devices, antennas, and gateways. Yet the software segment is racing ahead at a 28.12% CAGR as analytics platforms capitalise on torrents of molecular data. Services remain nascent but record double-digit growth because enterprises require consulting expertise to integrate nano-devices with legacy systems. Dow's collaboration with Carbice on thermal interface materials shows how specialised know-how is turning into high-margin service lines.
The software boom is redefining value capture: hardware margins compress as commoditisation sets in, while orchestration stacks that manage billions of endpoints command premium licences. Cloud vendors embed nano-device APIs, drawing developers into unified platforms that bundle security, AI, and lifecycle management. Over the forecast horizon, the Internet of Nano Things market size linked to software revenues is projected to narrow the gap on hardware, recalibrating competitive strategies across the ecosystem.
Healthcare contributed 29.90% of 2025 revenue and remains the largest adopter, leveraging nanosensors for continuous vitals monitoring, implant surveillance, and smart drug delivery. Smart-city programmes, however, will expand at 27.05% CAGR to 2031 as municipalities deploy nanosensor meshes for air-quality analytics, water-leak detection, and intelligent traffic control. In manufacturing, nanosensors embedded on production lines feed real-time molecular data into predictive-maintenance engines, while logistics firms fit nanosensors inside containers to verify cold-chain compliance.
Environmental agencies adopt nanosensor buoys that detect pollutants at parts-per-billion resolution, a capability classical sensors lack. Agriculture outfits scatter plant-tissue nanosensors that signal nutrient deficits early, cutting fertiliser usage and water waste. These deployments illustrate how vertical diversification is accelerating overall Internet of Nano Things market penetration across the real economy.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By End-user
- Healthcare
- Logistics and Transportation
- Defense and Aerospace
- Manufacturing
- Energy and Power
- Environmental Monitoring
- Retail
- Agriculture
- Smart Cities and Infrastructure
- Other End-users
- By Communication Technology
- Electromagnetic
- Molecular Communication
- Nano RFID/NFC
- Nano Sensor Networks
- Nano Satellite Communication
- Others
- By Deployment Model
- On-Premise
- Cloud
- Hybrid
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Singapore
- Malaysia
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 38.10% revenue share in 2025, buoyed by federal grants, early terahertz spectrum allocation, and entrenched semiconductor fabs capable of nano-class production. The NIST IoT Advisory Board provides clarity around standards, accelerating commercial pilots. However, high labour costs and capital outlays squeeze margins, and the talent pipeline struggles to supply nano-manufacturing technicians. The United States focuses on defence, aerospace, and advanced healthcare implants, while Canada channels resources into environmental monitoring for natural-resource stewardship.
Asia-Pacific will post a 27.62% CAGR to 2031, reflecting aggressive Industry 4.0 incentives, deep electronics supply chains, and expansive 5G footprints. China drives manufacturing uptake, embedding nanosensors inside fabs and chemical plants to boost yield and safety, while Japan's med-tech firms pioneer bio-compatible nano implants. South Korea exploits telecom leadership to pilot 6G-ready nano-mesh networks. Regional governments subsidise nano R&D, compressing time-to-market and intensifying competition. The resulting scale advantages will narrow the Internet of Nano Things market size gap between Asia-Pacific and North America by decade end.
Europe remains influential, championing data privacy and sustainability frameworks that shape global norms. Horizon Europe has earmarked EUR 100 million for edge-AI and IoT research, with part allocated to nano-device interoperability. Germany deploys nanosensors in precision manufacturing, and the United Kingdom tests graphene-based health patches. Emerging regions in South America and the Middle East, and Africa invest selectively in environmental and infrastructure monitoring, capitalising on nanosensors' ability to deliver high granularity at lower lifecycle costs.
- IBM Corporation
- Intel Corporation
- Cisco Systems, Inc.
- Qualcomm Technologies, Inc.
- Siemens AG
- Schneider Electric SE
- SAP SE
- Juniper Networks, Inc.
- Nokia Corporation
- Honeywell International Inc.
- Analog Devices, Inc.
- STMicroelectronics N.V.
- Nanoscale Components, Inc.
- NanoSensors, Inc.
- Agilent Technologies, Inc.
- TeraSense Group, Inc.
- Graphenea, Inc.
- Litmus Automation, Inc.
- ON Semiconductor Corporation
- Microchip Technology Inc.
- Camtek Ltd.
- NeuraLace Medical, Inc.
- Nanolike SAS
- Ambiq Micro, Inc.
- Synapse Wireless, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumption and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid advancements in nanotechnology enabling ultra-low power sensors
- 4.2.2 Growing demand for real-time health monitoring wearables
- 4.2.3 Increasing adoption of Industry 4.0 and smart manufacturing
- 4.2.4 Proliferation of 5G/6G and edge computing infrastructure
- 4.2.5 Emerging terahertz-band nano-antenna breakthroughs reducing signal attenuation
- 4.2.6 Government-funded pandemic surveillance networks leveraging nanosensors
- 4.3 Market Restraints
- 4.3.1 Severe data security and privacy risks at nanoscale
- 4.3.2 High capital costs and complexity of nano-fabrication
- 4.3.3 Biocompatibility and long-term cytotoxicity concerns in human body deployments
- 4.3.4 Lack of standardized terahertz spectrum regulations causing deployment delays
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By End-user
- 5.2.1 Healthcare
- 5.2.2 Logistics and Transportation
- 5.2.3 Defense and Aerospace
- 5.2.4 Manufacturing
- 5.2.5 Energy and Power
- 5.2.6 Environmental Monitoring
- 5.2.7 Retail
- 5.2.8 Agriculture
- 5.2.9 Smart Cities and Infrastructure
- 5.2.10 Other End-users
- 5.3 By Communication Technology
- 5.3.1 Electromagnetic
- 5.3.2 Molecular Communication
- 5.3.3 Nano RFID/NFC
- 5.3.4 Nano Sensor Networks
- 5.3.5 Nano Satellite Communication
- 5.3.6 Others
- 5.4 By Deployment Model
- 5.4.1 On-Premise
- 5.4.2 Cloud
- 5.4.3 Hybrid
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Singapore
- 5.5.4.6 Malaysia
- 5.5.4.7 Australia
- 5.5.4.8 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 IBM Corporation
- 6.4.2 Intel Corporation
- 6.4.3 Cisco Systems, Inc.
- 6.4.4 Qualcomm Technologies, Inc.
- 6.4.5 Siemens AG
- 6.4.6 Schneider Electric SE
- 6.4.7 SAP SE
- 6.4.8 Juniper Networks, Inc.
- 6.4.9 Nokia Corporation
- 6.4.10 Honeywell International Inc.
- 6.4.11 Analog Devices, Inc.
- 6.4.12 STMicroelectronics N.V.
- 6.4.13 Nanoscale Components, Inc.
- 6.4.14 NanoSensors, Inc.
- 6.4.15 Agilent Technologies, Inc.
- 6.4.16 TeraSense Group, Inc.
- 6.4.17 Graphenea, Inc.
- 6.4.18 Litmus Automation, Inc.
- 6.4.19 ON Semiconductor Corporation
- 6.4.20 Microchip Technology Inc.
- 6.4.21 Camtek Ltd.
- 6.4.22 NeuraLace Medical, Inc.
- 6.4.23 Nanolike SAS
- 6.4.24 Ambiq Micro, Inc.
- 6.4.25 Synapse Wireless, Inc.
7 INVESTMENT ANALYSIS
8 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 8.1 White-Space and Unmet-Need Assessment


