|
시장보고서
상품코드
2121706
인슐린 주입 펌프 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Insulin Infusion Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인슐린 주입 펌프 시장 규모는 2025년에 40억 8,000만 달러로 평가되었고, 2026년 43억 달러에서 2031년까지 55억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.38%를 기록할 전망입니다.
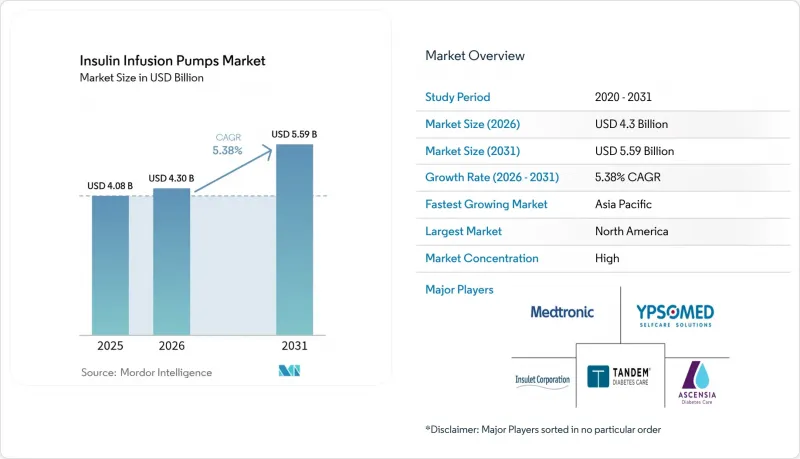
본 보고서에서는 업계를 구성 부품별(인슐린 펌프 본체, 주입 세트, 저장통), 펌프 유형별(유선식 펌프, 패치형 펌프, 이식형 펌프), 환자 유형별(1형 당뇨병, 2형 당뇨병),최종 사용자별(병원 및 진료소 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류하고 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 인슐린 주입 펌프 시장 동향 및 인사이트
폐쇄 루프형 ‘인공 췌장’ 시스템의 급속한 보급
2025년 4월 메드트로닉사의 ‘MiniMed 780G’가 FDA 승인을 받은 것은 자동 식사 감지 기능과 5분 단위의 인슐린 조절 기능의 가치를 부각시켰으며, 대규모 사용자 집단에서 목표 범위 내 유지율을 70% 이상으로 끌어올렸습니다. 탠덤사의 ‘Control-IQ’ 플랫폼도 동등한 이점을 보여주고 있으며, 알고리즘의 정확도와 센서의 신뢰성이 평가받는 기술 경쟁이 본격화되고 있습니다. 인공지능(AI)을 통해 생리적인 인슐린 분비 패턴을 모방한 투여량의 개인화가 가능해졌으며, 클로즈드 루프 플랫폼은 미래의 표준 치료법으로 자리매김하고 있습니다. 임상적 증거가 축적됨에 따라 보험사 측의 신뢰도가 높아지고, 적용 기준도 확대되고 있습니다. 마케팅 측면에서 기기의 작동 원리보다는 생활 방식의 편의성이 강조됨에 따라 환자의 수용도가 높아지고 있으며, 이는 판매 대수 증가와 소모품의 지속적인 매출을 견인하고 있습니다.
청소년층의 1형 당뇨병 유병률 상승
미국 내 소아 유병률은 현재 1,000명당 3.5명을 초과하고 있으며, 유럽 및 아시아 일부 지역에서도 유사한 증가 추세가 관찰됩니다. 소아과학회는 혈당 조절의 우수성과 야간 저혈당 감소 등을 이유로 펌프 요법을 1차 선택 치료법으로 권장하고 있습니다. FDA가 2세 이상을 대상으로 한 자동 인슐린 투여 장치를 승인함에 따라, 소아 잠재 대상자층이 확대되고 있습니다. 지역별 등록 데이터를 보면 도입 상황에 격차가 나타나며, 임상 지원이 미치지 못하는 지역에서 충족되지 않은 수요가 존재함을 시사하고 있습니다. 이에 대응하여 각 제조업체는 더 소형화된 저장통, 간소화된 사용자 인터페이스, 그리고 어린 사용자와 간병인의 공감을 얻을 수 있는 다채로운 색상의 패치용 접착제 등을 출시하며 대응하고 있습니다.
연결형 기기의 사이버 보안 위험
2024년, FDA는 특정 무선 펌프에 무단 접근이나 의도파관 않은 인슐린 투여를 가능하게 하는 취약점이 있다고 지적하여, 여러 건의 클래스 I 리콜이 실시되었습니다. 그 후, 학술적 분석을 통해 보안 조치가 적용되지 않은 블루투스 채널을 통한 잠재적인 악용 경로가 입증되었으며, 종단 간암호화 및 변조 방지 기능을 갖춘 펌웨어의 필요성이 강조되고 있습니다. FDA의 새로운 시판 전 지침에서는 위협 완화 계획과 시판 후 모니터링이 의무화되어, 이로 인해 개발 비용이 증가하고 승인까지의 기간이 길어지고 있습니다. 현재 병원 측은 조달에 앞서 공급업체에 상세한 사이버 보안 인증서 제출을 요구하고 있습니다. 공개적으로 보고된 환자에 대한 중대한 피해 사례는 없지만, 위험 회피 성향이 강한 지불 기관들 사이에서는 뿌리 깊은 위험 인식이 도입 지연으로 이어질 가능성이 있습니다.
부문 분석
인슐린 펌프 기기는 2025년 매출의 65.12%를 차지하고 있으며, 높은 가격대와 내장 소프트웨어의 복잡성이 두드러집니다. 한편, 하이브리드형 폐쇄 루프 알고리즘으로 인해 인슐린의 미량 볼러스 투여가 더욱 빈번해짐에 따라, 소모품인 리저버 시장은 연평균 성장률(CAGR) 7.62%로 더욱 빠르게 확대되었습니다. 막힘이나 기포를 감지하기 위한 스마트 센서를 리저버 내에 내장함으로써 환자의 안전성이 향상되었고, 공급업체에게는 교차 판매의 기회가 생겨났습니다. 메드트로닉이 자사의 펌프와 애보트의 혈당 센서를 결합한 것과 같은 전략적 제휴는 조달에 영향을 미치는 생태계 접근 방식의 한 예입니다.
소모품의 동향은 지속적인 수익 전망도 강화하고 있습니다. 각 제조업체는 7일간의 사용을 상정한 장기 착용형 주입 세트를 도입하고 있으며, 이를 통해 삽입 시의 부담을 줄이고 브랜드 충성도를 높이고 있습니다. 현재 경쟁사와의 차별화는 원활한 카트리지 장전, 인슐린 잔류량 감소, 그리고 감염 위험을 억제하는 항균 코팅에 달려 있습니다. 이러한 점진적인 혁신 덕분에 성숙한 시장에서 기기 교체 주기가 길어지더라도 판매량 전망은 안정적입니다.
패치형 펌프는 2025년에 52.05%의 시장 점유율을 차지하고 연평균 성장률(CAGR) 8.28%를 나타낼 것으로 전망되며, 이는 튜브가 없고 눈에 띄지 않는 웨어러블 기기에 대한 환자들의 선호도를 뒷받침합니다. 세련된 산업 디자인, 방수 하우징 및 자동 캐뉼라 삽입 기능 덕분에 사용자의 편의성이 향상되고 사회적 편견이 최소화되고 있습니다. 유선식 펌프는 감소 추세를 보이고 있지만, 대용량 저장소가 필요한 고용량 사용자나 두 유형의 호르몬을 병용하는 임상시험 프로토콜을 수행하는 사용자에게는 여전히 사용되고 있습니다. 이식형 시스템은 외과적 장벽이 존재하기 때문에 여전히 실험 단계에 머물러 있습니다.
패치 분야의 경쟁은 치열해지고 있으며, Tandem사의 ‘Mobi’가 더 얇은 디자인과 스마트폰 전용 인터페이스를 무기로 Insulet사의 기존 제품에 도전하고 있습니다. 신규 진출기업들은 아시아태평양을 대상으로 저비용 패치 대체품으로 포지셔닝하며, 간소화된 기능 세트와 구독형 가격을 결합한 서비스를 제공합니다. 무선 펌웨어 업그레이드를 통해 물리적 교체가 필요 없이 기능이 강화되어 사용자 유지율이 높아지고 있습니다.
지역별 분석
2025년에도 북미는 36.95%의 점유율을 차지하며 여전히 최대 시장으로 자리매김했습니다. 이는 광범위한 보험 적용 범위, 정교한 공급망, 그리고 제1형 및 2형 당뇨병 환자 모두로부터의 조기 수요가 뒷받침하고 있습니다. 이 지역의 성숙한 인프라는 폐쇄형 루프 시스템의 업그레이드와 상호 운용 가능한 구성 요소 생태계의 신속한 도입을 뒷받침하고 있지만, 현재 판매량 증가는 신규 사용자 수보다 교체 주기에 더 크게 좌우되는 경향을 보이고 있습니다. 또한, 사이버 보안에 관한 규제도 이 지역에서 시작되어 전 세계 설계 기준에 영향을 미치고 있습니다.
유럽에서는 국민건강보험 제도와 치료 성과를 벤치마킹하는 견고한 임상 등록 제도 덕분에 안정적인 판매량이 유지되고 있습니다. 보상 체계는 다양하지만, 일반적으로 입원 비용 절감 효과가 입증된 기술이 우선적으로 채택됩니다. 통합형 펌프 및 지속 혈당 모니터에 대한 신속한 CE 마크 취득 절차가 경쟁의 다양성을 촉진하고 있습니다. 중동 및 아프리카에서는 보급률이 낮은 편이지만, 사우디아라비아와 아랍에미리트(UAE)의 투자 이니셔티브에 힘입어 공공 당뇨병 센터에 패치형 펌프를 도입하는 시범 프로그램이 시작되었습니다. 아시아태평양은 당뇨병 유병률 상승, 도시화, 그리고 중산층 보험 가입자층의 확대로 인해 2031년까지 연평균 성장률(CAGR) 6.72%로 가장 높은 성장률을 기록하고 있습니다. 중국의 단계별 병원 제도에서는 소아 1형 당뇨병 환자를 대상으로 특정 패치형 펌프에 대한 보험 적용이 이루어지고 있는 반면, 인도에서는 2형 당뇨병 성인 환자를 대상으로 저비용 구독 번들이 시범적으로 도입되고 있습니다. 라틴아메리카는 성장률의 극단적인 양극단 중간에 위치해 있으며, 브라질과 멕시코가 이 지역의 확산을 주도하고 있고, 민간 보험사들이 가치 기반 당뇨병 프로그램을 시범적으로 시행하고 있습니다. 시장에 진출한 기업들은 각 지역의 사회경제적 특성에 맞추어 현지 언어 지원, 고온 기후에 적합한 접착제 배합, 유연한 자금 조달 수단 제공에 주력하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the insulin infusion pumps market size was valued at USD 4.08 billion in 2025 and estimated to grow from USD 4.3 billion in 2026 to reach USD 5.59 billion by 2031, at a CAGR of 5.38% during the forecast period (2026-2031).
This report Segments the Industry Into by Component (Insulin Pump Devices, Infusion Sets, Reservoirs), Pump Type (Tethered Pumps, Patch Pumps, Implantable Pumps), Patient Type (Type-1 Diabetes, Type-2 Diabetes), End User (Hospitals & Clinics, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Insulin Infusion Pumps Market Trends and Insights
Rapid Adoption of Closed-Loop "Artificial Pancreas" Systems
FDA approval of Medtronic's MiniMed 780G in April 2025 underscored the value of automated meal detection and five-minute insulin adjustments, pushing time-in-range figures above 70% among large user cohorts. Tandem's Control-IQ platform shows comparable benefits, highlighting a technology race that rewards algorithm accuracy and sensor reliability. Artificial intelligence enables dose personalization that mimics physiologic insulin patterns, positioning closed-loop platforms as the future standard of care. Growing clinical proof amplifies payer confidence and broadens eligibility criteria. As marketing emphasizes lifestyle simplicity instead of device mechanics, patient receptivity rises, driving incremental units and recurring consumable sales.
Rising Prevalence of Type 1 Diabetes in Youth
Incidence rates among children now exceed 3.5 per 1,000 in the United States, with similar uptrends in Europe and parts of Asia. Pediatric societies recommend pump therapy as first-line treatment, citing superior glycemic control and reduced nocturnal hypoglycemia. FDA clearance of automated insulin delivery for ages two and above widens the pediatric addressable pool. Regional registries reveal adoption gaps, suggesting unmet demand where clinical support lags. Manufacturers respond with smaller reservoirs, simplified user interfaces, and colorful patch adhesives that resonate with younger users and caregivers.
Cybersecurity Risks in Connected Devices
In 2024 the FDA flagged vulnerabilities in certain wireless pumps that could allow unauthorized access and unintended insulin delivery, prompting multiple Class I recalls. Academic analyses have since documented potential exploit pathways via unsecured Bluetooth channels, underscoring the need for end-to-end encryption and tamper-proof firmware. New FDA premarket guidance requires threat-mitigation plans and postmarket monitoring, adding development cost and elongating approval timelines. Hospitals now press suppliers for detailed cybersecurity certifications before procurement. Although no catastrophic patient harm has been reported publicly, lingering risk perception may slow adoption among risk-averse payers.
Other drivers and restraints analyzed in the detailed report include:
- Reimbursement Expansion for Tubeless Pumps
- Rising Adoption of DIY Looping Systems
- High Out-of-Pocket Costs in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Insulin pump devices retained 65.12% of 2025 revenue, underscoring their premium pricing and embedded software complexity. Consumable reservoirs, however, expanded faster at an 7.62% CAGR as hybrid closed-loop algorithms modulated insulin micro-boluses more frequently. Integration of smart sensors inside reservoirs to detect occlusions and air bubbles heightens patient safety and gives vendors cross-selling leverage. Strategic partnerships, such as Medtronic pairing its pumps with Abbott glucose sensors, exemplify an ecosystem approach that influences procurement.
Consumable dynamics also strengthen recurring revenue visibility. Manufacturers introduce extended-wear infusion sets aimed at seven-day site usage, reducing insertion trauma and driving brand loyalty. Competitive differentiation now hinges on frictionless cartridge loading, lower residual insulin waste, and antimicrobial linings that curb infection risk. These incremental innovations stabilize unit volume outlook, even when device replacement cycles lengthen in mature markets.
Patch pumps captured 52.05% share in 2025 and are on track for an 8.28% CAGR, validating patient preference for tubeless, discreet wearables. Sleek industrial design, waterproof housing, and automated cannula insertion raise user comfort and minimize social stigma. Tethered pumps, while declining, still serve high-dose users who need large reservoirs or dual-hormone research protocols. Implantable systems remain experimental due to surgical hurdles.
Competition within the patch segment intensifies as Tandem's Mobi challenges Insulet's incumbency with a thinner profile and smartphone-only interface. Emerging entrants position low-cost patch alternatives for Asia-Pacific, bundling simplified feature sets with subscription pricing. Firmware upgrades delivered over the air enhance functionality without physical replacements, reinforcing user stickiness.
Complete Report Scope:
- By Component
- Insulin Pump Devices
- Infusion Sets
- Reservoirs
- By Pump Type
- Tethered Pumps
- Patch Pumps
- Implantable Pumps
- By Patient Type
- Type-1 Diabetes
- Type-2 Diabetes
- By End User
- Hospitals & Clinics
- Homecare Settings
- Ambulatory Surgical Centers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America remained the largest market in 2025 with a 36.95% share, underpinned by widespread insurance coverage, advanced supply chains, and early demand from both Type 1 and Type 2 populations. The region's mature infrastructure supports swift adoption of closed-loop upgrades and interoperable component ecosystems, though unit growth now mirrors replacement cycles more than net new users. Cybersecurity regulations also originate here, influencing global design standards.
Europe contributes steady volumes thanks to universal healthcare and robust clinical registries that benchmark outcomes. Reimbursement frameworks vary but generally favor technology proven to cut hospitalization costs. Rapid CE-mark pathways for integrated pumps and continuous glucose monitors promote competitive diversity. The Middle East and Africa lag in penetration, yet investment initiatives in Saudi Arabia and the UAE spark pilot programs that introduce patch pumps into public diabetes centers. Asia-Pacific posts the fastest 6.72% CAGR through 2031 due to rising diabetes prevalence, urbanization, and expanding middle-class insurance pools. China's tiered hospital system now reimburses select patch pumps for pediatric Type 1 users, while India experiments with low-cost subscription bundles for Type 2 adults. Latin America sits between growth extremes, with Brazil and Mexico leading regional adoption as private insurers pilot value-based diabetes programs. Market entrants target localized language support, hotter-climate adhesive formulations, and flexible financing to fit each region's socioeconomic profile.
- Medtronic
- Insulet
- Tandem Diabetes Care
- Roche
- Ypsomed
- SOOIL Development
- EOFlow
- Beta Bionics
- CeQur
- Debiotech
- Medtrum Technologies
- MicroPort
- Terumo
- Beckton Dickinson
- Bigfoot Biomedical
- ViCentra
- Cambridge Medical Robotics
- Valeritas
- Smiths Group
- Delta Life
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Closed-Loop "Artificial Pancreas" Systems
- 4.2.2 Rising Prevalence of Type 1 Diabetes in Youth
- 4.2.3 Reimbursement Expansion for Tubeless Pumps
- 4.2.4 Growth of the DIY Looping Community
- 4.2.5 Bluetooth-Enabled Analytics and Mobile Integration
- 4.2.6 Inclusion in Corporate Wellness Programs
- 4.3 Market Restraints
- 4.3.1 Cybersecurity Risks in Connected Devices
- 4.3.2 High Out-of-Pocket Costs in Emerging Markets
- 4.3.3 Supply Chain Disruptions for Sterile Tubing and Components
- 4.3.4 Regulatory Delays for Next-Gen Devices
- 4.4 Market Indicators
- 4.4.1 Type-1 Diabetes Population Analysis
- 4.4.2 Type-2 Diabetes Population Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Component
- 5.1.1 Insulin Pump Devices
- 5.1.2 Infusion Sets
- 5.1.3 Reservoirs
- 5.2 By Pump Type
- 5.2.1 Tethered Pumps
- 5.2.2 Patch Pumps
- 5.2.3 Implantable Pumps
- 5.3 By Patient Type
- 5.3.1 Type-1 Diabetes
- 5.3.2 Type-2 Diabetes
- 5.4 By End User
- 5.4.1 Hospitals & Clinics
- 5.4.2 Homecare Settings
- 5.4.3 Ambulatory Surgical Centers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Medtronic
- 6.3.2 Insulet
- 6.3.3 Tandem Diabetes Care
- 6.3.4 Roche Diabetes Care
- 6.3.5 Ypsomed
- 6.3.6 SOOIL Development
- 6.3.7 EOFlow
- 6.3.8 Beta Bionics
- 6.3.9 CeQur
- 6.3.10 Debiotech
- 6.3.11 Medtrum Technologies
- 6.3.12 MicroPort
- 6.3.13 Terumo
- 6.3.14 Becton, Dickinson & Co.
- 6.3.15 Bigfoot Biomedical
- 6.3.16 ViCentra
- 6.3.17 Cambridge Medical Robotics
- 6.3.18 Valeritas
- 6.3.19 Smiths Medical
- 6.3.20 Delta Life
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment