

|
시장보고서
상품코드
2121715
비즈니스 애널리틱스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Business Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
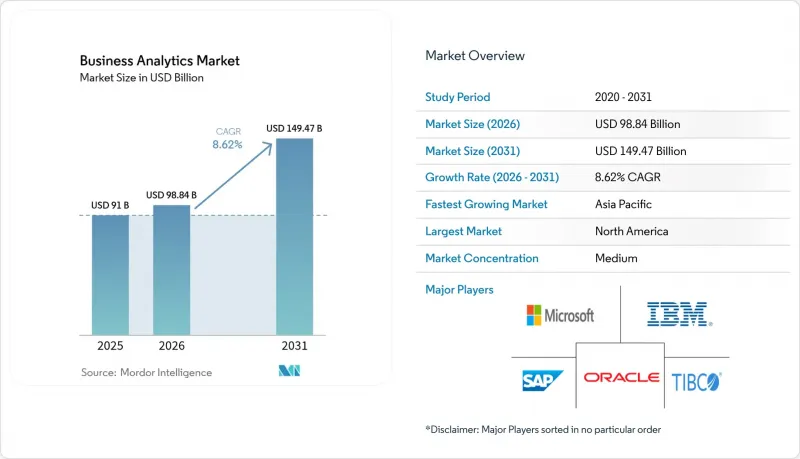
에 의하면, 비즈니스 애널리틱스 시장 규모는 2025년에 910억 달러로 평가되었고, 2026년 988억 4,000만 달러에서 2031년까지 1,494억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 8.62%를 기록할 전망입니다.
본 보고서는 도입 모델(On-Premise, 클라우드), 분석 유형(기술적 분석, 진단적 분석 등), 조직 규모(대기업, 중소기업), 최종 사용자 산업(은행, 금융서비스 및 보험(BFSI), 헬스케어 및 생명과학 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계 비즈니스 애널리틱스 시장 동향 및 인사이트
분석 플랫폼에 대한 AI 및 ML 통합
인공지능은 비즈니스 분석 플랫폼에서 단순한 부가 기능에서 핵심 기능으로 전환되었습니다. Snowflake Cortex나 Microsoft 365 Copilot의 Analyst 에이전트와 같은 새로운 제품들은 자연어를 해석하고, SQL을 자동 생성하며, 과거에는 데이터 사이언스자가 필요했던 예측적 인사이트를 제시합니다. 이러한 기능을 도입한 기업에서는 마케팅, 공급망 및 재무 팀에서 30-50%의 생산성 향상이 보고되고 있습니다. 모델 훈련 비용이 낮아짐에 따라 벤더들은 생성형 AI를 통합하고, 접근성을 확대하며, 데이터 전처리를 자동화하고 있습니다. 이로 인해 자율형 에이전트가 사람의 코딩 없이도 복잡한 분석 파이프라인을 조정하는 ‘에이전트형 애널리틱스’의 시대가 도래하고 있습니다.
빅데이터의 급증과 클라우드의 보급
데이터의 양, 속도, 다양성은 계속해서 증가하고 있습니다. 6,000개가 넘는 조직이 BigQuery에서 매주 275페타바이트 이상의 데이터를 처리하고 있으며, 이는 탄력적인 클라우드 스토리지와 컴퓨팅이 분석의 기반으로 자리 잡았음을 여실히 보여줍니다. ClickHouse와 AWS 간의 5년 계약과 같은 공동 혁신 프로그램을 통해 금융 및 전자상거래 워크로드에 특화된 솔루션 개발이 가속화되고 있습니다. 또한 클라우드 프레임워크를 통해 기업은 On-Premise IoT 데이터 처리와 통합 대시보드를 결합할 수 있게 되어, 산업 분야에서 설비 효율을 10% 향상시키고 예기치 못한 다운타임을 30% 줄이고 있습니다.
데이터 주권에 관한 규제
GDPR(EU 개인정보보호규정), CLOUD법, 그리고 새로 제정되고 있는 각국의 법률 간에 규정이 상충하고 있어, 다국적 기업은 지역별로 특화된 데이터 스택을 구축할 수밖에 없습니다. 도입 시에는 현지 처리, 암호화된 전송, 그리고 감사 가능한 동의를 확보해야 하므로 비용과 복잡성이 증가하고 있습니다. 하이퍼스케일러 및 지역 제공업체가 제공하는 ‘소버린 클라우드’ 서비스가 이 문제를 해결하고 있지만, 조직은 여전히 분석의 일관성을 해치지 않으면서 규제 당국의 요구 사항을 충족하기 위해 여러 공급업체와 관리 체계를 능숙하게 조정해야 합니다.
부문 분석
클라우드 부문은 2025년 매출의 64.72%를 차지하고 있으며, 연평균 성장률(CAGR) 10.18%를 고려할 때 2031년까지 비즈니스 분석 시장 규모에서 더 큰 점유율을 차지하게 될 것입니다. 설비 투자 절감, 유연한 확장성, 데이터 레이크 및 AI 서비스와의 신속한 통합이 그 매력을 확고히 하고 있습니다. 보안 인증 및 자동화된 규정 준수 기능은 현재 금융, 의료, 정부 기관의 워크로드를 포괄하고 있으며, On-Premise 지지자들의 마지막 보루를 서서히 무너뜨리고 있습니다.
엄격한 지연 시간 요구 사항, 레거시 시스템과의 통합 또는 규제상의 의무가 존재하는 상황에서는 On-Premise 배포가 여전히 남아 있지만, 그 점유율은 해마다 줄어들고 있습니다. 기밀성이 높은 워크로드를 방화벽 내부에 남겨두면서 버스트 처리를 클라우드로 이전하는 하이브리드 방식의 접근법은 전환을 위한 로드맵을 제시합니다. 각 제공업체는 마이그레이션 툴킷, 관리형 서비스, 종량제 요금제를 결합하여 클라우드 전환을 주저하는 고객을 뒷받침함으로써, 시장 리더가자 성장 엔진으로서의 클라우드의 입지를 강화하고 있습니다.
기술적 분석은 2025년 매출의 32.05%를 차지하며 비즈니스 분석 시장에서 가장 큰 점유율을 유지했지만, 예측 분석 기술은 연평균 성장률(CAGR) 8.74%로 모든 카테고리를 능가하는 성장세를 보이고 있습니다. 조직은 ‘무슨 일이 일어났는지’를 보여주는 대시보드에서 벗어나, 고객 이탈 위험을 경고하고, 재고를 최적화하며, 고장이 발생하기 전에 유지보수 인력을 파견하는 등 미래를 내다보는 모델로 진화하고 있습니다. 생성형 AI는 복잡한 시계열 모델의 자동 코딩과 기술적 지식이 없는 사용자를 위한 시나리오 시뮬레이션 제시를 통해 예측 워크플로우를 강화합니다.
진단 분석은 근본 원인을 규명하고, 예측 알고리즘에 특징량을 공급하는 가교 역할을 합니다. 처방 분석 도구는 예산이나 인력 배치 등의 제약 조건 하에서 최적의 행동을 권장함으로써 루프를 완성합니다. 생산 일정 최적화를 통해 한 소비재 제조업체가 주당 최대 20만 달러를 절감한 초기 성공 사례가 더 광범위한 도입을 뒷받침하고 있습니다. 툴킷이 성숙해짐에 따라, 예측 분석과 처방 분석 계층이 연계되어 과거 데이터를 기능 간을 아우르는 맥락을 인식하는 자동화된 의사 결정으로 전환해 나갈 것입니다.
지역별 분석
북미는 성숙한 기술 생태계, 풍부한 인재, 그리고 클라우드의 조기 도입을 통해 2025년 매출의 26.98%를 차지하고 있습니다. 기업들은 AI 가속기, 스트리밍 파이프라인, 자동화된 거버넌스를 활용하여 기존 플랫폼을 정교화하고, 확립된 데이터 자산에서 더 큰 효율성을 이끌어내고 있습니다. 미국이 지출을 주도하고 있으며, 캐나다는 천연 자원 및 금융 서비스와 같은 수직 시장에서 분석 기술을 활용하고 있습니다. 멕시코는 수출 지향적 제조업과 국경을 넘는 물류를 지원하기 위해 클라우드 플랫폼을 도입하고 있습니다.
아시아태평양은 정부의 AI 전략, 모바일의 광범위한 보급, 그리고 그린필드에서의 클라우드 도입에 힘입어 연평균 성장률(CAGR) 10.12%로 가장 빠르게 성장하고 있는 지역입니다. 중국은 대규모 디지털 결제 생태계와 산업 고도화 프로그램의 뒷받침을 받아 해당 지역 비즈니스 분석 시장의 37.5%를 차지하고 있습니다. 베트남이나 필리핀과 같은 고성장 경제국에서는 중소기업들이 레거시 시스템을 뛰어넘기 위해 SaaS형 분석 솔루션을 도입하고 있으며, 연간 성장률은 19%를 초과하고 있습니다. 인도, 일본, 한국, 태국에서는 공공 부문의 보조금을 노동력의 기술 향상 및 데이터 생태계 개발에 활용하고 있어, 플랫폼 공급업체에게 유리한 환경이 조성되어 있습니다.
유럽은 엄격한 개인정보 보호 규제와 산업 디지털화를 위한 자금 지원에 힘입어 꾸준히 전진하고 있습니다. 독일, 프랑스, 영국에서는 제조 효율성 향상 및 금융 규정 준수를 위해 분석 솔루션이 도입되고 있는 반면, 남유럽 국가들에서는 관광 및 소매 분야에서의 분석 활용 사례가 확대되고 있습니다. 소버린 클라우드 프레임워크와 개인정보 보호 강화 기술은 GDPR(EU 개인정보보호규정)로 인한 수요에 대응하고 있습니다. 중동 및 아프리카에서는 특히 걸프 국가들이 스마트 시티 구상의 혜택을 누리고 있습니다. 한편, 남미에서는 브라질과 아르헨티나를 중심으로 클라우드 보급이 확대되며 성장세를 보이고 있지만, 인프라 격차와 환율 변동이 도입 속도를 둔화시키고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the business analytics market size was valued at USD 91 billion in 2025 and estimated to grow from USD 98.84 billion in 2026 to reach USD 149.47 billion by 2031, at a CAGR of 8.62% during the forecast period (2026-2031).
This report is Segmented by Deployment Model (On-Premises, Cloud), Analytics Type (Descriptive, Diagnostic, and More), Organization Size (Large Enterprises, Smes), End-User Industry (BFSI, Healthcare and Life Sciences, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Business Analytics Market Trends and Insights
AI and ML infusion into analytics platforms
Artificial intelligence has shifted from a bolt-on feature to a core capability within business analytics platforms. New releases such as Snowflake Cortex and Microsoft 365 Copilot's Analyst agent interpret natural language, auto-generate SQL, and surface predictive insights that once required a data scientist. Companies adopting these capabilities report 30-50% productivity lifts in marketing, supply-chain, and finance teams. As model training costs fall, platform vendors embed generative AI to widen access and automate data preparation, ushering in an era of "agentic analytics" where autonomous agents orchestrate complex analysis pipelines without human coding.
Proliferation of big data and cloud adoption
Volume, velocity, and variety of data keep rising. More than 6,000 organizations exchange upward of 275 petabytes each week on BigQuery, highlighting how elastic cloud storage and compute have become the default substrate for analytics. Joint innovation programs, such as the five-year agreement between ClickHouse and AWS, accelerate purpose-built solutions for finance and e-commerce workloads. Cloud frameworks also let firms pair localized IoT data processing with centralized dashboards, delivering 10% gains in equipment efficiency and 30% reductions in unplanned downtime in industrial settings.
Data-sovereignty restrictions
Conflicting rules among GDPR, the CLOUD Act, and emerging national laws force multinationals to architect region-specific data stacks. Deployments must ensure local processing, encrypted transfers, and auditable consent, adding cost and complexity.Sovereign-cloud offerings from hyperscalers and regional providers address the issue, yet organizations still juggle multiple vendors and controls to satisfy regulators without fracturing analytical coherence.
Other drivers and restraints analyzed in the detailed report include:
- Need for real-time decision-making
- Edge analytics for IoT-heavy industries
- Talent shortage in advanced analytics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The cloud segment accounts for 64.72% of 2025 revenue, and its 10.18% CAGR means it will command an even larger slice of the business analytics market size by 2031. Lower capital expenditure, elastic scaling, and rapid integration with data lakes and AI services cement its appeal. Security certifications and automated compliance features now cover finance, healthcare, and government workloads, eroding the last strongholds of on-premise advocates.
On-premise deployments persist where strict latency, legacy integration, or regulatory mandates prevail, but their share recedes every year. Hybrid blueprints, in which sensitive workloads stay behind the firewall while burst processing moves to the cloud, offer a transitional path. Providers bundle migration toolkits, managed services, and consumption-based pricing to nudge hesitant customers toward the cloud, reinforcing its position as both market leader and growth engine.
Descriptive analytics retained 32.05% of 2025 revenue, the largest slice of the business analytics market, yet predictive techniques outpace all categories with an 8.74% CAGR. Organizations evolve from "what happened" dashboards to forward-looking models that flag churn risk, optimize inventory, and route maintenance crews before breakdowns occur. Generative AI enhances predictive workflows by auto-coding complex time-series models and surfacing scenario simulations for non-technical users.
Diagnostic analytics serves as a bridge, explaining root causes and feeding features into forecasting algorithms. Prescriptive tools close the loop by recommending the best action under constraints such as budget or staffing. Early success stories like a consumer-products maker saving up to USD 200,000 weekly through optimized production schedules fuel wider adoption. As toolkits mature, predictive and prescriptive layers will jointly convert historical data into automated, context-aware decisions across functions.
Complete Report Scope:
- By Deployment Model
- On-Premise
- Cloud
- By Analytics Type
- Descriptive
- Diagnostic
- Predictive
- Prescriptive
- By Organisation Size
- Large Enterprises
- Small and Mid-sized Enterprises (SMEs)
- By End-user Industry
- Banking, Financial Services and Insurance (BFSI)
- Healthcare and Life Sciences
- Manufacturing
- Retail and E-commerce
- Telecom and IT
- Government and Public Sector
- Energy and Utilities
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America holds 26.98% of 2025 revenue thanks to a mature technology ecosystem, abundant talent, and early cloud adoption. Enterprises refine existing platforms with AI accelerators, streaming pipelines, and automated governance, squeezing incremental efficiency from established data assets. The United States leads spending, and Canada leverages analytics in natural-resources and financial-services verticals. Mexico adopts cloud platforms to support export-oriented manufacturing and cross-border logistics.
Asia Pacific is the fastest-growing region at a 10.12% CAGR, fueled by government AI strategies, widespread mobile adoption, and greenfield cloud deployments. China commands 37.5% of the regional business analytics market, backed by large-scale digital payment ecosystems and industrial upgrade programs. High-growth economies such as Vietnam and the Philippines exceed 19% annual expansion as SMEs embrace SaaS analytics to leapfrog legacy systems. India, Japan, South Korea, and Thailand channel public-sector grants into workforce upskilling and data-ecosystem development, creating fertile ground for platform vendors.
Europe advances steadily underpinned by strong privacy regulations and industry digitization funding. Germany, France, and the United Kingdom deploy analytics for manufacturing efficiency and financial compliance, while southern nations expand tourism and retail analytics use cases. Sovereign-cloud frameworks and privacy-enhancing technologies address GDPR-driven demands. The Middle East and Africa benefit from smart-city agendas, especially in the Gulf states, whereas South America gains traction through cloud uptake in Brazil and Argentina, although infrastructure gaps and currency volatility temper the slope of adoption
- Microsoft Corp.
- SAP SE
- Oracle Corp.
- IBM Corp.
- Salesforce Inc. (Tableau)
- SAS Institute Inc.
- TIBCO Software Inc.
- Qlik Tech Intl.
- MicroStrategy Inc.
- Infor Inc.
- Google LLC (Looker)
- Amazon Web Services (QuickSight)
- Domo Inc.
- Sisense Ltd.
- ThoughtSpot Inc.
- Alteryx Inc.
- Zoho Corp. (Zoho Analytics)
- Board International
- GoodData Corp.
- Yellowfin BI
- Pyramid Analytics
- Logi Analytics (InsightSoftware)
- Teradata Corp.
- Informatica Inc.
- Palantir Technologies
- Snowflake Inc.
- Databricks Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of big data and cloud adoption
- 4.2.2 Need for real-time decision-making
- 4.2.3 AI/ML infusion into analytics platforms
- 4.2.4 Regulatory push for data-driven compliance
- 4.2.5 Edge analytics for IoT-heavy industries
- 4.2.6 Privacy-preserving data clean rooms
- 4.3 Market Restraints
- 4.3.1 High upfront cost and ROI uncertainty
- 4.3.2 Talent shortage in advanced analytics
- 4.3.3 Data-sovereignty restrictions
- 4.3.4 ESG-data quality gaps
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 On-Premise
- 5.1.2 Cloud
- 5.2 By Analytics Type
- 5.2.1 Descriptive
- 5.2.2 Diagnostic
- 5.2.3 Predictive
- 5.2.4 Prescriptive
- 5.3 By Organisation Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Mid-sized Enterprises (SMEs)
- 5.4 By End-user Industry
- 5.4.1 Banking, Financial Services and Insurance (BFSI)
- 5.4.2 Healthcare and Life Sciences
- 5.4.3 Manufacturing
- 5.4.4 Retail and E-commerce
- 5.4.5 Telecom and IT
- 5.4.6 Government and Public Sector
- 5.4.7 Energy and Utilities
- 5.4.8 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Southeast Asia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Funding Activity
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Microsoft Corp.
- 6.4.2 SAP SE
- 6.4.3 Oracle Corp.
- 6.4.4 IBM Corp.
- 6.4.5 Salesforce Inc. (Tableau)
- 6.4.6 SAS Institute Inc.
- 6.4.7 TIBCO Software Inc.
- 6.4.8 Qlik Tech Intl.
- 6.4.9 MicroStrategy Inc.
- 6.4.10 Infor Inc.
- 6.4.11 Google LLC (Looker)
- 6.4.12 Amazon Web Services (QuickSight)
- 6.4.13 Domo Inc.
- 6.4.14 Sisense Ltd.
- 6.4.15 ThoughtSpot Inc.
- 6.4.16 Alteryx Inc.
- 6.4.17 Zoho Corp. (Zoho Analytics)
- 6.4.18 Board International
- 6.4.19 GoodData Corp.
- 6.4.20 Yellowfin BI
- 6.4.21 Pyramid Analytics
- 6.4.22 Logi Analytics (InsightSoftware)
- 6.4.23 Teradata Corp.
- 6.4.24 Informatica Inc.
- 6.4.25 Palantir Technologies
- 6.4.26 Snowflake Inc.
- 6.4.27 Databricks Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


