

|
시장보고서
상품코드
2121728
실리콘상 LCD(LCoS) 디스플레이 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Liquid Crystal On Silicon (LCoS) Display - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 실리콘상 LCD(LCoS) 디스플레이 시장 규모는 2026년에 32억 6,000만 달러에 이르고, 2031년까지 51억 6,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 9.62%를 기록할 전망입니다.
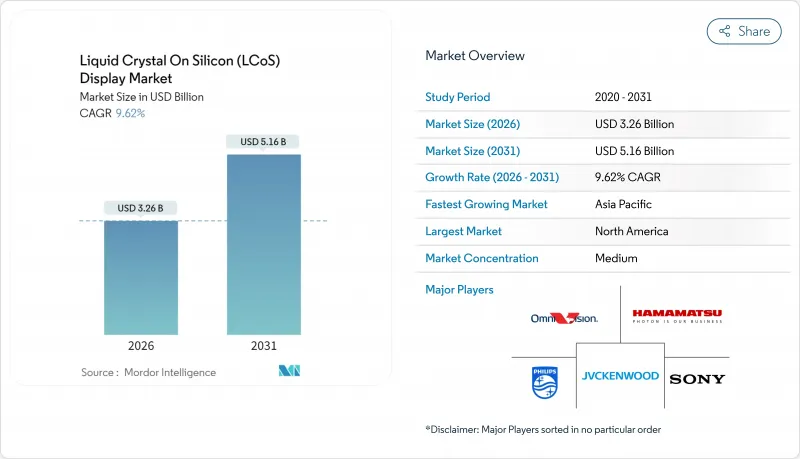
본 보고서는 제품별(헤드마운트 디스플레이, 프로젝터, 기타), 기술별(강유전체 LCoS, 네마틱 LCoS, 기타), 최종 사용자별(가정용 전자기기, 자동차, 기타),용도별(디스플레이 용도, 디스플레이 외 용도), 해상도별(HD, 풀 HD(1080p), 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 실리콘 기반 액정 디스플레이 시장 동향 및 인사이트
고해상도 디스플레이 제품에 대한 수요 증가
전문용 시뮬레이터, 수술용 현미경, 홈 시어터 애호가들 사이에서는 4K 및 8K 요구 사항이 주류를 이루고 있으며, 실리콘 상 액정 디스플레이 시장은 3마이크로미터 이하의 픽셀 피치로 이에 부응하고 있습니다. 소니의 VPL-GTZ380은 1.38인치 패널 3장을 적층하여, 외과 훈련용 혈관의 세부 사항까지 재현하는 네이티브 8K 이미지를 구현하고 있습니다. 각 패널 제조업체들은 수율을 유지하기 위해 침지형 포토리소그래피를 채택하고 있으며, 이로 인해 설비 투자는 증가하지만 시장 진입 장벽은 높아지고 있습니다. 가격적인 제약으로 인해 일반 소비자용 프로젝터에서의 4K 보급은 주춤하고 있지만, 기업 및 교육 기관 고객들은 미세한 글자의 가독성 기준을 충족하기 위해 더욱 신속하게 기기 교체를 진행하고 있습니다. 그 결과, 고해상도 패널은 향후 수익에서 점점 더 큰 비중을 차지할 것으로 예측됩니다.
소비자용 기기 및 HMD에서의 AR·VR 도입
더 얇은 헤드셋에는 팔을 뻗은 거리에서 볼 때 스크린 도어 효과를 해소할 수 있는 화소 밀도가 요구됩니다. 옴니비전(OmniVision)이 2025년 12월에 발표한 OP03021 칩은 대각선 0.39인치 화면에 1920×1080 픽셀을 집적하고 120Hz의 주사율을 구현함으로써,혼합현실(Mixed Reality) 안경의 무게를 100g 이하로 억제할 수 있게 했습니다. 이에 이어 하이맥스(Hi-Max)사는 광로 길이를 30% 단축하는 듀얼 엣지 프론트 라이트 방식을 채택하여, 설계자가 더 얇은 템플 암을 설계할 수 있도록 했습니다. 이러한 발전으로 인해, 보다 광범위한 LCoS(Liquid Crystal On Silicon) 디스플레이 시장의 HMD 출하 대수는 연평균 성장률(CAGR) 10.22%로 성장을 지속하고, 있습니다. 또한, 1밀리초 이내에 전환되는 강유전체 모드는 사용자의 쾌적성을 보장하기 위한 임계치인 ‘모션 투 포토(Motion to Photon)’의 지연을 10밀리초 이하로 억제하는 데 매우 중요합니다.
기술 개발 및 제조의 높은 비용
3마이크로미터 이하의 패터닝 장비는 1대당 1억 달러 이상의 비용이 들며, 액정 배향이 어긋날 경우 초기 수율 손실이 20%에 달할 가능성이 있습니다. 재팬 디스플레이는 이러한 설비 투자 부담을 분리하기 위해 2025년 10월, 자동차용 마이크로 디스플레이 사업을 AutoTech로 분사했습니다. 또한, 가전제품 바이어들도 매년 가격 인하를 요구하고 있어, 이익률 회복을 저해하고 있습니다. 이러한 경제적 요인으로 인해 신규 진입이 억제되고 있으며, 고해상도 디스플레이 생산 능력의 대부분은 여전히 일본, 한국, 대만에 집중되어 있습니다.
부문별 분석
2025년, 이 부문은 프로젝터 부문에서 LCoS(Liquid Crystal On Silicon) 디스플레이 시장 규모에서 가장 큰 점유율을 차지했으며, 프로젝터가 매출의 46.06%를 차지했습니다. 그러나 헤드 마운트 디스플레이는 연평균 10.22%라는 더 빠른 속도로 성장할 것으로 전망됩니다. 피코 프로젝터는 조작 화면을 벽에 투사하는 스마트 홈용 인터페이스로 중심을 옮겨가고 있습니다. 한편, 공간 광 변조기(SLM) 패널은 틈새 시장이지만, 연구 기관들이 위상 정밀도에 높은 가치를 인정하고 있어 가장 높은 가격대를 유지하고 있습니다.
옴니비전(OmniVision)의 OP03021은 대각선 0.39인치 이내에서 망막 해상도의 픽셀을 구현하여, 소비자용 AR 안경의 무게를 100g 이하로 억제할 수 있게 함으로써 HMD의 성장세를 더욱 강화하고 있습니다. 반면, 전문 영화관 운영자들은 8만 달러짜리 8K 프로젝터에 대한 투자를 지속하고 있으며, 이로 인해 기존 벤더들의 현금 흐름이 유지되고 있습니다. 이러한 양면성으로 인해 LCoS 디스플레이 시장은 비용 중심의 소비자용 제품과 프리미엄 프로젝션 솔루션 사이에서 균형을 유지하고 있습니다.
2025년 매출액에서 네마틱 방식은 여전히 60.11%를 차지하고 있지만, 강유전체 방식의 점유율은 가장 빠르게 확대되고 있으며, LCoS(Liquid Crystal On Silicon) 디스플레이 시장 전체를 상회하는 연평균 성장률(CAGR) 10.54%에 힘입고 있습니다. 강유전체 액정은 100µs 이하에서 스위칭이 가능하여, 홀로그래픽 LiDAR 및 가변 초점 AR 광학 시스템에 필수적입니다.
프라운호퍼 IPMS는 자동차용 LiDAR의 빔을 실시간으로 재구성하는 이진 강유전체 패널을 시연했습니다. 자발 분극으로 인해 배향에 민감해지기 때문에 수율 문제는 여전히 남아 있으며, 결함률은 15%를 초과하고 있습니다. 그럼에도 불구하고, 방위 및 포토닉스 부문의 구매자들은 지연 시간 단축을 위해 30%의 가격 프리미엄을 감수하고 있으며, 이 공정을 숙달한 공급업체에게는 건실한 이익률이 보장되고 있습니다.
지역별 분석
북미는 기업용 프로젝터 판매 호조, 방위용 헬멧 수주, 외과 수술 및 물류 부문에서의 AR 초기 실증 프로젝트에 힘입어 2025년 매출의 34.38%를 차지했습니다. 국립 연구소 등 연구 기관이 위상형 공간 광 변조기의 대부분을 구매함에 따라 현지 수요가 더욱 강화되었습니다. ‘CHIPS and Science Act’에 따라 국내 팹 설립이 촉진될 것으로 예상되지만, 2026년 초 시점에서는 새로운 생산 라인의 착공에 이르지 못했습니다.
아시아태평양은 연평균 성장률(CAGR) 10.94%로 확대될 것으로 예측되며, 이는 세계에서 가장 빠른 속도입니다. 일본의 기존 기업들은 구형 LCD 팹을 마이크로디스플레이용으로 전환하고 있으며, 한국의 기업 그룹은 AR 부품에 대한 투자를 추진하고, 중국은 액정용 화학물질 공급망을 통합하고 있습니다. Slichem이 DIC의 유체 사업을 인수함에 따라 중국 패널 제조업체들은 주요 자재를 자체 조달할 수 있게 되었으나, 유럽과 미국의 주요 방위 기업들은 현재 공급망을 더욱 엄격하게 심사하고 있습니다.
유럽은 자동차용 HUD 프로그램에 힘입어 중간 순위를 차지하고 있습니다. 유로 NCAP의 2025년 평가 기준 개정에서는 증강현실(AR) 디스플레이가 평가 대상에 포함되게 되었으며, 이에 따라 독일 자동차 제조업체들은 신차에 파노라마 HUD를 기본 사양으로 탑재하고 있습니다. ‘호라이즌 유럽’은 2027년까지 포토닉스 부문에 12억 유로(13억 달러)를 배정하고 있으며, 그 일부는 LCoS(공간 광 변조기) 연구 자금으로 사용되고 있습니다. 중동 시장에서는 비행 시뮬레이션용으로 LCoS 시스템이 도입되고 있지만, 아프리카와 남미 시장은 여전히 발전 단계에 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.02According to Mordor Intelligence, the liquid crystal on silicon (LCoS) display market size stood at USD 3.26 billion in 2026 and is projected to reach USD 5.16 billion by 2031, expanding at a 9.62% CAGR over 2026-2031.
This report is Segmented by Product (Head-Mounted Display, Projector, and More), Technology (Ferroelectrics LCoS, Nematics LCoS, and More), End User (Consumer Electronics, Automotive, and More), Application (Display Applications, and Non-Display Applications), Resolution (HD, Full HD (1080p), and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Liquid Crystal On Silicon (LCoS) Display Market Trends and Insights
Increasing Demand for High-Resolution Display Products
Professional simulators, surgical microscopes, and home-theater enthusiasts are converging on 4K and 8K requirements, and the Liquid Crystal On Silicon (LCoS) display market is answering with sub-3 micrometer pixel pitches. Sony's VPL-GTZ380 stacks three 1.38-inch panels to achieve native 8K images that replicate vascular detail for surgical training. Panel makers are adopting immersion photolithography to maintain yields, which raises capex but fortifies entry barriers. While price limits slow 4K adoption in mainstream consumer projectors, corporate and education customers are upgrading faster to meet fine-text readability standards. As a result, high-resolution panels are expected to corner an ever-larger slice of future revenue.
Deployment of AR and VR in Consumer Devices and HMDs
Slimmer headsets need pixel densities that eliminate the screen-door effect at arm's-length viewing. OmniVision's December 2025 OP03021 chip integrates 1920 X 1080 pixels on a 0.39-inch diagonal and drives 120 Hz refresh, allowing mixed-reality glasses to weigh under 100 g. Himax followed with a dual-edge front-lit architecture that cuts optical-path length by 30%, letting designers carve thinner temple arms. Such gains underpin a 10.22% CAGR for HMD shipments within the wider Liquid Crystal On Silicon (LCoS) display market. Ferroelectric modes that switch in under a millisecond are also critical to reduce motion-to-photon latency below 10 ms, a threshold for user comfort.
High Cost of Technology Development and Manufacturing
Sub-3 micrometer patterning tools cost upward of USD 100 million each, and initial yield losses can hit 20% when liquid-crystal alignment drifts. Japan Display spun off its automotive micro display assets into AutoTech in October 2025 to ring-fence this capex pressure. Consumer-electronics buyers also demand annual price cuts, squeezing margin recovery. These economics discourage new entrants and keep most high-resolution capacity clustered in Japan, South Korea, and Taiwan.
Other drivers and restraints analyzed in the detailed report include:
- Growing Automotive Adoption of HUDs
- Emergence of Laser-Illuminated LCoS for High-Brightness Projectors
- Competition From OLED and MicroLED Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The segment generated the largest slice of the Liquid Crystal On Silicon (LCoS) display market size from projectors in 2025, with projectors holding 46.06% revenue. However, head-mounted displays are set to grow faster at 10.22% annually. Pico projectors are pivoting toward smart-home interfaces that project controls on walls, while spatial-light-modulator panels, though niche, command the highest prices because laboratories pay for phase accuracy.
OmniVision's OP03021 enabled retinal-resolution pixels within a 0.39-inch diagonal, allowing consumer AR glasses to weigh under 100 g and reinforcing HMD momentum. At the same time, professional cinema owners continue to invest in USD 80,000 8K projectors, preserving cash flow for legacy vendors. This dual narrative keeps the LCoS display market balanced between cost-sensitive consumer products and premium projection solutions.
Nematic modes still dominated 60.11% of 2025 revenue, yet the ferroelectric share is expanding fastest, supported by a 10.54% CAGR that outstrips the overall Liquid Crystal On Silicon (LCoS) display market. Ferroelectric liquid crystals switch in under 100 µs, essential for holographic LiDAR and varifocal AR optics.
Fraunhofer IPMS demonstrated binary ferroelectric panels that reconfigure automotive LiDAR beams in real time. Yield hurdles persist because spontaneous polarization makes alignment sensitive, lifting defect rates above 15%. Even so, buyers in defense and photonics tolerate 30% price premiums for latency gains, ensuring healthy margins for suppliers able to master the process.
Complete Report Scope:
- By Product
- Head-Mounted Display (HMD)
- Projector
- Head-Up Display (HUD)
- Pico Projector
- Spatial Light Modulator Panel
- By Technology
- Ferroelectrics LCoS (FLCoS)
- Nematics LCoS (NLCoS)
- Wavelength Selective Switching (WSS)
- Reflective LCoS
- Transmissive LCoS
- By End User
- Consumer Electronics
- Automotive
- Aviation
- Optical 3D Measurement
- Medical
- Military
- Industrial and Scientific
- By Application
- Display Applications
- Projectors
- Microdisplays for AR/VR HMDs
- Head-Up Displays
- Non-Display Applications
- Wavelength Selective Switching in Optical Telecom
- Beam Steering and LiDAR
- Spatial Light Modulators for Holography and 3D Printing
- Display Applications
- By Resolution
- HD (Less than equal to 720p)
- Full HD (1080p)
- WQHD (1440p)
- 4K and Above
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 34.38% of 2025 revenue thanks to strong enterprise projector sales, defense helmet orders, and early AR pilots in surgery and logistics. Research institutes such as national laboratories purchased the bulk of phase-only spatial light modulators, reinforcing local demand. The CHIPS and Science Act is expected to seed domestic fabs, though new lines had not broken ground by early 2026.
Asia-Pacific is forecast to expand at a 10.94% CAGR, the fastest rate worldwide. Japanese incumbents are repurposing older LCD fabs for micro displays, South Korean groups are investing in AR components, and China is consolidating liquid-crystal chemical supply. Slichem's acquisition of DIC's fluids allows Chinese panel makers to internalize key materials, but Western defense primes now vet supply chains more closely.
Europe sits mid-pack, buoyed by automotive HUD programs. Euro NCAP's 2025 scoring revisions reward augmented-reality displays, prompting German OEMs to standardize panoramic HUDs on new models. Horizon Europe earmarked EUR 1.2 billion (USD 1.3 billion) for photonics through 2027, part of which funds LCoS spatial-light-modulator research. Middle East markets buy LCoS systems for flight simulation, while Africa and South America remain nascent.
- Sony Corporation
- JVC Kenwood Corporation
- Himax Technologies Inc.
- OmniVision Technologies Inc.
- HOLOEYE Photonics AG
- Meadowlark Optics Inc.
- Hamamatsu Photonics KK
- Syndiant Inc.
- Canon Inc.
- Epson Corporation
- Kopin Corporation
- Forth Dimension Displays Ltd.
- Raontech Inc.
- AAXA Technologies Inc.
- MicroVision Inc.
- Magic Leap Inc.
- Google LLC
- Microsoft Corporation
- Koninklijke Philips NV
- May Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for High-Resolution Display Products
- 4.2.2 Deployment of AR and VR in Consumer Devices and HMDs
- 4.2.3 Growing Automotive Adoption of HUDs
- 4.2.4 Emergence of Laser-Illuminated LCoS for High-Brightness Projectors
- 4.2.5 Integration of LCoS Spatial Light Modulators in Quantum and Photonics Research
- 4.2.6 Government Funding for Advanced Microdisplay Manufacturing
- 4.3 Market Restraints
- 4.3.1 High Cost of Technology Development and Manufacturing
- 4.3.2 Competition From OLED and MicroLED Alternatives
- 4.3.3 Supply Chain Dependence on Specialized Liquid Crystal Materials
- 4.3.4 Thermal Management Challenges in High-Brightness LCoS Panels
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Head-Mounted Display (HMD)
- 5.1.2 Projector
- 5.1.3 Head-Up Display (HUD)
- 5.1.4 Pico Projector
- 5.1.5 Spatial Light Modulator Panel
- 5.2 By Technology
- 5.2.1 Ferroelectrics LCoS (FLCoS)
- 5.2.2 Nematics LCoS (NLCoS)
- 5.2.3 Wavelength Selective Switching (WSS)
- 5.2.4 Reflective LCoS
- 5.2.5 Transmissive LCoS
- 5.3 By End User
- 5.3.1 Consumer Electronics
- 5.3.2 Automotive
- 5.3.3 Aviation
- 5.3.4 Optical 3D Measurement
- 5.3.5 Medical
- 5.3.6 Military
- 5.3.7 Industrial and Scientific
- 5.4 By Application
- 5.4.1 Display Applications
- 5.4.1.1 Projectors
- 5.4.1.2 Microdisplays for AR/VR HMDs
- 5.4.1.3 Head-Up Displays
- 5.4.2 Non-Display Applications
- 5.4.2.1 Wavelength Selective Switching in Optical Telecom
- 5.4.2.2 Beam Steering and LiDAR
- 5.4.2.3 Spatial Light Modulators for Holography and 3D Printing
- 5.4.1 Display Applications
- 5.5 By Resolution
- 5.5.1 HD (Less than equal to 720p)
- 5.5.2 Full HD (1080p)
- 5.5.3 WQHD (1440p)
- 5.5.4 4K and Above
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia
- 5.6.4 Middle East
- 5.6.4.1 Israel
- 5.6.4.2 Saudi Arabia
- 5.6.4.3 United Arab Emirates
- 5.6.4.4 Turkey
- 5.6.4.5 Rest of Middle East
- 5.6.5 Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Egypt
- 5.6.5.3 Rest of Africa
- 5.6.6 South America
- 5.6.6.1 Brazil
- 5.6.6.2 Argentina
- 5.6.6.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Sony Corporation
- 6.4.2 JVC Kenwood Corporation
- 6.4.3 Himax Technologies Inc.
- 6.4.4 OmniVision Technologies Inc.
- 6.4.5 HOLOEYE Photonics AG
- 6.4.6 Meadowlark Optics Inc.
- 6.4.7 Hamamatsu Photonics KK
- 6.4.8 Syndiant Inc.
- 6.4.9 Canon Inc.
- 6.4.10 Epson Corporation
- 6.4.11 Kopin Corporation
- 6.4.12 Forth Dimension Displays Ltd.
- 6.4.13 Raontech Inc.
- 6.4.14 AAXA Technologies Inc.
- 6.4.15 MicroVision Inc.
- 6.4.16 Magic Leap Inc.
- 6.4.17 Google LLC
- 6.4.18 Microsoft Corporation
- 6.4.19 Koninklijke Philips NV
- 6.4.20 May Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


