|
시장보고서
상품코드
2121804
산업용 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Industrial Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
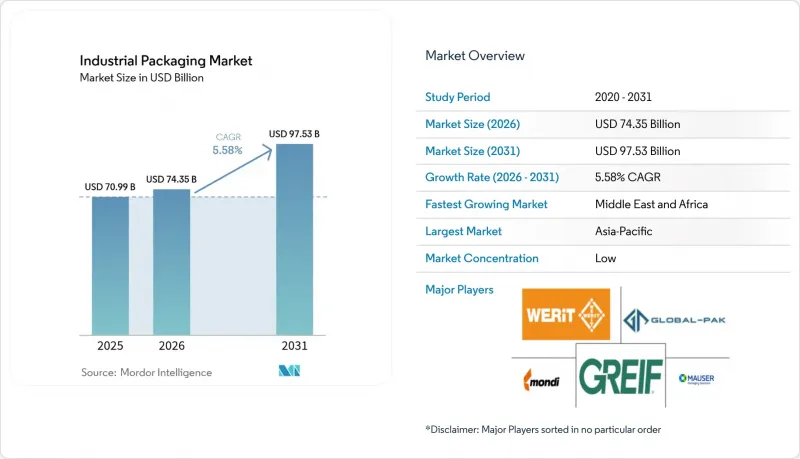
에 의하면, 산업용 포장 시장 규모는 2025년에 709억 9,000만 달러로 평가되었고, 2026년에 743억 5,000만 달러로 추정되고, 2031년까지 975억 3,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 5.58%로 성장할 전망입니다.
본 보고서는 제품 유형별(IBC, 드럼통, 자루, 페일통, 골판지 상자 등), 소재 유형별(플라스틱, 금속, 종이 및 섬유계 등), 포장 용량별(50L 이하, 51-500L, 501-1,000L 및 그 이상), 포장 형태별(경질 및 연질), 최종 사용자 산업별(화학·제약 및 기타), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시됩니다.
세계의 산업용 포장 시장 동향 및 인사이트
지속 가능하고 재활용 가능한 소재의 부상
규제 당국은 재생 재료 함유율에 대한 최소 기준과 완전한 재활용 가능성을 의무화하고 있으며, 이로 인해 가공업체들은 버진 수지로부터의 전환을 강요받고 있습니다. Mondi가 2025년에 출시할 예정인 종이 기반 IBC 라이너는 폴리에틸렌으로 만든 내부 백을 배제하면서도 수증기 투과율을 5 g/m2·일 미만으로 억제하여, 식품 등급 용도에서 섬유 기질의 유효성을 입증하고 있습니다. Mauser Packaging Solutions는 현재 오염된 HDPE 드럼을 버진 수지와 동등한 펠릿으로 변환하는 탈중합 라인을 가동하고 있으며, 이를 통해 위험물 용기의 순환 이용을 가능하게 하고 있습니다. 프리미엄 브랜드들은 탄소 중립 실적을 확보하기 위해 바이오 폴리머의 비용 프리미엄을 40-60% 부담하고 있습니다. 한편, 접착제 공급업체들은 싱글 스트림 재활용에 대응 가능한 수성 및 핫멜트 시스템으로 전환하고 있습니다. 재활용을 고려한 설계(Design-for-Recycling) 소프트웨어는 개발 단계에서 제품 수명 종료 시나리오를 시뮬레이션하여 실물 시제품 제작을 줄이는 동시에 규정 준수 대응을 신속하게 처리합니다.
전자상거래 및 국경을 넘는 무역 흐름의 확대
2025년, 크로스보더 전자상거래 시장 규모는 1조 2,000억 달러를 돌파할 전망이며, ISO 668을 준수하는 골판지 상자와 컨테이너 이용률을 극대화하는 접이식 IBC에 대한 수요가 증가하고 있습니다. 동남아시아와 중동의 제3자 물류 제공업체들은 15-25%의 화물 추가 요금을 피하기 위해 포장 치수를 표준화하고 있습니다. 아마존의 ‘프러스트레이션 프리(Frustration-Free)’ 지침은 화학제품 유통 분야로도 파급되어, 2차 포장을 배제하고 포장 중량을 8-12% 줄이는 스틸 드럼의 재설계를 촉진하고 있습니다. 소비자에게 직접 판매하는 영양 보충제 브랜드들은 과잉 재고를 쌓지 않으면서도 분할 주문을 발송할 수 있도록 20-50리터 용량의 드럼을 선택하고 있습니다. 지역 무역 협정으로 관세 장벽이 제거됨에 따라, 여러 운송 규격을 충족하는 유엔 인증 IBC에 대한 수요가 증가하고 있습니다.
변동이 심한 수지 및 철강 가격
2024년부터 2025년에 걸쳐 HDPE 현물 가격은 톤당 1,100-1,450달러 사이에서 변동했고, 열간 압연 코일은 톤당 650-950달러로 크게 요동쳤기 때문에가공업체의 이익률은 압박을 받았습니다. Greif에서는 사내 컴파운딩을 통해 폴리프로필렌 수요의 40%를 충당하게 되어, 가격 급등에 대한 완충 역할을 하고 있습니다. 헤지 수단이 없는 소규모 사업자들은 60-90일간의 가격 전가 지연에 직면하여 현금 흐름에 부담이 가중되면서, 범용 드럼 시장에서의 철수가 가속화되고 있습니다. 고객들은 분기별 조정 상한선이 설정된 지수 연동형 계약을 제공하는 공급업체를 점점 더 선호하는 추세이며, 예측 가능성을 대가로 약간 높은 기본 가격을 수용하고 있습니다. 또한, 가격 변동성이 심해짐에 따라 변환업체들은 석유화학 통합 기업과 다년간의 수지 공급 계약을 체결하는 쪽으로 기울고 있습니다.
부문별 분석
IBC는 일회용 라이너 덕분에 세척 주기가 필요 없으며, 무균 상태를 유지하면서도 유엔의 성능 시험 기준을 충족하기 때문에 연평균 성장률(CAGR) 6.11%로 성장하여 산업용 포장 시장 전체를 상회할 것으로 예측됩니다. 드럼은 2025년에 산업용 포장 시장 점유율의 35.53%를 차지했으나, 인력이 많이 소요되는 취급 작업과 수작업으로 기울일 때 발생하는 1-2%의 누출로 인해 성장이 둔화될 것으로 예측됩니다. 탄소섬유 복합재로 제작된 IBC는 무게를 40-50% 줄여, 수소 운송 시 운송 비용을 0.15-0.20달러/t-km 절감합니다. 감마선 살균 라이너가 장착된 플렉서블 IBC는 바이오 의약품의 배치 전환 시간을 8시간에서 30분으로 단축하여 자산 가동률을 4분의 1 향상시킵니다. 자동차용 윤활유 공급업체가 200리터 드럼통에서 1,000리터 적층형 IBC로 전환함으로써 창고 공간을 35% 확보하고, 단위당 지게차 작업 시간을 4분에서 90초로 단축하고 있습니다.
틈새 시장의 용기는 여전히 특수한 용도에서 자리 잡고 있습니다. 분말 형태의 화학약품이나 건설용 첨가제 분야에서는 25-50kg 포장이 노동 기준을 충족하기 때문에 봉지가 주류를 이루고 있습니다. 페일 통은 접착제나 특수 주문형 코팅제에 사용되며, 골판지로 만든 ‘백 인 박스(Bag-in-Box)’ 하이브리드 용기는 섬유의 재활용성과 폴리에틸렌의 차단성을 결합하여 액체 농축액 운송에 활용되고 있습니다. 측벽을 접을 수 있는 반경질 IBC는 비어 있을 때의 부피를 60-70% 줄이면서도, 충전 시에는 3단까지 적재할 수 있습니다. 유엔의 낙하 시험 및 수압 시험 기준에서는 여전히 위험물에 대해 경질 포장을 권장하고 있지만, 더 두꺼운 다층 필름을 통해 유연한 설계에서도 규제 적합성 격차가 점차 해소되고 있습니다.
소매업체의 회수 프로그램과 소비자의 참여를 용이하게 하는 지자체별 가정별 수거 제도의 지원에 힘입어, 섬유계 포장은 연평균 성장률(CAGR) 6.75%로 성장할 전망입니다. 2025년,HDPE의 내화학성(1.20-1.40달러/kg) 덕분에 플라스틱은 산업용 포장 시장 규모의 46.44%를 차지했으나, 0.10-0.25달러/kg의 확대된 생산자책임(EPR) 수수료가 그 우위를 약화시키고 있습니다. Mondi의 크라프트지 IBC 라이너는 플라스틱 필름을 사용하지 않고도 방습성 테스트를 통과하여, 섬유 회수 과정에서 발생하는 선별상의 장벽을 제거하고 있습니다. 사탕수수 유래 폴리에틸렌은 제조 단계까지의 탄소 발자국을 60-70% 줄여, 고급 퍼스널케어 제품의 리필 용품에서 30-40%의 가격 프리미엄을 정당화하고 있습니다. 금속 용기는 가연성 또는 천공 위험이 있는 화물 시장에서 틈새 시장을 유지하고 있지만, 재생강 함유율이 80%를 초과하고 전기 아크로가 채택됨에 따라 내재된 탄소량이 절반으로 줄었습니다. 알루미늄과 섬유를 결합한 하이브리드 IBC는 사용 종료 시 기계적 분리가 가능하여 재활용률을 높입니다.
접착제의 혁신이 이러한 전환을 가속화하고 있습니다. 수성 시스템은 펄프 제조 공정에서 깨끗하게 박리되므로, 과거 재생 섬유를 괴롭혔던 점착성 오염을 피할 수 있습니다. 고객이 조달처 및 가공 조건의 추적 가능성을 요구하게 됨에 따라, ISO 9001 인증을 획득한 공급망이 현재 의약품 및 식품 등급 주문을 주도하고 있습니다. Mauser의 화학적 재활용 제품은 고순도 재생 HDPE 드럼의 생산을 가능하게 하여, 위험물 용도에서의 순환형 생산 능력을 확대되고 있습니다. 재활용 흐름을 통합한 기존 시장 기업들은 브랜드 소유주로부터 지지를 얻는 반면, 대응이 늦어진 기업들은 치솟는 환경 조정료를 지불해야 할 위험에 직면해 있습니다.
지역별 분석
2025년, 아시아태평양은 산업용 포장 시장의 40.45%를 차지했습니다. 이는 중국의 화학제품 생산량이 15억 톤을 초과하고, 인도의 농약 수출액이 80억 달러에 달한 것이 원동력이 되었습니다. 롄클라우드항 등 중국의 연안 메가사이트에서는 도로 병목 현상을 피할 수 있는 철도 대응형 IBC가 현재 선호되고 있습니다. 한편, 인도의 농약 생산 지대에서는 유해한 살충제 용기로 유엔 인증 HDPE 드럼으로의 전환이 진행되고 있습니다. 일본에서는 노동력 고령화에 따라 코봇 도입이 가속화되고 있으며, 팔레타이징 속도는 시간당 50드럼에 달하고, 인건비를 60-70% 절감하고 있습니다. 한국에서는 ‘수소 경제 로드맵’에 따라 수입 터미널에서 내륙 공급 거점으로 메틸시클로헥산이 운송되는 과정에서 복합재 IBC 수요가 촉진되고 있습니다. 동남아시아의 물류 기업들은 항만 체류 시간을 단축하고 체선료를 절감하기 위해 ISO 규격의 팔레트 크기를 철저히 준수하고 있습니다.
북미에서는 출하량이 안정적이지만, 반도체 팹 및 전기자동차 조립 공장의 니어쇼어링 혜택을 받고 있습니다. 초고순도 화학약품용 IBC에는 칩 팹의 오염을 방지하기 위해 불소를 포함하지 않는 라미네이트 필름이 채택되고 있습니다. 멕시코의 마키라도라 집적지에서는 폐기되기까지 30-40회 국경을 넘는 재사용 가능한 플라스틱 토트가 활용되어, 골판지 폐기물이 줄어들고 있습니다. 캐나다의 오일샌드 사업에서는 시추용 첨가제를 취급하기 위해 -40°C에서도 사용 가능한 탄소강 드럼을 구입하고 있습니다. 캘리포니아주 등 미국 각 주에서는 재활용 소재 함유율에 관한 규제가 적용되고 있어, 이에 따라 각 컨버터 기업들은 r-HDPE 드럼으로의 전환을 강요받고 있습니다. 한편, 동부 해안 항구에서는 화학제품 수출 흐름을 뒷받침하기 위해 드럼 세척 설비에 대한 투자가 진행되고 있습니다.
중동 및 아프리카은 연평균 성장률(CAGR) 7.14%를 나타낼 것으로 전망되며, 가장 빠른 성장 궤도를 그리고 있습니다. 사우디아라비아의 200억 달러 규모 ‘비전 2030’에 따른 석유화학 플랜트 확장 계획은 부식성 중간체에 대응하는 복합재 IBC 컨테이너에 대한 수요를 견인하고 있습니다. 아랍에미리트(UAE)의 자유무역지대는 아시아 제조업체와 아프리카 광산 회사를 연결하는 컨테이너 환적 허브 역할을 하며, 탱크 세척 및 드럼 재생 처리 시설에 대한 투자를 촉진하고 있습니다. 남아프리카의 광업 부문에서는 목재 크레이트에서 RFID 태그가 부착된 UN 규격의 스틸 드럼으로의 전환이 진행되어 추적성이 향상되고 있습니다. 나이지리아의 소비자용 석유 생산 업체들은 수입 드럼을 국내산 골판지 및 섬유 기반 벌크 팩으로 대체하여 외화를 국내에 유보하고 있습니다. 사우디아라비아의 ‘NEOM’ 계획과 관련된 수소 시범 사업은 암모니아 및 액체 유기 수소 운송 용기의 초기 도입자를 창출하고 있으며, 복합재 IBC에 대한 지역적 수요 증가를 예고하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the industrial packaging market size is projected to be USD 70.99 billion in 2025, USD 74.35 billion in 2026, and reach USD 97.53 billion by 2031, growing at a CAGR of 5.58% from 2026 to 2031.
This report is Segmented by Product Type (IBCs, Drums, Sacks, Pails, Corrugated Boxes, and More), Material Type (Plastics, Metal, Paper and Fiber-Based, and More), Packaging Capacity (<=50L, 51-500L, 501-1, 000L, and More), Packaging Format (Rigid, and Flexible), End-User Industry (Chemicals and Pharmaceuticals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Packaging Market Trends and Insights
Emergence of Sustainable and Recyclable Materials
Regulators are mandating minimum recycled-content thresholds and full recyclability, compelling converters to shift away from virgin resin. Mondi's 2025 paper-based IBC liner eliminates the polyethylene inner bag yet achieves moisture-vapor transmission below 5 g/m2-day, validating fiber substrates for food-grade use. Mauser Packaging Solutions now runs depolymerization lines that convert contaminated HDPE drums into virgin-equivalent pellets, enabling circular use in hazardous-goods containers. Premium brands absorb 40-60% cost premiums on bio-polymers to secure carbon-neutral credentials, while adhesive suppliers switch to water-based and hot-melt systems that remain compatible with single-stream recycling. Design-for-recycling software simulates end-of-life scenarios during development, cutting physical prototyping and speeding compliance.
Expansion of E-Commerce and Cross-Border Trade Flows
Cross-border e-commerce surpassed USD 1.2 trillion in 2025, lifting demand for ISO 668-compliant corrugated boxes and collapsible IBCs that maximize container utilization. Third-party logistics providers in Southeast Asia and the Middle East standardize packaging dimensions to avoid freight surcharges of 15-25%. Amazon's frustration-free guidelines ripple into chemical distribution, prompting steel-drum redesigns that strip secondary overwraps and cut package weight 8-12%. Direct-to-consumer nutraceutical brands choose 20-50 liter drums so they can ship split orders without bloating inventory. Regional trade pacts remove tariff friction, amplifying demand for UN-certified IBCs that satisfy multiple transport codes.
Volatile Resin and Steel Prices
HDPE spot prices oscillated between USD 1,100 and USD 1,450 t in 2024-2025, while hot-rolled coil swung from USD 650 to USD 950 t, crushing converter margins. Greif's in-house compounding now covers 40% of polypropylene needs, buffering against price spikes. Small players lacking hedges face 60-90-day pass-through lags that strain cash flow, accelerating exits from commodity drum markets. Customers increasingly favor suppliers offering index-linked contracts that cap quarterly adjustments, accepting slightly higher base prices in exchange for predictability. Volatility also nudges converters toward multi-year resin agreements with integrated petrochemical partners.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Food-Grade and Pharma Bulk Logistics
- On-Site Packaging Automation Adoption
- Tightening Global Environmental Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IBCs are forecast to grow at a 6.11% CAGR, outstripping the wider industrial packaging market, because single-use liners erase cleaning cycles and preserve sterility while meeting UN performance tests. Drums held 35.53% of the industrial packaging market share in 2025 but face slower growth due to labor-intensive handling and 1-2% spillage during manual tipping. Carbon-fiber composite IBCs slice weight 40-50%, lowering transport costs by USD 0.15-0.20/t-km for hydrogen carriers. Flexible IBCs with gamma-sterile liners cut biopharma batch changeover from eight hours to half an hour, lifting asset utilization by a quarter. Automotive lubricant suppliers upgrading from 200-liter drums to 1,000-liter stackable IBCs reclaim 35% warehouse space and reduce forklift time per unit from four minutes to ninety seconds.
Niche formats persist in specialized roles. Sacks dominate powdered chemicals and construction additives, where 25-50 kg packages align with labor codes. Pails address adhesives and bespoke coatings, and corrugated bag-in-box hybrids merge fiber recyclability with polyethylene barriers for liquid concentrates. Semi-rigid IBCs with collapsible sidewalls reduce empty volume 60-70% yet stack three-high filled. UN drop- and hydro-pressure criteria still favor rigid packages in hazardous goods, but thicker multilayer films are closing the compliance gap for flexible designs.
Fiber-based packs are set to rise at a 6.75% CAGR, supported by retailer take-back schemes and municipal curbside collection that simplify consumer participation. Plastics retained 46.44% of the industrial packaging market size in 2025 thanks to HDPE's chemical resistance at USD 1.20-1.40/kg, but extended producer responsibility fees of USD 0.10-0.25/kg erode that edge. Mondi's kraft IBC liners pass moisture-barrier tests without plastic films, removing sorting hurdles in fiber recovery. Sugarcane-based polyethylene slashes cradle-to-gate carbon 60-70%, justifying 30-40% premiums in premium personal-care refills. Metal containers keep niches in flammable or puncture-risk cargo, but recycled steel content above 80% and electric-arc furnaces cut embodied carbon by half. Hybrid aluminum-in-fiber IBCs allow mechanical separation at end-of-life, boosting recycling.
Adhesive innovation accelerates the shift. Water-based systems detach cleanly in pulpers, avoiding stickie contamination that once plagued recovered fiber. ISO 9001 certified supply chains now dominate pharmaceutical and food-grade orders, as customers require traceable sourcing and processing conditions. Mauser's chemical-recycling outputs enable high-purity r-HDPE drums, widening circular capacity for hazardous-goods applications. Market incumbents that integrate recycling streams gain brand-owner loyalty, while laggards risk paying escalating eco-modulation fees.
Complete Report Scope:
- By Product Type
- Intermediate Bulk Containers (IBCs)
- Drums
- Sacks
- Pails
- Corrugated Boxes
- Other Product Types
- By Material Type
- Plastics
- Metal
- Paper and Fiber-Based
- Other Material Types
- By Packaging Capacity
- <= 50 L
- 51 - 500 L
- 501 - 1,000 L
- 1,001 - 2,000 L
- > 2,000 L
- By Packaging Format
- Rigid Packaging
- Flexible Packaging
- By End-User Industry
- Chemicals and Pharmaceuticals
- Food and Beverage
- Automotive
- Oil, Gas and Petrochemicals
- Building and Construction
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific captured 40.45% of the industrial packaging market in 2025, propelled by China's chemical output above 1.5 billion t and India's agrochemical exports topping USD 8 billion. Chinese coastal megasites such as Lianyungang now favor rail-compatible IBCs that bypass road bottlenecks, while India's agrochemical belt upgrades to UN-approved HDPE drums for hazardous insecticides. Japan's aging workforce accelerates cobot adoption, with palletizing speeds reaching 50 drums an hour and cutting labor costs 60-70%. South Korea's Hydrogen Economy Roadmap stimulates composite IBC demand as methylcyclohexane flows from import terminals to inland dispensers. Southeast Asian logistics firms enforce ISO pallet footprints to shorten port dwell times and slice demurrage bills.
North America shows steady volume but benefits from near-shoring of semiconductor fabs and electric-vehicle assembly. Ultrapure chemical IBCs integrate fluorine-free laminate films to avoid chip-fab contamination. Mexico's maquiladora clusters rely on reusable plastic totes that cross borders 30-40 times before retirement, shrinking corrugated waste. Canadian oil-sands operations purchase carbon-steel drums rated for -40 °C service to handle drilling additives. U.S. states like California apply recycled-content rules that push converters toward r-HDPE drums, while East Coast ports invest in drum-washing capacity to support chemical export flows.
The Middle East and Africa offer the fastest trajectory, with a 7.14% CAGR outlook. Saudi Arabia's USD 20 billion Vision 2030 petrochemical build-out drives demand for composite IBCs rated for corrosive intermediates. UAE free zones serve as container trans-shipment hubs bridging Asian manufacturers and African miners, spurring investments in tank-cleaning and drum-reconditioning yards. South Africa's mining sector swaps wooden crates for RFID-tagged UN steel drums, improving traceability. Nigeria's consumer-oil producers substitute imported drums with domestic corrugated and fiber-based bulk packs, retaining forex. Hydrogen pilots tied to Saudi Arabia's NEOM plan create early adopters for ammonia and liquid organic hydrogen carriers, foreshadowing regional capacity for composite IBCs.
- Greif, Inc.
- Mauser Packaging Solutions Holding Company
- Mondi plc
- Smurfit WestRock
- Amcor plc
- International Paper Company
- Packaging Corporation of America
- Schutz GmbH & Co. KGaA
- WERIT Kunststoffwerke W. Schneider GmbH & Co. KG
- Tank Holding Corp.
- Visy Industries Holdings Pty Ltd
- Pact Group Holdings Ltd
- Brambles Limited (CHEP)
- Global-Pak, Inc.
- Nefab AB
- Snyder Industries, LLC
- Myers Container, LLC
- Pyramid Technoplast Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Emergence of Sustainable and Recyclable Materials
- 4.2.2 Expansion of E-Commerce and Cross-Border Trade Flows
- 4.2.3 Growth in Food-Grade and Pharma Bulk Logistics
- 4.2.4 On-Site Packaging Automation Adoption
- 4.2.5 Hydrogen-Supply Chain Demand for Composite IBCs
- 4.2.6 Rise of Reusable Packaging Pool Business Models
- 4.3 Market Restraints
- 4.3.1 Volatile Resin and Steel Prices
- 4.3.2 Tightening Global Environmental Regulations
- 4.3.3 PFAS and Micro-Plastic Bans on Barrier Coatings
- 4.3.4 Near-Shoring Lowering Long-Haul Packaging Volumes
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Intermediate Bulk Containers (IBCs)
- 5.1.2 Drums
- 5.1.3 Sacks
- 5.1.4 Pails
- 5.1.5 Corrugated Boxes
- 5.1.6 Other Product Types
- 5.2 By Material Type
- 5.2.1 Plastics
- 5.2.2 Metal
- 5.2.3 Paper and Fiber-Based
- 5.2.4 Other Material Types
- 5.3 By Packaging Capacity
- 5.3.1 <= 50 L
- 5.3.2 51 - 500 L
- 5.3.3 501 - 1,000 L
- 5.3.4 1,001 - 2,000 L
- 5.3.5 > 2,000 L
- 5.4 By Packaging Format
- 5.4.1 Rigid Packaging
- 5.4.2 Flexible Packaging
- 5.5 By End-User Industry
- 5.5.1 Chemicals and Pharmaceuticals
- 5.5.2 Food and Beverage
- 5.5.3 Automotive
- 5.5.4 Oil, Gas and Petrochemicals
- 5.5.5 Building and Construction
- 5.5.6 Other End-User Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Italy
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 Australia
- 5.6.4.5 South Korea
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Kenya
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Greif, Inc.
- 6.4.2 Mauser Packaging Solutions Holding Company
- 6.4.3 Mondi plc
- 6.4.4 Smurfit WestRock
- 6.4.5 Amcor plc
- 6.4.6 International Paper Company
- 6.4.7 Packaging Corporation of America
- 6.4.8 Schutz GmbH & Co. KGaA
- 6.4.9 WERIT Kunststoffwerke W. Schneider GmbH & Co. KG
- 6.4.10 Tank Holding Corp.
- 6.4.11 Visy Industries Holdings Pty Ltd
- 6.4.12 Pact Group Holdings Ltd
- 6.4.13 Brambles Limited (CHEP)
- 6.4.14 Global-Pak, Inc.
- 6.4.15 Nefab AB
- 6.4.16 Snyder Industries, LLC
- 6.4.17 Myers Container, LLC
- 6.4.19 Pyramid Technoplast Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment