

|
시장보고서
상품코드
2121834
내열 코팅 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Heat-Resistant Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
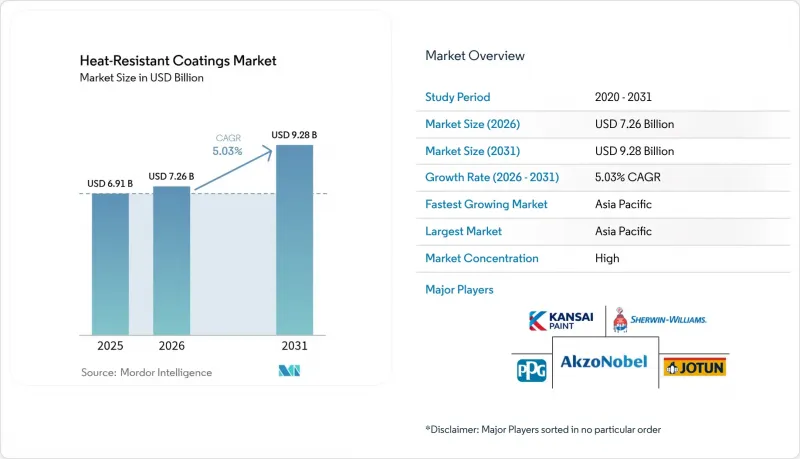
에 의하면, 내열 코팅 시장 규모는 2025년 69억 1,000만 달러에서 2026년에는 72억 6,000만 달러에 이르고, 2026-2031년 CAGR 5.03%로 성장을 지속하여 2031년에는 92억 8,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 수지별(실리콘, 에폭시, 아크릴, 기타 수지), 기술별(용제형, 수성, 분체, UV/EB 경화형), 최종 사용자 산업(건축 및 건설, 석유 및 가스,전력, 운송, 목공·가구, 소비재, 기타 최종 사용자 산업), 그리고 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
세계 내열 코팅 시장 동향 및 인사이트
전 세계 인프라 투자의 급증
각국 정부는 기후 변화에 대한 회복력과 도시 성장을 목표로 한 인프라 구축에 사상 최대 규모의 자금을 투입하고 있습니다. 미국의 ‘인프라 투자 및 고용법’에서는 코팅 사양에 영향을 미치는 에너지 기준 개정에 2억 2,500만 달러가 배정되었습니다. 아시아태평양의 신흥 경제국들도 이러한 추세를 가속화하고 있으며, 인도네시아, 인도, 중국에서는 고온 차단 필름을 사양으로 하는 공항, 교량, 스마트 시티 프로젝트가 가속화되고 있습니다. 교통 터널 및 지역 난방 공급 라인에서의 민관 파트너십을 통해 수명이 긴 내열 코팅에 대한 수요는 더욱 확대되고 있습니다.
전 세계 화재 방지 규제의 강화
방화 기준 개정에 따라 점화 저항성, 연기 독성 및 사용 시 표면 온도에 관한 최소 성능 기준이 상향 조정되었습니다. 『국제 방화 기준 2024』에서는 도료 배합에 즉각적인 영향을 미치는 개정된 화염 전파 기준이 도입되었습니다. 캘리포니아주 방화 기준 제24장에서는 내열 제품을 취급하는 도장 부스에 대해 자동 소화 시스템 및 전용 환기 설비의 설치를 의무화하고 있습니다. EU 지침에서는 허용되는 용제 함유량이 지속적으로 축소되고 있어, 건설업체들이 저VOC 실리콘·아크릴계 하이브리드 도료를 사용하도록 유도하고 있습니다. 고층 빌딩의 파사드 및 교통 허브의 개보수 공사로 인해, 소유주가 자산을 규정에 부합하도록 만들기 위해 수요가 급증하고 있습니다. 새로운 기준치를 상회하는 제품을 인증받은 제조업체는 사양 선정 시 우선적으로 고려되며, 비용이 많이 드는 수정 작업의 필요성을 줄일 수 있습니다.
실리콘 및 에폭시 가격 변동
미국 국제무역위원회의 판정에 따라 특정 에폭시 수지 수입품이 적정 가격보다 낮게 판매되고 있었던 사실이 밝혀지면서, 국내 공급이 부족해져 비용이 상승했습니다. 이와 동시에 아시아의 주요 실리콘 제조 공장에서 잇달아 가동 중단이 발생하면서 가격 변동이 더욱 심화되었습니다. 장기 계약을 체결하지 않은 중소 배합 제조업체들은 두 자릿수에 달하는 비용 급등에 직면하여 이익률이 압박받았고, 제품 가격 조정을 불가피하게 되었습니다. 생산자들은 전구체의 조달처를 다각화하거나 자사 내 모노머 생산 능력을 확대하는 등 리스크 헤지를 도모하고 있으나, 설비 투자로 인해 즉각적인 개선은 지연되고 있습니다. 원자재 가격 변동은 주기적인 현상이지만, 단기적으로는 현금 흐름을 압박하고 연구개발비 지출을 저해합니다.
부문별 분석
실리콘 수지는 2025년 내열 코팅 시장 점유율의 37.45%를 차지하고 있으며, 이는 600°C를 넘는 온도에서도 접착력을 잃지 않고 견딜 수 있다는 이 화학 물질의 특성을 반영합니다. 이러한 선도적 지위는 2031년까지 부문별 연평균 성장률(CAGR)이 8.78%로 가장 높다는 사실로도 입증되며, 실리콘은 내열 코팅 시장의 중요한 성장 동력이 되고 있습니다. 수요는 배기 스택, 플레어 스택, 베이킹 오븐, 그리고 고장이 허용되지 않는 항공우주 부품 등에 이릅니다. 에폭시 수지는 중온 영역에서 여전히 중요한 위치를 차지하고 있지만, 비용 측면의 역풍과 비스페놀 A 유도체에 대한 규제 당국의 엄격한 감시에 직면해 있습니다. 아크릴 수지는 표면 온도의 최고치가 비교적 낮은 소비재 분야에서 가격에 민감한 용도를 충족시키고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 47.12%를 차지하며 선두를 달리고 있으며, 운송, 주택, 에너지 분야의 메가 프로젝트를 원동력으로 연평균 성장률(CAGR) 7.35%로 확대되고 있습니다. 중국의 ‘일대일로’ 회랑에서는 산불이나 화학물질 유출 위험에 노출된 교량 및 터널을 위해 내열성 프라이머가 요구되고 있습니다. 인도는 ‘메이크 인 인디아’ 구상 아래, 열안정성 필름이 필수적인 조리용 가스레인지, 보일러, 산업용 오븐의 국내 생산을 확대되고 있습니다.
북미는 여전히 혁신의 중심지입니다. 미국 및 캐나다의 항공우주 대기업들은 MIL 규격에 부합하는 금속계 및 세라믹계 배리어 코팅을 지정하고 있습니다. 연방 정부의 인프라 투자로 노후화된 교량의 교체와 에너지 그리드 개선이 진행되고 있으며, 각 프로젝트에서는 저VOC이며 내열성이 높은 마감재 사용이 의무화되어 있습니다.
유럽에서는 지속가능성이 중시되고 있습니다. EU의 VOC 상한치는 해마다 강화되고 있으며, 건설업체에는 수성 실리콘 및 분체 도료의 채택이 권장되고 있습니다. 독일, 프랑스, 이탈리아의 자동차 플랫폼에는 열 조절을 위해 나노 구조의 세라믹 필름으로 코팅된 경량 금속 부품이 탑재되고 있습니다. 남미, 중동 및 아프리카 시장은 규모는 작지만, 기술 이전과 국제 안전 기준 채택의 혜택을 받고 있어 내열 도료의 잠재 시장 전체를 확대되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the heat-Resistant coatings market size is expected to grow from USD 6.91 billion in 2025 to USD 7.26 billion in 2026 and is forecast to reach USD 9.28 billion by 2031 at 5.03% CAGR over 2026-2031.
This report is Segmented by Resin (Silicone, Epoxy, Acrylic, Other Resins), Technology (Solvent-Borne, Water-Borne, Powder, UV/EB-curable), End-User Industry (Building and Construction, Oil and Gas, Power Sector, Transportation, Woodworking and Furniture, Consumer Goods, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa).
Global Heat-Resistant Coatings Market Trends and Insights
Surge in Global Infrastructure Spending
Governments are funding record levels of infrastructure aimed at climate resilience and urban growth. The United States Infrastructure Investment and Jobs Act earmarked USD 225 million for updated energy codes that influence coating specifications. Emerging Asia-Pacific economies add momentum as Indonesia, India, and China accelerate airport, bridge, and smart-city projects that specify high-temperature barrier films. Public-private partnerships in transport tunnels and district-heating lines further widen demand for long-cycle thermal coatings.
Stricter Global Fire-Safety Regulations
Fire-code revisions raise minimum performance thresholds for ignition resistance, smoke toxicity, and end-use surface temperature. The International Fire Code 2024 introduces updated flame-spread benchmarks that immediately affect coating formulations. California's Fire Code Chapter 24 mandates automatic extinguishing systems and specialized ventilation for coating booths handling heat-resistant products. EU directives continue to shrink allowed solvent content, pushing builders toward low-VOC silicone-acrylic hybrids. Retrofits of high-rise facades and transportation hubs create demand spikes as owners bring assets into compliance. Manufacturers that certify products above the new baseline win specification priority and reduce the need for costly rework.
Volatile Silicone and Epoxy Prices
A United States International Trade Commission ruling found certain epoxy imports were sold below fair value, tightening domestic supply and raising costs. Simultaneous outages in key Asian silicone plants amplified volatility. Smaller formulators lacking long-term contracts faced double-digit cost spikes that eroded margins and triggered product repricing. Producers hedge by dual-sourcing precursors and expanding in-house monomer capacity, but capital outlays delay immediate relief. Although raw-material swings are cyclical, they compress cash flow and hinder research and development spending in the short term.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand from the Aerospace Industry
- Rising Awareness Toward Fire Protection Equipment
- VOC Limits on Solvent-Borne Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone resins accounted for 37.45% of the 2025 heat-resistant coatings market share, reflecting the chemistry's ability to tolerate temperatures above 600 °C without losing adhesion. That leadership is matched by the fastest segment CAGR of 8.78% through 2031, making silicone the pivotal growth engine of the heat-resistant coatings market. Demand spans exhaust stacks, flare stacks, bake ovens, and aerospace parts where failure is unacceptable. Epoxies retain relevance in mid-temperature zones but face cost headwinds and regulatory scrutiny on bisphenol-A derivatives. Acrylics fill price-sensitive applications in consumer goods where surface temperature peaks are lower.
Complete Report Scope:
- By Resin
- Silicone
- Epoxy
- Acrylic
- Other Resins (Polyurethane, Alkyd, etc.)
- By Technology
- Solvent-borne
- Water-borne
- Powder
- UV/EB-curable
- By End-user Industry
- Building and Construction
- Oil and Gas
- Power Sector
- Transportation
- Woodworking and Furniture
- Consumer Goods
- Other End-user Industries (Industrial Processing Equipment, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific led with 47.12% of 2025 revenue and advances at 7.35% CAGR, powered by megaprojects in transport, housing, and energy. China's Belt and Road corridors require heat-resistant primers for bridges and tunnels exposed to wildfire and chemical spill risks. India, under its Make in India vision, expands domestic manufacturing of cookstoves, boilers, and industrial ovens that all specify heat-stable films.
North America remains an innovation center. Aerospace primes in the United States and Canada specify metallic and ceramic barrier coats qualified to MIL standards. Federal infrastructure outlays replace aging bridges and improve energy grids, each project mandating low-VOC, high-temperature finishes.
Europe emphasizes sustainability. EU VOC ceilings tighten yearly, pushing builders to waterborne silicones and powder options. Automotive platforms in Germany, France, and Italy integrate lightweight metal components coated with nano-structured ceramic films for thermal regulation. Markets in South America, the Middle East and Africa grow from a smaller base yet benefit from technology transfer and the adoption of international safety codes, widening the total addressable heat-resistant coatings market.
- 3M
- Advanced Industrial Coatings
- AkzoNobel N.V.
- Aremco
- Arkema
- Axalta Coating Systems LLC
- BASF
- Belzona International Ltd.
- Hempel A/S
- Jotun
- Kansai Paint Co. Ltd.
- KCC Corporation
- Momentive
- PPG Industries Inc.
- Teknos Group
- The Sherwin-Williams Company
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Global Infrastructure Spending
- 4.2.2 Stricter Global Fire-safety Regulations
- 4.2.3 Growing Demand from the Aerospace Industry
- 4.2.4 Rising Awareness Toward Fire Protection Equipment
- 4.2.5 Re-usable Spacecraft and Space-tourism Vehicles
- 4.3 Market Restraints
- 4.3.1 Volatile Silicone and Epoxy Prices
- 4.3.2 VOC Limits on Solvent-borne Systems
- 4.3.3 Applicator Skill Shortage for Multi-layer Systems
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin
- 5.1.1 Silicone
- 5.1.2 Epoxy
- 5.1.3 Acrylic
- 5.1.4 Other Resins (Polyurethane, Alkyd, etc.)
- 5.2 By Technology
- 5.2.1 Solvent-borne
- 5.2.2 Water-borne
- 5.2.3 Powder
- 5.2.4 UV/EB-curable
- 5.3 By End-user Industry
- 5.3.1 Building and Construction
- 5.3.2 Oil and Gas
- 5.3.3 Power Sector
- 5.3.4 Transportation
- 5.3.5 Woodworking and Furniture
- 5.3.6 Consumer Goods
- 5.3.7 Other End-user Industries (Industrial Processing Equipment, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Advanced Industrial Coatings
- 6.4.3 AkzoNobel N.V.
- 6.4.4 Aremco
- 6.4.5 Arkema
- 6.4.6 Axalta Coating Systems LLC
- 6.4.7 BASF
- 6.4.8 Belzona International Ltd.
- 6.4.9 Hempel A/S
- 6.4.10 Jotun
- 6.4.11 Kansai Paint Co. Ltd.
- 6.4.12 KCC Corporation
- 6.4.13 Momentive
- 6.4.14 PPG Industries Inc.
- 6.4.15 Teknos Group
- 6.4.16 The Sherwin-Williams Company
- 6.4.17 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


