

|
시장보고서
상품코드
2121915
니오븀 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Niobium - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
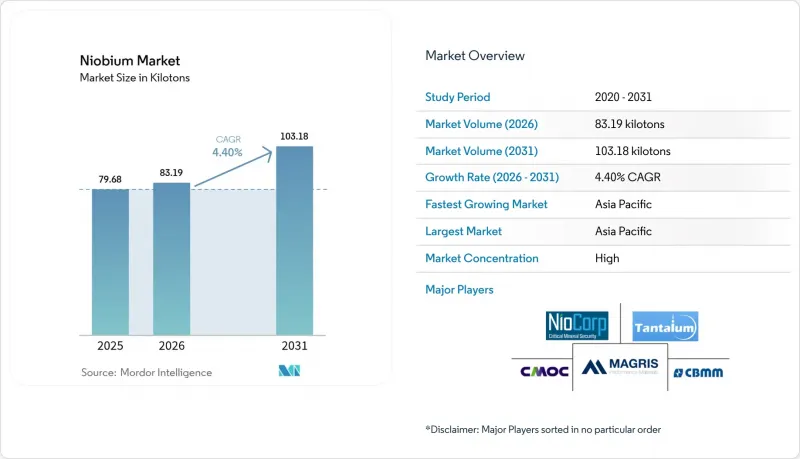
에 따르면 니오븀 시장 규모는 2025년 79.68 킬로톤에서 2026년에는 83.19 킬로톤으로 확대하며, 2026-2031년에 CAGR 4.4%로 추이하며, 2031년까지 103.18 킬로톤에 달할 것으로 예측됩니다.
이 보고서는 광물 상태(카보나타이트 및 관련 광물, 콜롬바이트·탄탈라이트), 유형(페로니오브, 산화니오브 등),용도(철강, 초합금, 초전도 자석 및 커패시터 등), 최종사용자 산업(건설, 자동차·조선, 항공우주·방위 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
세계 니오브 시장의 동향 및 인사이트
건설 업계에서의 고강도·고인장강(HSLA) 채택 확대
건축기준법 개정에 따라 내진성을 높이기 위해 더 높은 강도 대 중량비가 의무화되었습니다. 0.02-0.05%의 니오브를 함유한 고강도·고인장강(HSLA)은 기존 강종에 비해 20-30%의 강도 향상을 실현하는 동시에 필요한 강재 사용량을 줄여줍니다. 중국의 2024년판 내진 기준에서는 고층 건축 프로젝트를 위해 니오브 미량 합금강의 사용이 명시되어 있으며, 인도네시아와 멕시코에서도 유사한 개정이 검토되고 있습니다. 재료 비용의 추가 부담은 여전히 5-8%에 그치는 반면, 구조용 강재 사용량은 최대 20%까지 절감되므로, 엔지니어링 기업은 장기적인 인프라 계획에 니오브 사양을 반영하고 있습니다. 아시아와 아프리카에서 새로운 도시화 물결이 가속화되는 가운데, 건설 수요는 니오브 총 소비량의 49% 이상을 차지하며 니오브 시장의 안정적인 기반을 더욱 공고히 하고 있습니다. 규제 측면의 움직임에 따라 향후 10년 이내에 HSLA의 채택은 사실상 되돌릴 수 없는 추세가 될 것입니다.
자동차 및 조선 업계의 경량화 추진
더 엄격해진 연비 목표와 선박 배기가스 규제로 인해 적극적인 경량화 전략이 추진되고 있습니다. 니오브를 함유한 첨단 고강도 강재는 현재 프리미엄 부문 차량의 60% 이상에 채택되어 있으며, 각 OEM 업체들이 충돌 안전성과 배터리로 인한 중량 증가 간의 균형을 모색함에 따라 대중차용 플랫폼으로도 확대되고 있습니다. 조선 분야에서는 니오브를 첨가한 극저온용 HSLA 강판이 -162°C에서의 파괴 인성에 관한 LNG 운반선 요건을 충족하여, 한국과 카타르의 선단 갱신을 지원하고 있습니다. 상용 트럭 및 철도 차량 제조사들도 마찬가지로 니오브를 첨가한 빔과 섀시 부품을 채택하는 경향을 보이고 있으며, 대대적인 설계 변경 없이 적재 효율을 향상시키고 있습니다. 이러한 다양한 운송 수단을 아우르는 채택 사이클 덕분에, 니오브 시장은 단일 부문에 의존하지 않고 여러 산업에 걸쳐 시너지 효과를 창출하는 위치에 있습니다.
급성 노출로 인한 건강 및 환경 문제
니오브 광석에는 종종 토륨이나 우라늄이 공존하므로 채굴시 엄격한 방사선 감시가 필요합니다. 브라질 규제 당국은 현재 허가 갱신시 지하수 기준선 조사 및 동위원소 매핑을 의무화하고 있으며, 이로 인해 규정 준수 비용이 15-25% 증가하고 있습니다. 원주민 영토를 둘러싼 논란으로 인해 신규 개발 프로젝트의 승인이 더욱 지연되고 있으며, 캐나다의 ‘링 오브 파이어(Ring of Fire)’ 지역에서도 지역사회와의 관계에 관한 유사한 과제가 나타나고 있습니다. 산업 수준의 노출에서 만성 독성 사례는 보고된 바 없으나, 여론에 의한 위험이 설비 투자 결정에 영향을 미쳐 공급 측의 유연성을 저해할 가능성이 있습니다.
부문 분석
카보나타이트 광상은 2025년 세계 공급량의 95.85%를 차지하며, 2031년까지 연평균 성장률(CAGR) 4.43%로 확대될 전망이어서 니오브 시장 규모의 성장 궤도를 지원하고 있습니다. 브라질의 아라샤 광산은 스트립 비율이 낮고, 선광을 용이하게 하는 굵은 입자의 파이록로아를 생산하며, 경쟁력 있는 운영 비용 수준으로 페로니오브를 생산하고 있는 좋은 사례입니다.
현재 탐사 투자는 그린란드와 탄자니아 지반 아래에 매장된 카보나타이트를 목표로 하고 있지만, 아라샤 광산 규모에 필적하는 발견은 아직 없으며, 기존 공급 집중 경향이 더욱 강화되고 있습니다. 예측 가능한 광물 조성 및 수십년에 걸친 야금 노하우를 통해 안정적인 처리량이 확보되고 있으며, 이는 장기 공급 계약의 기반이 되어 니오브 시장의 가격 안정성을 공고히 하고 있습니다. 일본과 독일의 전략적 비축 기업은 합금 공장의 품질관리를 효율화할 수 있는 일관된 불순물 프로파일 덕분에 계속해서 카보나타이트 원료를 선호하고 있습니다.
2025년 출하량의 92.75%를 페로니오브가 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 4.35%를 기록할 것으로 예측됩니다. 이는 전 세계 조강 수요 동향을 반영한 것입니다. 일반적으로 65%의 니오브를 함유한 마스터 합금은 기본 산소 용광로 공정에 원활하게 통합되어, 용해 공장 기술자가 결정립 크기나 석출 동태를 미세 조정할 수 있게 해줍니다. 산화 니오브는 현재 시장 점유율이 작지만, 배터리 및 유전체 세라믹에 대한 적용 확대에 힘입어 수요가 증가하고 있습니다. CBMM사의 산화 니오브 전용 생산 라인은 2030년까지 연간 4만 톤의 생산 능력을 목표로 하고 있습니다.
진공 등급의 금속 및 특수 합금 분말은 항공우주용 엔진, MRI용 자석, 양자 소자 등에 사용되고 있으며, 취급량은 적지만 높은 단가를 유지하고 있습니다. 적층 제조의 보급에 따라 구형 C-103 분말의 수요는 벌크 판재나 봉재의 수요를 초과할 가능성이 높으며, 이는 가공 업체의 수입원 다변화로 이어질 것으로 전망됩니다. 그 결과, 페로니오브는 계속해서 판매량의 주류를 차지하겠지만, 고순도 파생 제품이 니오브 업계 전체의 이익률 동향을 좌우하게 될 것입니다.
지역별 분석
아시아태평양은 2025년 전 세계 총 출하량의 60.10%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 4.71%로 성장하여 니오브 시장에서 가장 큰 지역 점유율을 확보할 것으로 예측됩니다. 중국의 막대한 철강 생산량과 진화하는 내진 기준이 대량 수요를 지원하는 한편, 니오브-실리콘 합금을 활용하는 항공우주 프로그램으로 인해 차세대 추진 시스템에 대한 채택이 확대되고 있습니다.
북미의 성장은 운송 차량의 탈탄소화와 국방 주도의 초음속 기술 개발이라는 두 가지 주제에 달려 있습니다. EPA(미국 환경보호청)의 연비 규제 강화와 주 차원의 제로 배출 의무화로 인해 OEM 기업은 무게가 증가하는 배터리 시스템의 균형을 맞추기 위해 섀시 경량화를 목적으로 니오브를 풍부하게 함유한 강재의 채택을 강요받고 있습니다. 캐나다의 니오벡 광산은 세계 생산량의 약 8-10%를 공급하고 있지만, 미국의 정책 입안자들은 브라질산 수입에 대한 의존도를 낮추기 위한 전략적 과제로 엘크 크릭을 통한 공급원 다각화를 계속해서 중시하고 있습니다.
유럽에서는 니오브 미량 합금 처리된 API X70 등급이 필요한 수소 파이프라인 확장을 통해 탄소 중립 목표 달성을 목표로 하고 있으며, 자동차 CO₂ 배출 규제의 강화로 인해 자동차용 프레스 부품에 고장력강의 채택이 지속되고 있습니다. 독일의 자동차 산업 클러스터에서는 페로니오브를 첨가함으로써 더욱 경량화된 화이트 바디 어셈블리를 실현하고 있습니다. 한편, 노르웨이의 광물 전략에서는 개정된 허가 규정에 따라 국내 탐사의 우선 대상으로 니오브가 꼽히고 있습니다. 또한 이 지역에서는 CERN의 가속기 업그레이드를 위한 니오브·주석 초전도체에 관한 기초 연구도 지원되고 있으며, 광범위한 니오브 시장 속에서 연구 주도형 틈새 시장이 유지되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the niobium market size is expected to grow from 79.68 kilotons in 2025 to 83.19 kilotons in 2026 and is forecast to reach 103.18 kilotons by 2031 at 4.4% CAGR over 2026-2031.
This report is Segmented by Occurrence (Carbonatites and Associates and Columbite-Tantalite), Type (Ferroniobium, Niobium Oxide, and More), Application (Steel, Super-Alloys, Superconducting Magnets and Capacitors, and More), End-User Industry (Construction, Automotive and Shipbuilding, Aerospace and Defense, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa).
Global Niobium Market Trends and Insights
Rising HSLA Steel Adoption in Construction
Building-code revisions now mandate higher strength-to-weight ratios for seismic resilience, and HSLA steels containing 0.02-0.05% niobium deliver 20-30% strength gains over conventional grades while cutting tonnage requirements. China's 2024 seismic standards explicitly cite niobium-microalloyed steels for high-rise projects, and similar updates are under review in Indonesia and Mexico. Because material cost premiums remain 5-8% yet structural steel volumes fall by up to 20%, engineering firms are embedding niobium specifications across long-term infrastructure plans. As new urbanization waves in Asia and Africa accelerate, construction demand anchors more than 49% of overall niobium consumption, reinforcing a stable baseline for the niobium market. Regulatory momentum makes HSLA adoption essentially irreversible within a decade horizon.
Lightweighting Push in Automotive and Shipbuilding
Stricter fuel-economy targets and maritime emission limits foster aggressive mass-reduction strategies. Advanced high-strength steels incorporating niobium now appear in over 60% of premium-segment vehicles and are migrating into mass-market platforms as OEMs balance crashworthiness with battery-induced weight penalties. In shipbuilding, cryogenic-grade HSLA plate with niobium additions satisfies LNG-carrier requirements for fracture toughness at -162 °C, supporting fleet renewal across South Korea and Qatar. Commercial trucking and railcar builders likewise gravitate toward niobium-enhanced beam and chassis components, improving payload efficiency without major design overhauls. The cross-modal adoption cycle positions the niobium market for multi-industry synergies rather than single-sector dependency.
Acute-exposure Health and Environmental Concerns
Niobium ores often coexist with thorium and uranium, necessitating strict radiological surveillance during mining. Regulatory authorities in Brazil now require groundwater baselines and isotopic mapping before license renewals, adding 15-25% to compliance costs. Indigenous-territory debates further delay greenfield approvals, and similar community-engagement hurdles appear in Canada's Ring of Fire region. While no chronic-toxicity cases have been documented at industrial exposure levels, public perception risks can influence capex decisions, tempering supply-side agility.
Other drivers and restraints analyzed in the detailed report include:
- Pipeline Build-out for Hydrogen and LNG Transmission
- Niobium-doped Li-ion Batteries Scale-up
- ESG Traceability Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Carbonatite-hosted deposits held 95.85% of the 2025 global supply and are set to expand at a 4.43% CAGR through 2031, underpinning the niobium market size growth trajectory. Brazil's Araxa mine exemplifies low-strip ratios and coarse-grained pyrochlore that simplify beneficiation, yielding ferroniobium at competitive opex levels.
Exploration spending now targets undercover carbonatites in Greenland and Tanzania; however, no discovery approaches Araxa's scale, reinforcing existing supply concentration. Predictable mineralogy and decades of metallurgical know-how translate into steady throughput, anchoring long-term delivery contracts and reinforcing the niobium market's pricing stability. Strategic stockpilers in Japan and Germany continue to favor carbonatite feed due to consistent impurity profiles that streamline alloy-shop quality control.
Ferroniobium accounted for 92.75% of 2025 shipments and is forecast to post a 4.35% CAGR through 2031, mirroring global crude-steel demand patterns. The master alloy, usually containing 65% niobium, integrates seamlessly into basic-oxygen furnace practices, enabling melt-shop engineers to fine-tune grain size and precipitation kinetics. Niobium oxide, while representing a minor share today, is pacing up on the back of battery and dielectric-ceramic uptake; CBMM's dedicated oxide line targets 40,000 tons annual capacity by 2030.
Vacuum-grade metal and specialty alloy powders feed aerospace engines, MRI magnets, and quantum devices, commanding premium unit values in spite of small tonnages. As additive manufacturing spreads, demand for spherical C-103 powder is likely to outpace bulk plate and bar, diversifying revenue streams for converters. Consequently, ferroniobium will remain the volume anchor, but high-purity derivatives will shape margin dynamics across the niobium industry.
Complete Report Scope:
- By Occurrence
- Carbonatites and Associates
- Columbite-Tantalite
- By Type
- Ferroniobium
- Niobium Oxide
- Niobium Metal
- Vacuum-grade Nb Alloys
- By Application
- Steel
- Super-alloys
- Superconducting Magnets and Capacitors
- Batteries
- Other Applications
- By End-user Industry
- Construction
- Automotive and Shipbuilding
- Aerospace and Defense
- Oil and Gas
- Other End-users
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Russia
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 60.10% of 2025 global volume and is forecast to grow at a 4.71% CAGR to 2031, securing the largest regional slice of the niobium market. China's gargantuan steel output and evolving seismic codes sustain bulk demand, while aerospace programs exploring niobium-silicon alloys extend uptake into next-generation propulsion systems.
North America's growth hinges on dual themes: decarbonization of transport fleets and defense-driven hypersonic development. Tightened EPA fuel-economy rules and state-level zero-emission mandates push OEMs toward niobium-enriched steels for chassis mass reduction, counterbalancing heavier battery systems. Canada's Niobec mine supplies roughly 8-10% of global output, but U.S. policymakers continue to view diversification via Elk Creek as a strategic imperative to curb reliance on Brazilian imports.
Europe targets net-zero targets by expanding hydrogen pipelines that demand niobium-microalloyed API X70 grades, and stringent vehicle CO2 limits sustain high-strength steel penetration in automotive stamping. Germany's auto clusters integrate ferroniobium additions to deliver lighter body-in-white assemblies, while Norway's mineral strategy lists niobium as a priority for domestic exploration under revised permitting rules. The region also supports fundamental research into niobium-tin superconductors for CERN's accelerator upgrades, sustaining a research-driven niche inside the broader niobium market.
- Admat Inc.
- American Elements
- Australian Strategic Materials Ltd
- CBMM
- Changsha South Tantalum Niobium Co. Ltd
- CMOC
- Grandview Materials
- Magris Performance Materials
- NioCorp Development Ltd
- Titanex GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising HSLA Steel Adoption in Construction
- 4.2.2 Lightweighting Push in Automotive and Shipbuilding
- 4.2.3 Pipeline Build-Out for Hydrogen and LNG Transmission
- 4.2.4 Niobium-Doped Li-Ion Batteries Scale-Up
- 4.2.5 Additive-Manufactured Nb Alloys for Aerospace
- 4.3 Market Restraints
- 4.3.1 Supply Concentration in Brazil and Pricing Power
- 4.3.2 Acute-Exposure Health and Environmental Concerns
- 4.3.3 ESG Traceability Compliance Costs
- 4.4 Porter's Five Forces
- 4.4.1 Bargaining Power of Suppliers
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Threat of New Entrants
- 4.4.4 Threat of Substitutes
- 4.4.5 Degree of Competition
- 4.5 Technological Snapshot/ Production Analysis
- 4.6 Price Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Occurrence
- 5.1.1 Carbonatites and Associates
- 5.1.2 Columbite-Tantalite
- 5.2 By Type
- 5.2.1 Ferroniobium
- 5.2.2 Niobium Oxide
- 5.2.3 Niobium Metal
- 5.2.4 Vacuum-grade Nb Alloys
- 5.3 By Application
- 5.3.1 Steel
- 5.3.2 Super-alloys
- 5.3.3 Superconducting Magnets and Capacitors
- 5.3.4 Batteries
- 5.3.5 Other Applications
- 5.4 By End-user Industry
- 5.4.1 Construction
- 5.4.2 Automotive and Shipbuilding
- 5.4.3 Aerospace and Defense
- 5.4.4 Oil and Gas
- 5.4.5 Other End-users
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Russia
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Admat Inc.
- 6.4.2 American Elements
- 6.4.3 Australian Strategic Materials Ltd
- 6.4.4 CBMM
- 6.4.5 Changsha South Tantalum Niobium Co. Ltd
- 6.4.6 CMOC
- 6.4.7 Grandview Materials
- 6.4.8 Magris Performance Materials
- 6.4.9 NioCorp Development Ltd
- 6.4.10 Titanex GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


