

|
시장보고서
상품코드
2121926
자동차용 공압 액추에이터 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Pneumatic Actuators - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
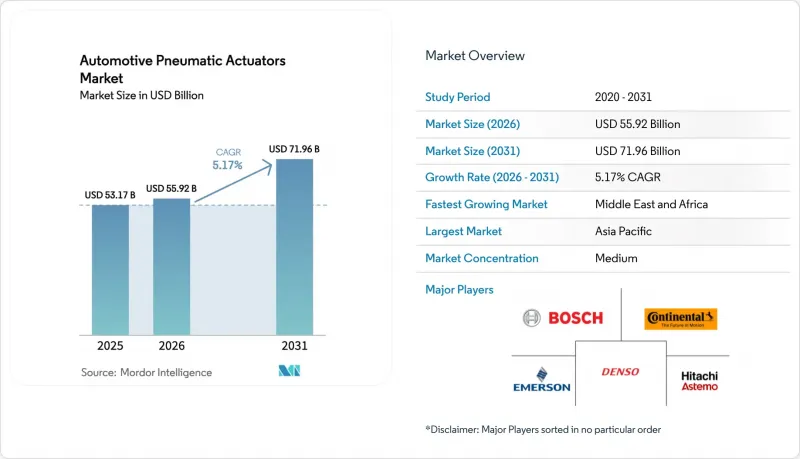
에 의하면, 자동차용 공압 액추에이터 시장 규모는 2025년에 531억 7,000만 달러로 평가되었고, 2026년 559억 2,000만 달러에서 2031년까지 719억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.17%를 기록할 전망입니다.
본 보고서는 용도별(스로틀 액추에이터, 연료 분사 액추에이터, 브레이크 액추에이터 등), 차종별(승용차, 소형 상용차 등),액추에이터 구조별(싱글 다이어프램식 공압 등), 판매 채널별(OEM 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 및 수량(단위)으로 제시되어 있습니다.
전 세계 자동차용 공압 액추에이터 시장 동향 및 인사이트
배기가스 규제 강화가 정밀한 공연비 제어를 촉진
2024년에 시행된 미국 환경보호청(EPA)의 3단계 대형차 배기가스 기준에 따라 NOx 허용치가 상향 조정됨에 따라, 디젤차 제조업체들은 고해상도 공압 밸브에 의존하는 EGR(배기가스 재순환) 및 분사 전략의 개선을 불가피하게 하고 있습니다. 이와 유사한 유로 7 초안 또한 유럽에서 수요의 정점을 유발하고 있습니다. 실험실 내 사이클 시험 대신 현장 검증 시험이 도입됨에 따라, 액추에이터는 실제 환경에서의 진동 및 온도 변동 하에서도 정밀도를 유지해야 합니다. 디지털 피드백 루프를 완성하는 전기-공압 패키지를 보유한 공급업체는 입찰에서 뚜렷한 우위를 점하고 있습니다. 규제 일정에 따라 수주 결정이 가속화되면서, 예측 기간 동안의 수익 전망이 확고해지고 있습니다.
전 세계 자동차 생산 대수 증가
소형차 및 대형차의 생산 대수가 증가함에 따라, 모든 공압 용도의 기본 수요가 상승하고 있습니다. 이는 조립되는 각 차량에 여러 개의 액추에이터 장착 위치가 있기 때문입니다. 일본자동차공업회(JAMA)는 2025년 OEM 일정에서도 연비 효율과 규제 준수를 확보하기 위해 브레이크, 스로틀 및 EGR 회로에 공압 솔루션이 계속해서 통합될 것임을 확인했습니다. 플랫폼 공유로 인해 생산 대수는 더욱 확대되고 있습니다. 이는 단일 액추에이터 제품군이 자매 모델 전체에 탑재될 수 있게 되어 공급업체의 규모의 경제가 높아지고 있기 때문입니다. 유럽과 미국의 제조업체들은 최종 조립 거점을 동남아시아로 재배치하고 있으며, 이에 따라 액추에이터 제조업체들은 모듈 생산 라인을 해당 지역으로 집약하도록 유도되고 있습니다. 따라서 전기식 경쟁 제품이 비용 경쟁력을 높여가고 있는 상황에서도, 생산 회복은 자동차용 공압 액추에이터 시장의 단기적 성장을 확고히 하고 있습니다.
에너지 효율이 뛰어난 전동 액추에이터로의 전환
전기 기계식 시스템은 배터리 전력을 최대 80%의 효율로 운동 에너지로 변환하여, 공압 구동식의 20%라는 상한선을 훨씬 뛰어넘습니다. 이 차이는 전기자동차에서 더욱 두드러지며, 1와트의 절약이 주행 거리 연장으로 이어집니다. 또한, 생산 라인 구축 업체들도 용접 로봇이나 자재 이송 암을 전동 실린더로 전환하여 궤적의 정밀도를 높이고 있습니다. 그러나 대형 트럭의 드럼 브레이크 등 높은 추력이 요구되는 분야에서는 압축 공기가 이미 차량 플랫폼에 필수적인 요소가 되었기 때문에 여전히 공압식이 주류를 이루고 있습니다. 그 결과, 각 공급업체들은 압력에 기반한 추력을 유지하면서 저에너지 위치 제어를 접목한 하이브리드형 액추에이터의 연구 개발에 주력하고 있습니다.
부문 분석
2025년, 자동차용 공압 액추에이터 시장에서 브레이크 챔버 및 주차 브레이크 캘리퍼 유닛은 31.12%의 점유율을 차지했습니다. 이 제품들은 모든 승용차 및 상용차 모델에 탑재가 의무화되어 있어 안정적인 판매량을 확보하고 있습니다. 전기기계식 주차 브레이크는 고급 세단에 점차 보급되고 있지만, 대형 트럭의 드럼 브레이크는 여전히 낮은 단가와 높은 클램핑력을 발휘하는 에어 챔버에 의존하고 있습니다. 터보차저의 웨스트게이트 액추에이터는 가장 빠르게 성장하는 분야로 그 뒤를 이어 연평균 성장률(CAGR) 6.43%로 성장을 지속하고, 있습니다. 이는 다운사이징된 가솔린 엔진이 출력 및 배기가스 규제 목표를 달성하기 위해 정밀한 과급압 제어가 필요하기 때문입니다. 스로틀 밸브, HVAC 블렌드 도어 및 EGR 버터플라이 밸브는 각각 규제 및 편의성 요구 사항에 힘입어 한 자릿수 중반의 성장률을 유지하고 있습니다.
공압식 연료 분사 레일 레귤레이터는 브라질에서 인기 있는 특정 플렉스 연료 사양에 여전히 채택되고 있으며, 도어 잠금 장치의 플런저는 비용 효율성을 중시하는 해치백 차량에서 여전히 일반적입니다. 전반적으로 각 공급업체들은 액추에이터 본체에 내장된 스마트 압력 센서를 이용하여 차량 제어 네트워크에 상태 데이터를 피드백하려는 시도를 하고 있습니다. 이러한 기능 강화 덕분에, 직접 구동식 전동 모터가 경쟁 격차를 좁혀가고 있음에도 불구하고 공압 구동 장치의 중요성은 여전히 유지되고 있습니다. 전반적으로, 이러한 용도의 구성은 자동차용 공압 액추에이터 시장이 10억 달러 규모의 두 자릿수 매출을 유지하고 있는 이유를 여실히 보여줍니다. 이는 모든 차량에 필수적인 안전, 배기가스, 편의성 관련 기능에 걸쳐 있기 때문입니다.
승용차는 2025년 매출의 56.05%를 차지하고 있으며, 이는 전 세계 공장에서의 막대한 생산 대수를 반영합니다. 그러나 대형 상용차는 연평균 성장률(CAGR) 5.63%를 기록하며, 자동차용 공압 액추에이터 시장 규모 확대를 주도할 것으로 예측됩니다. 차량 운영 사업자들은 가혹한 가동 주기 하에서 에어 브레이크 및 에어 서스펜션 회로의 내구성을 중시하고 있는 반면, CO₂ 배출 규제의 강화로 인해 기술을 전면적으로 교체하기보다는 압축기 관리의 최적화가 요구되고 있습니다. 소형 상용 밴은 전자상거래에 따른 소포 수요 증가와 연동되어, 도시 물류의 성장을 배경으로 견실한 연평균 성장률(CAGR)을 달성하고 있습니다. 건설·광산용 장비는 주로 고온용 배기 플랩 컨트롤러와 견고한 스티어링 스태빌라이저가 대상입니다.
이륜차는 특정 아시아 국가에 집중된 마이크로 부문 상태를 유지하고 있으나, 스쿠터 OEM 각사는 자동 클러치 작동용 저압 에어 서보의 시범 도입을 추진하고 있습니다. 이러한 다양성은 양극화를 여실히 드러내고 있습니다. 교외용 승용차는 NVH(소음·진동·거칠기)의 이점으로 인해 소형 전동 구동 시스템으로 전환되는 경향이 있는 반면, 고적재 차량은 힘 밀도와 검증된 유지보수성을 이유로 공압식을 유지하고 있습니다. 이러한 분화는 Tier 1 공급업체의 향후 플랫폼 전략을 형성하고 있으며, 인증 프로토콜을 재작성하지 않고도 마이크로 클래스부터 헤비 듀티 클래스까지 확장 가능한 모듈형 제품군의 생산을 요구하고 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 45.08%를 차지할 것으로 예상되며, 그 배경으로는 중국의 다브랜드 승용차 생산과 일본의 고정밀 밸브 기술력이 꼽힙니다. 베트남, 태국, 인도공급 거점이 가치 곡선을 따라 상승함에 따라, 이 지역은 연평균 성장률(CAGR) 6.84%를 나타낼 것으로 예측되며, 전 세계 자동차 제조업체들에게 이 지역 내 조달의 매력이 높아지고 있습니다. 한국의 전기 공압식 연구개발 센터는 한국의 선진적인 반도체 생태계를 활용하여 압력 MEMS 센서를 액추에이터의 PCB에 통합함으로써 경쟁력을 높이고 있습니다. 전기자동차의 보급이 진행되고 있음에도 불구하고, 비용이 최적화된 서브컴팩트 부문에서는 여전히 공압 구동식 HVAC 및 터보 웨이스트게이트 유닛이 채택되고 있어, 공급업체에게는 안정적인 공급량을 확보해 주고 있습니다.
중동 및 아프리카은 7.42%라는 견실한 연평균 성장률(CAGR)을 기록하며 가장 빠르게 성장하는 클러스터로 두각을 나타내고 있습니다. ‘사우디 비전 2030’의 산업 정책은 CKD 조립 라인을 유치하고 있으며, 건설 붐을 뒷받침하는 상용 트럭을 위해 각 라인에서 현지 생산된 액추에이터 부품의 채택이 요구되고 있습니다. 아랍에미리트(UAE)는 프리존의 물류망을 활용하여 예비 부품 키트를 아프리카 시장의 오지로 재수출하고 있습니다. 튀르키예는 유럽과의 관세 동맹을 통해 부품 수출을 확대하고 있으며, 이로 인해 공압 부품 공급업체들은 이즈미르와 부르사의 시설을 확장할 수밖에 없는 상황입니다. 이러한 동향으로 인해 조달 방식이 대륙 횡단 운송에서 시장 근접 생산으로 전환되어, 리드 타임 단축과 운송에 따른 배기가스 감축으로 이어지고 있습니다.
남미에서는 이 지역 특유의 플렉스 연료 엔진 구조로 인해 에탄올 혼합 연료가 거의 매일 연소 화학량론비를 변화시키기 때문에 EGR 및 연료 레일용 액추에이터에 대한 수요가 촉진되고 있습니다. 현지 조달 규제로 인해 다국적 공급업체들은 씰 스택을 수입하는 대신 미나스 제라이스주에 엘라스토머 가황 프레스를 설치해야 하는 상황에 처해 있습니다. 아르헨티나에서는 통화 안정화 조치에 따라 대형 트럭 조립이 회복되면서 대용량 브레이크 챔버에 대한 수요가 증가하고 있습니다. 통화 변동성과 정치적 리스크가 향후 전망을 둔화시키고 있지만, 기존 설비의 관성으로 인해 이 반구 지역의 자동차용 공압 액추에이터 시장은 견조한 모습을 유지하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the automotive pneumatic actuators market size was valued at USD 53.17 billion in 2025 and estimated to grow from USD 55.92 billion in 2026 to reach USD 71.96 billion by 2031, at a CAGR of 5.17% during the forecast period (2026-2031).
This report is Segmented by Application Type (Throttle Actuators, Fuel Injection Actuators, Brake Actuators, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Actuator Mechanism (Single-Diaphragm Pneumatic and More), Sales Channel (OEM and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Pneumatic Actuators Market Trends and Insights
Stricter emission norms driving precise air-fuel control
The US EPA's Phase 3 heavy-duty standards enacted in 2024 tighten NOx thresholds, compelling diesel makers to refine EGR and dosing strategies that rely on high-resolution pneumatic valves. Similar Euro 7 drafts trigger demand peaks in Europe. Field-valid testing replaces laboratory cycles, forcing actuators to sustain precision under real-world vibration and temperature excursions. Suppliers with electro-pneumatic packages that close the digital feedback loop enjoy distinct bidding advantages. The regulatory timetable accelerates award decisions, locking in revenue visibility for the forecast period.
Increasing global vehicle production
Rising light-duty and heavy-duty volumes lift baseline demand across all pneumatic applications because every unit assembled carries multiple actuator points. The Japan Automobile Manufacturers Association confirmed that OEM schedules for 2025 still embed pneumatic solutions in brake, throttle, and EGR circuits to assure fuel efficiency and compliance. Platform sharing further magnifies volumes because a single actuator family can now be fitted across sibling models, raising economies of scale for suppliers. Western manufacturers are repositioning final-assembly footprints toward Southeast Asia, which encourages actuator makers to co-locate module lines. The production rebound therefore secures near-term growth in the automotive pneumatic actuators market even as electric rivals sharpen their cost proposition.
Shift toward energy-efficient electric actuators
Electromechanical systems convert battery power into motion with up to 80% efficiency, dwarfing the 20% ceiling of air-driven counterparts. The delta becomes more pronounced in electric cars, where every watt saved extends range. Line-builders are also migrating their welding robots and material-handling arms to electric cylinders for tighter path accuracy. Yet pneumatics still dominates the highest-force nodes, such as heavy truck drum brakes, where compressed air is already integral to the vehicle platform. Consequently suppliers are channeling R&D toward mixed-technology actuators that preserve pressure-based force while embedding low-energy position control.
Other drivers and restraints analyzed in the detailed report include:
- ADAS proliferation demanding accurate actuation
- Lightweighting trend for fuel economy
- Complexity & high maintenance cost of pneumatics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Brake chambers and parking brake caliper units commanded 31.12% share of the automotive pneumatic actuators market in 2025. Their presence is mandated across every passenger and commercial vehicle variant, cementing baseline volume. Electromechanical parking brakes are penetrating luxury sedans, but heavy truck drum brakes still rely on air chambers that deliver high clamping force at low unit cost. Turbocharger wastegate actuators follow as the fastest riser, posting a 6.43% CAGR because downsized gasoline engines depend on accurate boost management to meet power and emission targets. Throttle valves, HVAC blend doors, and EGR butterflies retain mid-single-digit growth, each backed by regulatory or comfort imperatives.
Pneumatic fuel-injection rail regulators survive in certain flex-fuel layouts popular in Brazil, while door-lock plungers remain common in cost-sensitive hatchbacks. Across the board, suppliers experiment with smart pressure sensors embedded in actuator bodies to supply health data back to the vehicle control network. The enhancements prolong relevance of pneumatically powered devices even as direct electric motor drives tighten competitive gaps. Overall, the application mix underscores why the automotive pneumatic actuators market maintains double-digit billion-dollar revenues: it spans mandatory safety, emissions, and comfort functions that every vehicle must carry.
Passenger cars generated 56.05% of 2025 revenue, reflecting sheer production volume across global plants. Yet heavy commercial vehicles are projected to pace the automotive pneumatic actuators market size expansion with a 5.63% CAGR. Fleet operators prize the durability of air-brake and air-suspension circuits under intense duty cycles, while stricter CO2 quotas push for optimized compressor management rather than wholesale technology swaps. Light commercial vans track e-commerce parcel demand and achieve a robust CAGR on the back of city-logistics growth. Construction and mining equipment are, chiefly for high-temperature exhaust-flap controllers and robust steering stabilizers.
Two-wheelers remain a micro-segment concentrated in select Asian economies, yet scooter OEMs are trialing low-pressure air servos for automatic clutch actuation. The diversity highlights a bifurcation: suburban passenger cars gravitate toward compact electric drives for NVH advantages, whereas high-payload vehicles sustain pneumatics for force density and proven maintainability. That divergence shapes future platform strategies of tier-1 suppliers, compelling them to produce modular families that scale from micro to heavy-duty ratings without rewriting qualification protocols.
Complete Report Scope:
- By Application Type
- Throttle Actuators
- Fuel Injection Actuators
- Brake Actuators
- Exhaust Gas Recirculation Actuators
- Turbocharger Wastegate Actuators
- HVAC Actuators
- Door Lock Actuators
- Others
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Off-Highway Vehicles
- Two-Wheelers
- By Actuator Mechanism
- Single-Diaphragm Pneumatic
- Vacuum-Boost Pneumatic
- Electro-pneumatic (EP)
- Servo-pneumatic
- Rack-and-Pinion
- Rotary-Vane
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 45.08% of global revenue in 2025, underpinned by China's multi-brand passenger car output and Japan's high-precision valve competence. The region is forecast to post a 6.84% CAGR as supply bases in Vietnam, Thailand, and India climb the value curve, making in-region sourcing attractive for global nameplates. Electro-pneumatic R&D centers in South Korea exploit the country's advanced semiconductor ecosystem to integrate pressure MEMS sensors onto actuator PCBs, heightening competitive edge. Notwithstanding electric-vehicle penetration, cost-optimized sub-compact segments still install pneumatically driven HVAC and turbo wastegate units, securing volume for suppliers.
Middle East & Africa stands out as the fastest-growing cluster at a robust CAGR of 7.42%. Saudi Vision 2030 industrial policy lures CKD assembly lines, each demanding localized actuator content for commercial trucks that service construction booms. The UAE leverages free-zone logistics to re-export spare parts kits deeper into African markets. Turkey's customs-union access to Europe boosts its component exports, compelling pneumatic suppliers to expand Izmir and Bursa facilities. These dynamics re-orient procurement away from trans-continental shipping toward near-market production, shortening lead times and cutting freight emissions.
In South America, flex-fuel engine architectures unique to the region stimulate EGR and fuel-rail actuator demand because ethanol blends alter combustion stoichiometry daily. Local content rules push multinational suppliers to site elastomer curing presses in Minas Gerais rather than import seal stacks. Argentine heavy-truck assembly rebounds after currency stabilization measures, adding lift for high-capacity brake chambers. Currency volatility and political risk temper the outlook, yet installed base inertia keeps the automotive pneumatic actuators market resilient in the hemisphere.
- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- Emerson (ASCO Valve)
- Hitachi Astemo Ltd
- CTS Corporation
- Schrader Duncan Ltd
- Rotex Automation
- Nucon Industries Pvt Ltd
- Magneti Marelli SpA
- Mitsubishi Electric Corp
- Del-Tron Precision Inc
- Procon Engineering
- Valeo SA
- Aisin Corporation
- Mahle GmbH
- BorgWarner Inc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter emission norms driving precise air-fuel control
- 4.2.2 Increasing global vehicle production
- 4.2.3 ADAS proliferation demanding accurate actuation
- 4.2.4 Lightweighting trend for fuel economy
- 4.2.5 Hydrogen ICE valve-timing adoption
- 4.2.6 OTA-enabled actuator software monetisation
- 4.3 Market Restraints
- 4.3.1 Shift toward energy-efficient electric actuators
- 4.3.2 Complexity & high maintenance cost of pneumatics
- 4.3.3 Shortage of high-grade elastomers for seals
- 4.3.4 Tier-1 decarbonisation curbing pneumatic R&D
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Application Type
- 5.1.1 Throttle Actuators
- 5.1.2 Fuel Injection Actuators
- 5.1.3 Brake Actuators
- 5.1.4 Exhaust Gas Recirculation Actuators
- 5.1.5 Turbocharger Wastegate Actuators
- 5.1.6 HVAC Actuators
- 5.1.7 Door Lock Actuators
- 5.1.8 Others
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Medium and Heavy Commercial Vehicles
- 5.2.4 Off-Highway Vehicles
- 5.2.5 Two-Wheelers
- 5.3 By Actuator Mechanism
- 5.3.1 Single-Diaphragm Pneumatic
- 5.3.2 Vacuum-Boost Pneumatic
- 5.3.3 Electro-pneumatic (EP)
- 5.3.4 Servo-pneumatic
- 5.3.5 Rack-and-Pinion
- 5.3.6 Rotary-Vane
- 5.4 By Sales Channel
- 5.4.1 OEM
- 5.4.2 Aftermarket
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Robert Bosch GmbH
- 6.4.2 Continental AG
- 6.4.3 Denso Corporation
- 6.4.4 Emerson (ASCO Valve)
- 6.4.5 Hitachi Astemo Ltd
- 6.4.6 CTS Corporation
- 6.4.7 Schrader Duncan Ltd
- 6.4.8 Rotex Automation
- 6.4.9 Nucon Industries Pvt Ltd
- 6.4.10 Magneti Marelli SpA
- 6.4.11 Mitsubishi Electric Corp
- 6.4.12 Del-Tron Precision Inc
- 6.4.13 Procon Engineering
- 6.4.14 Valeo SA
- 6.4.15 Aisin Corporation
- 6.4.16 Mahle GmbH
- 6.4.17 BorgWarner Inc
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


