|
시장보고서
상품코드
2122046
스마트 센서 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Smart Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 2026년 스마트 센서 시장 규모는 903억 1,000만 달러로 추계되고 있으며, 2025년 770억 5,000만 달러에서 확대하며, 2031년에는 1,996억 8,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지의 연평균 성장률(CAGR)은 17.21%에 달할 전망입니다.
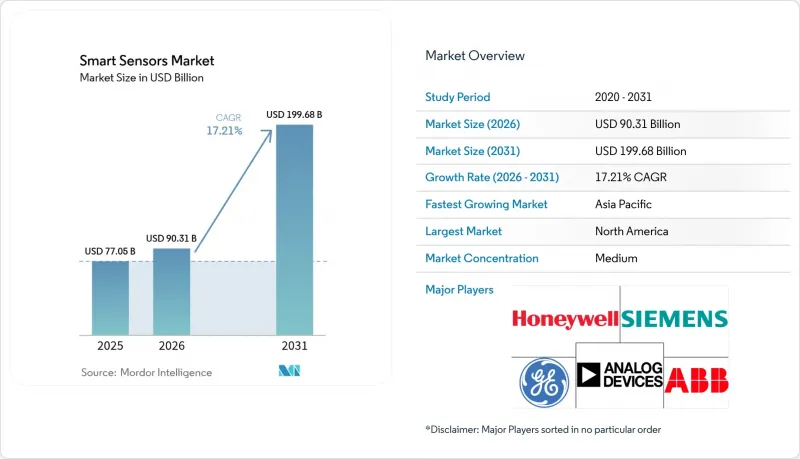
이 보고서는 유형별(유량 센서, 습도 센서, 위치 센서, 압력 센서 등), 기술별(MEMS, CMOS, 광학 분광법 등), 구성 요소별(A/D 변환기, D/A 변환기, 증폭기 등),용도별(항공우주·방위, 자동차·운송 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 스마트 센서 시장의 동향 및 인사이트
산업용 IoT에서의 에너지 효율화 추진
법적 구속력이 있는 지속가능성 보고 의무화로 인해 각 제조사는 측정 가능한 kWh 절감 및 CO₂ 배출량 감축을 실현하는 지능형 센서의 도입을 요구받고 있습니다. 유럽의 ‘기업 지속가능성 보고 지침’에서는 상세한 에너지 지표가 요구되고 있으며, 이에 따라 공장에서는 HVAC(냉난방·환기·공조), 조명, 기계 가동률을 지속적으로 최적화하는 엣지 AI 센서의 도입이 진행되고 있습니다. SECO사의 스마트 CNC 개조를 통해 생산 손실이 30%, 예비 부품 지출이 10% 감소하여, 모든 설비로 확대 적용할 타당성을 입증하는 구체적인 경제적 이점이 확인되었습니다. Lech-Stahlwerke사의 5G 지원 제철소에서도 유사한 성과를 거두었으며, 에너지 효율화 프로젝트는 이사회 차원의 우선 과제가 되었습니다. 조기 도입 기업이 두 자릿수 비용 절감을 보고하는 가운데, 뒤처진 기업은 이를 따라잡아야 한다는 경쟁적 압박에 직면해 있으며, 이로 인해 스마트 센서에 대한 수요가 자기 강화적인 순환을 만들어내고 있습니다.
소비자용 전자기기에서의 센서 보급
스마트폰 및 웨어러블 기기의 OEM(Original Equipment Manufacturer)들은 현재 기기 한 대당 최대 12종의 센서를 통합하여, 공기질 측정, 고급 생체인식, 자율 학습형 활동 추적 등의 기능을 지원하고 있습니다. 보쉬(Bosch)에 따르면 2025년에 출시될 휴대폰의 절반 이상이 이 회사의 멀티 센서 모듈을 탑재하여 출하될 전망입니다. 대량으로 발생하는 소비자 수요는 규모의 경제를 가져와 산업용 및 자동차용 시장 전반에 걸쳐 단가를 낮추고, 새로운 가성비 기준을 열어가고 있습니다. 웨어러블 기기를 위해 완성된 소형화 및 밀리와트 수준의 저전력 기술은 현재 공장 상태 모니터링 노드 및 자율 배송 로봇으로 전환되고 있으며, 엣지 지원 센서 스택이 업계를 넘어 빠르게 보급되고 있습니다.
높은 초기 도입 비용
스마트 센서의 포괄적인 도입에는 대개 엣지 게이트웨이, 사설 5G 네트워크, 그리고 직원 재교육에 대한 병행 투자가 필요합니다. 많은 중소규모 공장의 경우 총 지출액이 연간 매출의 0.5%를 초과할 가능성이 있으며, 손익분기점은 4개 회계 분기 이후로 미뤄지게 됩니다. 서울의 중소기업을 위한 Milesight의 턴키 IoT 키트는 LoRaWAN 게이트웨이와 컨트롤러를 번들로 제공하여 통합 장벽을 낮추고 있지만, 이 ‘올인원’ 패키지조차도 자본 예산에 부담을 주고 있습니다. MEMS 생산량이 확대됨에 따라 비용 측면의 역풍은 완화되고 있지만, 향후 24개월 동안 자금 사정이 어려운 사업자들의 경우 예산에 대한 신중한 태도가 도입을 억제할 것으로 예상됩니다.
부문 분석
2025년, 압력 센서 시장 규모는 216억 1,000만 달러에 달하여 스마트 센서 시장 전체의 28.05%라는 최대 점유율을 차지했습니다. 이 부문의 견고한 성장은 ADAS(첨단 운전자 지원 시스템)의 제동 제어, EV(전기자동차)의 배터리 관리, 의료용 인공호흡기에서 대체할 수 없는 역할을 담당하고 있기 때문입니다. 또한 실리콘 카바이드(SiC) 다이어프램에 대한 병행된 기술 혁신으로 인해 항공우주 분야 및 수소 연료 전지 스택용으로 작동 온도 범위가 600℃ 이상으로 확대되고 있습니다. 이미지 센서는 매출 규모는 작지만, 자율주행 규제로 인해 보행자 감지 카메라가 표준 사양으로 장착됨에 따라 연평균 성장률(CAGR) 18.85%로 성장할 것으로 예측됩니다. 글로벌 셔터와 이벤트 기반 픽셀의 통합으로 인해 급격하게 변화하는 조명 조건에서도 높은 콘트라스트 성능이 실현되어, 자동차 제조사는 고가의 LiDAR를 통한 이중화 없이도 AEB 규제를 준수할 수 있게 되었습니다.
수요의 다양화는 단위 경제성에도 변화를 가져오고 있습니다. 온도, 습도, 유량 센서는 스마트 시티의 상수도망이나 데이터센터의 열 관리 프로젝트를 통해 보급이 확대되고 있는 반면, 6축 위치 센서는 협동 로봇에 필수 요소로 자리 잡고 있습니다. 압력, 온도, 상대 습도 감지 기능을 결합한 하이브리드 모듈은 설치 비용을 절감하는 동시에, OEM 제조사의 전환 비용을 높임으로써 벤더 락인을 강화하고 있습니다.
2025년, MEMS 디바이스는 성숙한 파운드리 생태계와 스마트폰용 대량 생산에 적합한 비용 구조를 배경으로 스마트 센서 시장의 45.45% 점유율을 차지했습니다. 보쉬(Bosch) 한 회사만 해도 2024년에 60억 개 이상의 MEMS를 출하하여 그 규모 면에서 우위를 확실히 보여주고 있습니다. 그러나 포토닉 센서나 양자 기술을 활용한 센서도 연평균 성장률(CAGR) 20.95%로 확대될 것으로 예측되어, 고정밀 내비게이션 및 의료 진단 분야에서 MEMS의 점유율을 잠식할 가능성이 있습니다. 시티그룹의 추산에 따르면 양자 센싱 시장 규모는 2030년까지 14억 달러에 달할 전망이며, 이는 벤처 캐피털의 자금 유입을 촉진하고 있습니다. 이러한 상황에 대응하여 기존 MEMS 제조사들은 BioMEMS 채널 및 엣지 AI용 DSP 코어를 통합함으로써 대량 구매를 하는 고객들을 자사의 기술 로드맵 내에 묶어두려고 하고 있습니다.
미국-JOINT 프로그램 등의 업계 컨소시엄은 첨단 기판의 국내 공급망을 확보하기 위해 소재 연구개발을 가속화하고 있습니다. 이와 병행하여 MEMS 모듈에 내장된 신경모방 컴퓨팅 타일에 대한 연구도 진행되고 있으며, MEMS의 우위를 지원하는 크기와 비용상 이점을 해치지 않으면서 인지 기능을 구현하는 것을 목표로 하고 있습니다.
지역별 분석
아시아태평양은 2025년 전 세계 매출의 44.10%를 차지하며, 2031년까지 연평균 성장률(CAGR) 19.15%를 기록할 것으로 전망됩니다. 이는 중국의 ‘제14차 5개년 계획’에 따른 국내 센싱 IC에 대한 보조금과 일본의 양자 센싱 연구개발에 대한 협력적 지원금에 힘입은 결과입니다. 중국의 국내 시장은 2024년에 2,850억 위안(398억 달러)에 달할 것으로 보이며, 자동차, 공장 자동화, 네트워크 통신 분야가 각각 20% 이상의 점유율을 차지하고 있습니다. 지역 파운드리 업체들은 자사 수요와 투입 비용 인플레이션 억제라는 혜택을 받고 있으며, 이에 따라 수직 통합형 OEM 기업은 공급망 전반에 걸친 현지화를 추진하고 있습니다.
북미는 특히 자동차용 ADAS(첨단 운전자 보조 시스템) 및 항공우주용 센싱 분야에서 여전히 기술 선도자로서의 위상을 유지하고 있습니다. 하네웰과 NXP가 AI 지원 항공 전자 장비를 공동 개발하기 위해 전략적 제휴를 맺은 것은 해당 지역이 기능 안전과 엣지 컴퓨팅에 주력하고 있음을 보여주는 좋은 예입니다. CHIPS법에 따른 보조금을 포함하여 미국에서 지속되고 있는 산업 정책상의 인센티브로 인해 ams OSRAM 및 글로벌파운드리(GlobalFoundries)의 MEMS 생산 라인의 국내 복귀가 촉진되어 지역의 회복탄력성이 향상되고 있습니다.
유럽은 생산량 면에서는 아시아태평양(APAC)에 뒤처져 있지만, 규제에 따른 견인 효과의 혜택을 받고 있습니다. EU의 ‘일반 안전 규정 II’는 모든 신차에 필수적인 센서 세트를 기준으로 규정하고 있으며, 경기 침체기에도 꾸준한 생산량 확대를 보장하고 있습니다. 또한 기업의 탄소 배출 감축 목표에 따라 독일, 프랑스, 북유럽 국가에서 빌딩 자동화 및 산업용 효율화 센서에 대한 수요가 촉진되고 있습니다.
중동 및 아프리카, 남미의 신흥 시장에서는 스마트 시티 및 자원 부문의 디지털화 추진에 힘입어 센서 도입이 가속화되고 있습니다. 사우디아라비아의 기가 프로젝트에서는 환경 및 교통 관리를 위한 고밀도 센서 네트워크가 필요하며, 한편 칠레의 구리 광산에서는 채굴 효율을 높이기 위해 내환경성이 뛰어난 진동 센서가 도입되고 있습니다. 저지연 위성 백홀 솔루션을 통해 연결성의 장벽이 해소됨에 따라 이러한 지역에서는 기존 통신 인프라가 구축되어 있지 않더라도 첨단 센싱 기술을 도입할 수 있게 되었습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.03According to Mordor Intelligence, smart sensors market size in 2026 is estimated at USD 90.31 billion, growing from 2025 value of USD 77.05 billion with 2031 projections showing USD 199.68 billion, growing at 17.21% CAGR over 2026-2031.
This report is Segmented by Type (Flow Sensor, Humidity Sensor, Position Sensor, Pressure Sensor, and More), by Technology (MEMS, CMOS, Optical Spectroscopy, and More), by Component (Analog-To-Digital Converter, Digital-To-Analog Converter, Amplifier, and More), by Application (Aerospace and Defense, Automotive and Transportation, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart Sensors Market Trends and Insights
Energy-efficiency Push Across Industrial IoT
Legally binding sustainability reporting is prompting manufacturers to deploy intelligent sensors that deliver measurable kWh savings and CO2 reductions. The European Corporate Sustainability Reporting Directive requires granular energy metrics, pushing factories to install edge-AI sensors that continuously optimise HVAC, lighting, and machine utilisation. SECO's smart CNC retrofit cut production waste by 30% and spare-parts spend by 10%, showcasing hard-dollar returns that justify fleet-wide rollouts. Similar results at Lech-Stahlwerke's 5G-enabled mill have turned energy-efficiency projects into board-level priorities. As early adopters report double-digit cost reductions, laggards face competitive pressure to follow suit, creating a self-reinforcing demand cycle for intelligent sensors.
Consumer-electronics Sensor Proliferation
Smartphone and wearable OEMs now integrate up to a dozen sensor types per device, supporting features such as air-quality measurement, advanced biometrics, and self-learning activity tracking. Bosch confirms that more than half of 2025 handset launches ship with its multi-sensor modules. High-volume consumer demand delivers scale economies that drive per-unit cost down across industrial and automotive tiers, opening new price-performance thresholds. Miniaturisation and milliwatt-level power consumption perfected for wearables are now migrating into factory condition-monitoring nodes and autonomous delivery robots, accelerating cross-industry adoption of edge-ready sensor stacks.
High Upfront Deployment Cost
Comprehensive smart sensor rollouts frequently require parallel investment in edge gateways, private 5G networks, and workforce reskilling. For many small and midsized plants, total outlay can exceed 0.5% of annual revenue, deferring breakeven beyond four fiscal quarters. Milesight's turnkey IoT kit for Seoul SMEs bundles LoRaWAN gateways and controllers to lower integration friction, yet even this "all-in-one" package strains capital budgets. Cost headwinds are easing as MEMS volumes scale, but budgetary caution is expected to temper adoption among cash-constrained operators over the next 24 months.
Other drivers and restraints analyzed in the detailed report include:
- Automotive & E-health Safety Mandates
- On-sensor Edge-AI Lowers Latency
- Complex Design & Integration Skill Gap
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pressure sensors contributed USD 21.61 billion in 2025, translating to the largest 28.05% share of the smart sensors market. The segment's durability stems from its irreplaceable role in ADAS braking, EV battery management, and medical ventilators. Parallel innovation in silicon-carbide diaphragms now extends operating envelopes above 600 °C for aerospace and hydrogen fuel-cell stacks. Image sensors, while smaller in revenue terms, are forecast to grow at 18.85% CAGR as autonomous driving mandates make pedestrian-detection cameras standard equipment. Integration of global-shutter and event-based pixels is allowing high-contrast performance under rapidly changing lighting, enabling vehicle OEMs to comply with AEB regulations without expensive LiDAR redundancy.
Demand diversification is also reshaping unit economics. Temperature, humidity, and flow sensors are piggy-backing on smart-city water-grid and data-center thermal-management projects, while six-axis position sensors are becoming mandatory in collaborative robots. Hybrid modules that blend pressure, temperature, and relative humidity sensing deliver installation savings and strengthen vendor lock-in by raising switching costs for OEMs.
MEMS devices captured 45.45% of smart sensors market share in 2025 due to mature foundry ecosystems and cost structures tuned for smartphone volumes. Bosch alone shipped over 6 billion MEMS units in 2024, underscoring the scale advantage. However, photonic and quantum-enhanced sensors are projected to expand at 20.95% CAGR and could clip MEMS share in high-precision navigation and medical diagnostics. Citigroup estimates the quantum sensing addressable market could reach USD 1.4 billion by 2030, catalyzing venture capital inflows. MEMS incumbents are responding by co-integrating BioMEMS channels and edge-AI DSP cores to keep volume buyers within their technology roadmap.
Industry consortia such as the US-JOINT program, which includes 3M, are accelerating material R&D to secure domestic supply chains for advanced substrates. A parallel push into neuromorphic compute tiles embedded in MEMS modules aims to deliver cognitive functionality without sacrificing the size-cost advantage that underpin MEMS leadership.
Complete Report Scope:
- By Type
- Flow Sensors
- Humidity Sensors
- Position Sensors
- Pressure Sensors
- Temperature Sensors
- Image/Optical Sensors
- Other Types
- By Technology
- MEMS
- CMOS
- Optical Spectroscopy
- Quantum and Photonic
- Other Technologies
- By Component
- Analog-to-Digital Converter
- Digital-to-Analog Converter
- Amplifier
- Transceiver / RF Front-End
- Embedded AI Core
- Other Components
- By Application
- Aerospace and Defence
- Automotive and Transportation
- Healthcare and Medical Devices
- Industrial Automation
- Building and Home Automation
- Consumer Electronics
- Agriculture and Environmental
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- APAC
- China
- India
- Japan
- South Korea
- Rest of APAC
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific delivered 44.10% of 2025 global revenue and is expected to record a 19.15% CAGR through 2031, underpinned by China's 14th Five-Year Plan subsidies for domestic sensing ICs and Japan's coordinated quantum-sensing R&D grants. China's domestic market hit CNY 285 billion (USD 39.8 billion) in 2024, with automotive, factory automation, and network communications each capturing above-20% share. Regional foundries benefit from captive demand and lower input-cost inflation, prompting vertically integrated OEMs to localise entire supply chains.
North America remains technological bellwether, particularly in automotive ADAS and aerospace sensing. Honeywell's strategic partnership with NXP to co-develop AI-ready avionics exemplifies the region's focus on functional safety and edge compute. Ongoing US industrial-policy incentives, including CHIPS Act grants, are encouraging on-shoring of MEMS lines by ams OSRAM and GlobalFoundries, improving regional resilience.
Europe, while trailing APAC in volume, benefits from regulatory pull. The EU General Safety Regulation II sets a baseline of mandatory sensor suites in every new vehicle, guaranteeing steady volume ramps even in economic downturns. Additionally, corporate carbon-reduction targets are stimulating demand for building-automation and industrial-efficiency sensors across Germany, France, and the Nordics.
Emerging markets in the Middle East, Africa, and South America show accelerating sensor uptake through smart-city and resource-sector digitisation agendas. Saudi Arabia's giga-projects require dense environmental and traffic-management sensor grids, whereas Chilean copper mines are installing ruggedised vibration sensors to raise extraction efficiency. Low-latency satellite backhaul solutions are easing connectivity barriers, allowing these regions to adopt advanced sensing without legacy telecom infrastructure.
- ABB
- Honeywell International
- Eaton Corporation
- Analog Devices
- Infineon Technologies
- NXP Semiconductors
- STMicroelectronics
- Siemens AG
- TE Connectivity
- Legrand
- General Electric
- Vishay Intertechnology
- Bosch Sensortec
- Texas Instruments
- Omron Corporation
- Sensirion AG
- Murata Manufacturing
- Sony Semiconductor
- Samsung Electronics
- Robert Bosch GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Energy-efficiency push across industrial IoT
- 4.2.2 Consumer-electronics sensor proliferation
- 4.2.3 Automotive and e-health safety mandates
- 4.2.4 Miniaturisation and wireless advances
- 4.2.5 On-sensor edge-AI lowers latency
- 4.2.6 ESG-driven live-monitoring adoption
- 4.3 Market Restraints
- 4.3.1 High upfront deployment cost
- 4.3.2 Complex design and integration skill gap
- 4.3.3 IoT cybersecurity exposure
- 4.3.4 Rare-earth packaging supply risk
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Flow Sensors
- 5.1.2 Humidity Sensors
- 5.1.3 Position Sensors
- 5.1.4 Pressure Sensors
- 5.1.5 Temperature Sensors
- 5.1.6 Image/Optical Sensors
- 5.1.7 Other Types
- 5.2 By Technology
- 5.2.1 MEMS
- 5.2.2 CMOS
- 5.2.3 Optical Spectroscopy
- 5.2.4 Quantum and Photonic
- 5.2.5 Other Technologies
- 5.3 By Component
- 5.3.1 Analog-to-Digital Converter
- 5.3.2 Digital-to-Analog Converter
- 5.3.3 Amplifier
- 5.3.4 Transceiver / RF Front-End
- 5.3.5 Embedded AI Core
- 5.3.6 Other Components
- 5.4 By Application
- 5.4.1 Aerospace and Defence
- 5.4.2 Automotive and Transportation
- 5.4.3 Healthcare and Medical Devices
- 5.4.4 Industrial Automation
- 5.4.5 Building and Home Automation
- 5.4.6 Consumer Electronics
- 5.4.7 Agriculture and Environmental
- 5.4.8 Other Applications
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 APAC
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of APAC
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 UAE
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Kenya
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB
- 6.4.2 Honeywell International
- 6.4.3 Eaton Corporation
- 6.4.4 Analog Devices
- 6.4.5 Infineon Technologies
- 6.4.6 NXP Semiconductors
- 6.4.7 STMicroelectronics
- 6.4.8 Siemens AG
- 6.4.9 TE Connectivity
- 6.4.10 Legrand
- 6.4.11 General Electric
- 6.4.12 Vishay Intertechnology
- 6.4.13 Bosch Sensortec
- 6.4.14 Texas Instruments
- 6.4.15 Omron Corporation
- 6.4.16 Sensirion AG
- 6.4.17 Murata Manufacturing
- 6.4.18 Sony Semiconductor
- 6.4.19 Samsung Electronics
- 6.4.20 Robert Bosch GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment