|
시장보고서
상품코드
2122179
스마트 수도 계량 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Smart Water Meter - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
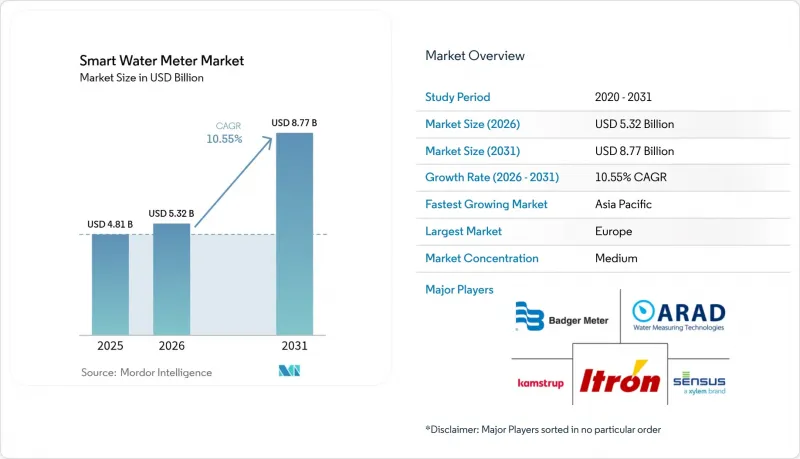
에 따르면 스마트 수도 계량 시장 규모는 2025년에 48억 1,000만 달러로 평가되며, 2026년 53억 2,000만 달러에서 2031년까지 87억 7,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 10.55%에 달할 전망입니다.
이 보고서는 기술별(자동 검침 및 첨단 계량 인프라), 용도별(주거용 등), 계량기 유형별(기계식/터빈식, 초음파식, 전자기식),통신 기술(무선 주파수, LoRaWAN/기타 LPWAN 등), 구성 요소(하드웨어, 소프트웨어 및 분석, 서비스), 배포 방식(신규 설치 및 개조/교체), 지역별로 분류되어 있습니다.
전 세계 스마트 수도 계량기 시장의 동향 및 인사이트
부양 요인으로 작용하는 정부 규제
도입 의무화 일정 및 수자원 효율화 기준에 따라 수도 사업자는 규정 준수 및 보고 요건을 충족하는 첨단 계량 솔루션의 도입을 강요받고 있습니다. EU의 음용수 지침에서는 종단 간 모니터링이 의무화되어 있으며, 이에 따라 독일과 프랑스에서는 모든 신축 및 대규모 개보수시 스마트 계량기 설치가 규정되어 있습니다. 캘리포니아주의 영구적인 물 사용 규정에서는 규제 집행을 위해 상세한 데이터가 요구되며, 재정 지원 수혜 요건으로 AMI 도입이 필수화되었습니다. 상수도 사업자는 물 손실 감소 및 고객 참여 증대를 입증함으로써 비용 회수 체계를 확보할 수 있으며, 이를 통해 투자 위험이 감소하고 관할 구역 전체에 걸친 도입이 촉진됩니다. 공급업체는 대량 발주를 통한 단가 인하라는 혜택을 누리는 한편, 정책 입안자는 절수 진행 상황을 추적하기 위한 투명성이 높은 성과 지표를 확보할 수 있습니다. 지자체, 지역, 국가 각 수준에서 규제는 스마트 수도 계량기 시장의 광범위한 보급에 필요한 장기적인 확실성을 지원하고 있습니다.
물 이용 효율 개선의 필요성
수자원이 부족한 지역의 수도 사업자는 커넥티드 계량기를 도입하여 대량 소비 패턴을 파악하고, 행동 변화를 유도하기 위해 시간 단위 데이터를 고객에게 제공하고 있습니다. 연속 원격 측정 기술을 활용하는 산업 시설에서는 누수를 파악하고 공정을 최적화한 결과, 소비량을 20-30% 줄였다고 보고되고 있습니다. 토양 수분 센서와 기상 정보를 기반으로 한 관개 일정을 결합한 농업 분야의 시범 사업에서는 최대 28%의 절수 효과가 기록되어, 분야를 초월한 유용성이 입증되었습니다. 물 생산 및 양수에는 막대한 운영비가 소요되므로, 효율 향상은 에너지 절약으로도 이어집니다. 분석 애플리케이션을 통한 수요 예측을 통해 상수도 사업자는 수요 피크를 평준화하고, 설비 용량 확장을 연기할 수 있게 됩니다. 상수도 사업자가 절수를 수익의 디커플링과 연계함으로써, 효율 향상은 안정적인 재무 실적으로 이어지며, 스마트 수도 계량기 시장의 성장을 지원합니다.
높은 초기 비용과 사이버 보안 위험
AMI의 전면 도입에는 엔드포인트 1대당 200-400달러의 비용이 소요되며, 자본 예산이 부족한 상수도 사업자에게는 큰 과제가 되고 있습니다. 요금 개정 승인을 받는 데 수년이 소요될 수 있으며, 프로젝트 시작 시기가 지연될 수 있습니다. 사이버 보안 대책, 암호화, 침입 탐지, 24시간 모니터링으로 인해 프로젝트 총 비용은 15-25% 더 증가합니다. 특히 개발도상국에서는 소규모 시스템의 경우 우대 대출이 없으면 투자가 미뤄지는 경우가 많습니다. 주목을 끄는 사이버 사고로 인해 규제 당국의 감시가 강화되면서 규정 준수 비용이 더욱 상승하고 있습니다. 이러한 요인들이 복합적으로 작용하여, 자금 조달 메커니즘이 성숙하고 보안 프레임워크가 표준화될 때까지 스마트 수도 계량기 시장의 성장을 저해할 것입니다.
부문 분석
2025년 기준, 자동 검침(AMR) 시스템은 스마트 수도 계량기 시장 점유율의 57.10%를 차지하고 있으며, 이는 확고한 기반과 비용 효율성이 뛰어난 단방향 데이터 전송을 반영한 것입니다. 많은 수도 사업자들은 현대화의 초기 단계에서 AMR을 도입하고 있습니다. 이는 드라이브바이 방식의 데이터 수집이 대규모 네트워크 구축 없이도 수작업을 대폭 줄일 수 있기 때문입니다. AMR과 관련된 스마트 수도 계량기 시장 규모는 여전히 크지만, 2세대 도입에서는 양방향 아키텍처가 주류를 이루게 되어 그 성장세는 완만해지고 있습니다.
유틸리티들이 실시간 누수 경보, 원격 차단 및 시간대별 요금 체계를 요구하는 가운데, 첨단 계량 인프라(AMI)는 2031년까지 연평균 성장률(CAGR) 11.55%를 기록하고 있습니다. 셀룰러, NB-IoT 및 LoRaWAN 모듈의 비용이 하락하면서 AMI 도입의 주요 장벽이 해소되고 있습니다. 서비스 제공업체는 계량기, 분석 기능 및 소프트웨어 구독을 패키지화하여 자본 비용을 운영 예산으로 분산시키고 있습니다. 풍부한 데이터를 처리하는 AMI 플랫폼은 절수 프로그램과 쉽게 통합되어 지역내 보급을 가속화하고, 스마트 수도 계량기 시장의 확대에 기여하고 있습니다.
유럽 및 북미에서 신축 주택에 스마트 계량기 설치를 의무화하는 규제가 잇따른 결과, 2025년에는 주거용 도입이 스마트 수도 계량기 시장 규모의 58.00%를 차지했습니다. 소비자는 절수 목표와 구체적인 절약 효과를 연결해 주는 사용 현황 포털의 혜택을 누리고 있으며, 안정적인 교체 주기가 유지되고 있습니다.
상업용 건물에서는 물·에너지·공조(HVAC) 데이터를 연동하는 시설 관리 소프트웨어의 지원에 힘입어 연평균 성장률(CAGR) 11.85%라는 가장 빠른 도입 속도를 보이고 있습니다. 고층 건물 소유주는 운영비 절감 및 그린 빌딩 인증 획득을 통해 투자의 타당성을 입증하고 있습니다. 소매 체인 및 호텔·레스토랑 기업은 분석을 활용하여 각 지점의 벤치마킹을 수행하고, 숨겨진 누수를 파악하며, 관개를 최적화하고 있습니다. 지속가능성 보고 기준이 엄격해짐에 따라 기업 사용자들은 도입을 확대하고 있으며, 이는 스마트 수도 계량기 시장 전체의 성장을 지원하고 있습니다.
지역별 분석
유럽은 물 손실 추적 및 투명한 요금 청구를 의무화하는 EU 지침에 힘입어 2025년 매출 점유율 36.10%로 스마트 수도 계량기 시장을 주도했습니다. 각국의 도입 로드맵을 통해 안정적인 입찰 프로젝트가 확보되었으며, 장기적인 공급업체 계약 체계가 조달 프로세스를 효율화하고 있습니다. 또한 공공사업자들은 기후 변화에 대한 회복력을 강화하기 위한 재건 자금을 활용하여, 지역 전체의 안정적인 수요를 지원하는 AMI(첨단 계량 인프라) 도입을 가속화하고 있습니다.
아시아태평양은 가장 빠른 성장세를 기록하고 있으며, 2031년까지 연평균 성장률(CAGR) 12.05%를 달성할 전망입니다. 중국에서는 광범위한 스마트 시티 시범 사업에서 인근 지역의 디지털 트윈에 계량 기능이 통합되어 있는 반면, 인도의 ‘Jal Jeevan Mission’에서는 스마트 엔드포인트를 포함한 농촌 지역의 연결에 자금이 투입되고 있습니다. 인도네시아와 베트남 등 동남아시아 국가에서는 급속한 도시화와 병행하여 레거시 자산의 갱신이 진행되고 있으며, 구식 기술에 얽힌 매몰 비용을 피하고 있습니다. 정부 보조금, 다자간 금융, 민관 파트너십이 어우러져 도입 규모를 확대하고, 스마트 수도 계량기 시장을 성장시키고 있습니다.
북미에서는 노후화된 인프라의 현대화와 주 전체 차원의 물 절약 의무화가 호재로 작용하고 있습니다. 캘리포니아주의 유틸리티는 AMI를 도입하여 1인당 사용량 제한을 철저히 시행하는 한편, 원격 차단 기능을 통해 산불에 대한 내성을 높이고 있습니다. 캐나다에서는 무수수 회수에 초점을 맞춘 주 차원의 현대화 프로그램이 진행되고 있으며, 이것이 추가적인 성장을 이끌고 있습니다. 라틴아메리카에서는 브라질의 운영권 입찰이 향후 큰 비즈니스 기회가 될 것임을 시사하고 있습니다. 한편, 중동 및 아프리카의 유틸리티들은 수자원 부족에 대처하고 부정 사용을 줄이기 위해 스마트 미터를 활용하고 있으나, 도입 진행 상황은 자금 조달 상황과 통신 네트워크 준비 상태에 따라 달라집니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the smart water meter market size was valued at USD 4.81 billion in 2025 and estimated to grow from USD 5.32 billion in 2026 to reach USD 8.77 billion by 2031, at a CAGR of 10.55% during the forecast period (2026-2031).

This report is Segmented by Technology (Automatic Meter Reading & Advanced Metering Infrastructure), Application (Residential, and More), Meter Type (Mechanical/Turbine, Ultrasonic, and Electromagnetic), Communication Technology (Radio-Frequency, LoRaWAN/Other LPWAN, and More), Component (Hardware, Software and Analytics, and Services), Deployment (New Installations and Retrofit/Replacement), and Geography.
Global Smart Water Meter Market Trends and Insights
Supportive Government Regulations
Mandatory deployment timelines and water-efficiency standards push utilities toward advanced metering solutions that satisfy compliance and reporting needs. The EU Drinking Water Directive requires end-to-end monitoring, prompting Germany and France to stipulate smart meters in all new constructions and major renovations. California's permanent water-use rules demand granular data for enforcement, making AMI rollouts a prerequisite for funding eligibility. Utilities gain cost recovery mechanisms when they document water-loss cuts and customer engagement improvements, which lowers investment risk and supports full-territory deployments. Vendors benefit from volume orders that reduce per-unit costs, while policymakers secure transparent performance metrics to track conservation progress. Across municipal, regional, and national levels, regulation underwrites the long-term certainty needed for widespread Smart Water Meter market adoption.
Need to Improve Water-Use Efficiency
Utilities in water-scarce regions adopt connected meters to identify high-consumption patterns and empower customers with hourly data that supports behavioral changes. Industrial facilities using continuous telemetry report 20-30% consumption cuts after pinpointing leaks and optimizing processes. Agricultural pilots that combine soil-moisture sensing with weather-based scheduling record up to 28% savings, demonstrating cross-sector utility. Efficiency gains also yield energy savings because water production and pumping constitute large operational expenses. Analytics applications forecast demand, allowing utilities to flatten peaks and defer capacity expansion. As utilities tie conservation to revenue decoupling, efficiency gains translate into stable financial performance and propel the Smart Water Meter market forward.
High Upfront Costs and Cybersecurity Risks
Full AMI rollouts cost USD 200-400 per endpoint, challenging utilities with tight capital budgets. Rate-case approvals can stretch over several years, delaying project start dates. Cybersecurity countermeasures, encryption, intrusion detection, and 24-hour monitoring raise the total project expense by an additional 15-25%. Smaller systems, especially in developing economies, often defer investments without concessional finance. High-profile cyber incidents intensify regulatory scrutiny, further elevating compliance costs. These factors collectively weigh on Smart Water Meter market growth until financing mechanisms mature and security frameworks standardize.
Other drivers and restraints analyzed in the detailed report include:
- Reducing Non-Revenue Water Losses
- Smart-City and IoT Platform Integration
- Systems-Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automatic Meter Reading systems accounted for 57.10% of Smart Water Meter market share in 2025, reflecting their entrenched base and cost-efficient one-way data transmission. Many utilities adopt AMR during early modernization phases because drive-by collection sharply reduces manual labor without extensive network build-out. The Smart Water Meter market size attached to AMR remains large, yet its growth moderates as second-generation rollouts favor two-way architectures.
Advanced Metering Infrastructure records an 11.55% CAGR to 2031 as utilities seek real-time leak alerts, remote disconnect, and time-variant pricing schemes. Cellular, NB-IoT, and LoRaWAN modules drop in cost, erasing a key barrier to AMI adoption. Service providers package meters, analytics, and software subscriptions, distributing capital costs over operating budgets. Data-rich AMI platforms integrate easily with conservation programs, accelerating regional penetration and widening the Smart Water Meter market.
Residential deployments formed 58.00% of the Smart Water Meter market size in 2025 after multiple European and North American mandates required smart meters for new housing. Consumers benefit from usage portals that connect conservation goals to tangible savings, sustaining stable replacement cycles.
Commercial buildings show the fastest uptake at a 11.85% CAGR, propelled by facility-management software that pairs water, energy, and HVAC data. High-rise real-estate owners justify investment through lower operating expenses and green-building certifications. Retail chains and hospitality groups apply analytics to benchmark sites, uncover concealed leaks, and optimize irrigation. As sustainability reporting frameworks tighten, enterprise users expand deployments, bolstering overall Smart Water Meter market growth.
Complete Report Scope:
- By Technology
- Automatic Meter Reading (AMR)
- Advanced Metering Infrastructure (AMI)
- By Application
- Residential
- Commercial
- Industrial
- Agricultural
- By Meter Type
- Mechanical / Turbine
- Ultrasonic
- Electromagnetic
- By Communication Technology
- Radio-frequency (Proprietary RF)
- LoRaWAN / Other LPWAN
- Cellular (NB-IoT/LTE-M)
- Wired (M-Bus/Ethernet)
- By Component
- Hardware
- Software and Analytics
- Services
- By Deployment
- New Installations
- Retrofit / Replacement
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Singapore
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Europe dominated the Smart Water Meter market with 36.10% revenue share in 2025, anchored by EU directives that compel water-loss tracking and transparent billing. National implementation roadmaps guarantee steady tender pipelines, and long-term vendor frameworks streamline procurement. Utilities also tap recovery funds targeting climate resilience, accelerating district-wide AMI deployments that underpin stable regional demand.
Asia-Pacific registers the fastest expansion, clocking a 12.05% CAGR to 2031. China's extensive smart-city pilots embed metering within neighborhood digital twins, while India's Jal Jeevan Mission finances rural connections that include smart endpoints. Southeast Asian economies such as Indonesia and Vietnam upgrade legacy assets concurrently with rapid urbanization, avoiding sunk costs tied to older technologies. Government grants, multilateral loans, and public-private partnerships combine to scale installations and enlarge the Smart Water Meter market.
North America benefits from aging infrastructure replacement and statewide conservation mandates. California utilities deploy AMI to enforce per-capita usage limits and to support wildfire resilience through remote shut-off capabilities. Canada advances province-level modernization programs focusing on non-revenue water recovery, adding incremental growth. Latin America's concession tenders in Brazil signal sizable upcoming opportunities, while Middle East and Africa utilities leverage smart meters to address scarcity and reduce theft, though deployment progress varies by funding availability and communication-network readiness.
- Arad Ltd.
- Badger Meter Inc.
- Itron Inc.
- Sensus USA Inc. (Xylem Inc.)
- Kamstrup A/S
- Diehl Stiftung and Co. KG
- Zenner International GmbH and Co. KG
- Landis+Gyr Group AG
- Honeywell International Inc.
- Neptune Technology Group Inc. (Roper)
- Aclara Technologies LLC (Hubbell)
- Apator SA
- Axioma Metering
- B Meters Srl
- Datamatic Inc.
- Maddalena S.p.A.
- Suntront Tech Co., Ltd.
- Mueller Systems LLC
- Waviot
- Watertech S.p.A. (Arad)
- Jiangxi Sanchuan Water Meter Co. Ltd.
- Ningbo Water Meter Co. Ltd.
- BETAR Company
- Integra Metering AG
- IESLab Electronic Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Supportive government regulations
- 4.2.2 Need to improve water-use efficiency
- 4.2.3 Reducing non-revenue water (NRW) losses
- 4.2.4 Smart-city and IoT platform integration
- 4.2.5 Pay-as-you-save financing models
- 4.2.6 Drought-driven conservation mandates
- 4.3 Market Restraints
- 4.3.1 High upfront costs and cybersecurity risks
- 4.3.2 Systems-integration complexity
- 4.3.3 Shortage of utility data-analytics talent
- 4.3.4 Battery-life limits in ultrasonic units
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 ROI Analysis for Smart Meters
- 4.9 Protocol Benchmarking and Comparison
- 4.10 LoRaWAN Implementation Steps and Use-cases
- 4.11 Utility Digitalisation Benefits
- 4.12 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Technology
- 5.1.1 Automatic Meter Reading (AMR)
- 5.1.2 Advanced Metering Infrastructure (AMI)
- 5.2 By Application
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Industrial
- 5.2.4 Agricultural
- 5.3 By Meter Type
- 5.3.1 Mechanical / Turbine
- 5.3.2 Ultrasonic
- 5.3.3 Electromagnetic
- 5.4 By Communication Technology
- 5.4.1 Radio-frequency (Proprietary RF)
- 5.4.2 LoRaWAN / Other LPWAN
- 5.4.3 Cellular (NB-IoT/LTE-M)
- 5.4.4 Wired (M-Bus/Ethernet)
- 5.5 By Component
- 5.5.1 Hardware
- 5.5.2 Software and Analytics
- 5.5.3 Services
- 5.6 By Deployment
- 5.6.1 New Installations
- 5.6.2 Retrofit / Replacement
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Chile
- 5.7.2.4 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 India
- 5.7.4.3 Japan
- 5.7.4.4 South Korea
- 5.7.4.5 Malaysia
- 5.7.4.6 Singapore
- 5.7.4.7 Australia
- 5.7.4.8 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 United Arab Emirates
- 5.7.5.1.2 Saudi Arabia
- 5.7.5.1.3 Turkey
- 5.7.5.1.4 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Arad Ltd.
- 6.4.2 Badger Meter Inc.
- 6.4.3 Itron Inc.
- 6.4.4 Sensus USA Inc. (Xylem Inc.)
- 6.4.5 Kamstrup A/S
- 6.4.6 Diehl Stiftung and Co. KG
- 6.4.7 Zenner International GmbH and Co. KG
- 6.4.8 Landis+Gyr Group AG
- 6.4.9 Honeywell International Inc.
- 6.4.10 Neptune Technology Group Inc. (Roper)
- 6.4.11 Aclara Technologies LLC (Hubbell)
- 6.4.12 Apator SA
- 6.4.13 Axioma Metering
- 6.4.14 B Meters Srl
- 6.4.15 Datamatic Inc.
- 6.4.16 Maddalena S.p.A.
- 6.4.17 Suntront Tech Co., Ltd.
- 6.4.18 Mueller Systems LLC
- 6.4.19 Waviot
- 6.4.20 Watertech S.p.A. (Arad)
- 6.4.21 Jiangxi Sanchuan Water Meter Co. Ltd.
- 6.4.22 Ningbo Water Meter Co. Ltd.
- 6.4.23 BETAR Company
- 6.4.24 Integra Metering AG
- 6.4.25 IESLab Electronic Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment