

|
시장보고서
상품코드
2122203
첨단 시각화 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Advanced Visualization - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
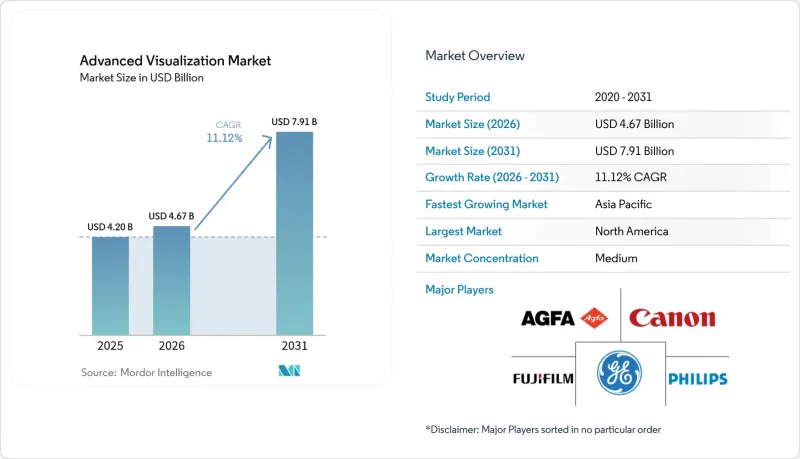
에 의하면, 2026년 첨단 시각화 시장 규모는 46억 7,000만 달러로 추정되고 2025년 42억 달러에서 성장하여 2031년에는 79억 1,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 11.12%가 될 것으로 전망됩니다.
본 보고서에서는 업계를 제품 및 서비스별(하드웨어 등), 솔루션 유형별(엔터프라이즈 플랫폼,독립형 도구), 도입 모델별(On-Premise 등), 영상 진단법별(MRI, CT 등), 임상 응용 분야별(종양학, 순환기 등), 최종 사용자별(병원 등) 및 지역별로 분류하고 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 첨단 시각화 시장 동향 및 인사이트
AI를 활용한 자동 분할이 진단 효율을 혁신
1,000건이 넘는 임상용 AI 용도(그중 77%가 방사선 의학 분야)이 연방 정부의 승인을 획득함에 따라 워크플로우 자동화의 타당성이 입증되었습니다. 이에 따라 캐논 메디컬의 ‘INSTINX’와 같은 플랫폼에서는 심장 CT 워크플로우에서 클릭 횟수를 40% 줄일 수 있게 되었으며, Philips의 ‘SmartSpeed Precise’에서는 MRI 스캔을 3배 더 빠르게 완료하고 영상 선명도를 80% 향상시킬 수 있게 되었습니다. 이러한 생산성 향상은 전문 기관들이 2030년을 훨씬 넘어서까지 지속될 것으로 예측하는 18.1%의 방사선과 의사 부족률을 상쇄하는 데 도움이 되고 있습니다. 중재실에서는 실시간 세분화이 현재 94%의 재검토 정확도로 경동맥 스텐트 삽입을 안내하고 있으며, AI의 가치가 진단에서 치료 계획으로 확대되고 있습니다.
엔터프라이즈 PACS 통합이 업무 통합을 촉진
섹트라의 클라우드 기반 엔터프라이즈 이미징 제품군에 대한 수주액이 40억 스웨덴 크로나를 넘어 사상 최고치를 기록한 것은 데이터 사일로를 해소하고 방사선과, 순환기내과, 병리과에 걸친 워크플로우를 표준화하는 통합 아키텍처에 대한 의료 시스템 수요가 높음을 입증합니다. PACSonWEB 등 클라우드 네이티브 PACS의 도입으로 의사가 언제 어디서나 영상을 열람할 수 있게 되면서, 12개월 이내에 병원 간 의뢰 건수가 10% 증가했습니다. 구독형 가격 책정이 영구 라이선스를 대체하고 있으며, 이로 인해 자본 지출이 절감되는 동시에 공급업체의 인센티브가 가동률 및 사이버 보안 성능 보증과 연동되고 있습니다.
데이터 개인정보 보호 규제가 클라우드 도입의 장벽이 되고 있다.
암호화 키의 주권을 국경에 연동시키는 GDPR(EU 개인정보보호규정) 조항으로 인해, 클라우드 PACS 공급업체는 정교한 키 관리 인프라를 도입할 수밖에 없게 되었으며, 이로 인해 유럽 내 도입 비용이 급등하고 판매 주기가 장기화되고 있습니다. 2024년에는 방사선과를 표적으로 한 사이버 사고가 67% 증가했으며, 퍼블릭 클라우드의 위험 프로파일에 대한 구매자의 심사가 엄격해지는 가운데,병원들은 환자 식별 정보를 On-Premise에 보관하면서, 익명화된 영상을 AI 추론을 위해 클라우드로 전송하는 하이브리드 아키텍처로의 전환을 강요받고 있습니다.
부문별 분석
세분화, 관류 매핑, 구조화된 보고서 생성을 자동화하는 AI 분석의 도입이 가속화됨에 따라, 소프트웨어 솔루션은 2025년 총 수익의 45.12%를 차지했으며, 첨단 시각화 시장 규모로는 약 18억 9,000만 달러에 해당합니다. 구독 기반 업그레이드를 통해 알고리즘의 지속적인 업데이트가 제공되며, 고객 유지율은 95% 이상을 유지하고 있습니다. 광자 계수형 CT나 3테슬라 MR 시스템에는 전용 GPU나 검출기 어레이가 필요하기 때문에 하드웨어 매출은 여전히 큰 비중을 차지하고 있지만, 가치의 형태는 X선관이나 간트리가 아닌 코드를 통해 임상적 개선이 이루어지는 ‘소프트웨어 정의형 이미징’으로 전환되고 있습니다. 서비스 부문은 의료 서비스 제공업체가 후처리, 사이버 보안, 가동 시간 보장을 매니지드 서비스 계약에 위탁하는 경향이 강해지고 있어 12.74%의 성장 전망을 보이며, 다른 모든 카테고리를 능가하는 성장세를 보이고 있습니다.
첨단 영상 산업 전반에서는 바쁜 응급실 전체에 씬 클라이언트 액세스를 실현하는 클라우드 오케스트레이션이 채택되어, 도입 주기가 수개월에서 수주로 단축되고 있습니다. 벤더의 로드맵에서는 현재 API가 풍부한 플랫폼이 우선시되고 있으며, 타사 AI 개발자가 워크플로우를 방해하지 않고 새로운 알고리즘을 통합할 수 있게 됨에 따라 이전에 구매한 하드웨어의 투자 대비 효과가 향상되고 있습니다. 종양학 및 순환기학 프로그램에서 전용 AI 번들이 배포됨에 따라, 소프트웨어 과금 체계는 벤더의 수익을 임상 건수와 연동시키는 검사 단위 가격 책정으로 전환되고 있습니다.
의료 네트워크가 방사선과, 순환기과, 나아가 디지털 병리학까지 아우르는 ‘단일 워크리스트’와 ‘단일 뷰어’의 도입을 선호함에 따라, 2025년에는 엔터프라이즈 플랫폼이 53.60%의 점유율을 차지했습니다. 여러 병원으로 구성된 구매 그룹이 표준 통일을 위해 벤더 중립 아카이브(NVA)나 실적 제로 뷰어를 규정하고 있기 때문에 이러한 통합 허브는 앞으로도 계속 확대될 전망입니다. 그럼에도 불구하고, 독립형 AI 용도는 척추 골절 감지 등 대규모 솔루션에서는 통합이 진행되지 않는 미해결 마이크로 워크플로우를 대상으로 함으로써 12.05%의 연평균 성장률(CAGR)을 기록하고 있습니다.
기업용 판매의 경우, 대부분의 경우 광자 계수 CT 라이선스, 종양학 자동 윤곽 그리기, 클라우드 재해 복구가 7년짜리 OPEX 계약에 묶여 있어, 이로 인해 전환 비용이 증가하고 브랜드 충성도가 굳어지고 있습니다. 틈새 시장 개발자의 경우, 주요 플랫폼에 통합된 마켓플레이스의 앱 스토어를 통한 배포를 통해 막대한 현장 영업 비용을 들이지 않고도 도달 범위를 확대할 수 있어, 소규모 기업도 진입할 수 있는 첨단 시각화 시장 규모가 확대되고 있습니다.
지역별 분석
북미는 2025년에 매출의 42.70%를 차지했습니다. 이는 모달리티 도입 대수가 밀집되어 있고, AI에 관한 510(k) 승인을 가장 빨리 획득했으며, 현재 관상동맥 CTA 검사 1회당 357.13달러를 환급하는 CMS의 지불 개혁에 힘입은 결과입니다. GE 헬스케어와 NVIDIA의 자율 스캔 공동 개발에 대표적으로 나타나는 바와 같이, 학계와 산업계의 파트너십은 향후 전 세계로 확산될 알고리즘을 지속적으로 육성하고 있습니다. 지속적인 인력 부족은 방사선과 그룹이 증가하는 수요에 대응하려는 가운데, 생산성 향상 소프트웨어에 호재가 되고 있습니다.
아시아태평양은 일본, 호주, 한국이 광자 계수형 CT로 업그레이드를 추진하는 한편, 인도 등 인구가 많은 국가들이 합리적인 가격의 클라우드 PACS를 도입하여 3차 의료 수준의 진단을 2급 도시까지 확대하고 있어 13.10%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. GE 헬스케어의 일본 메디피직스(Mediphysics) 인수 사례는 시각화 플랫폼을 보완하는 분자 영상 공급망에 대한 지역적 관심을 부각시키고 있습니다. 싱가포르와 한국의 국가 차원 AI 거버넌스 프레임워크는 규제 절차를 간소화하고, 현지 스타트업이 국제 의료기기 생태계에 통합되도록 뒷받침하고 있습니다.
유럽에서는 복잡한 GDPR(EU 개인정보보호규정) 준수 과제가 있는 가운데 완만한 성장이 예상됩니다. EU 역내에서 암호화 키 보관을 보장할 수 있는 공급업체는 경쟁 우위를 확보하고 있습니다. Philips가 소버린 클라우드 환경에서 ‘HealthSuite Imaging’을 배포한 것은 규제 준수와 혁신이 공존할 수 있음을 보여줍니다. 또한, 사이버 보안에 대한 경계심이 높아짐에 따라 레거시 PACS에서 제로 트러스트 및 벤더 중립 아카이브(NVA)로의 전환이 진행되면서, 첨단 시각화 시장의 매출을 서서히 끌어올리고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, advanced visualization market size in 2026 is estimated at USD 4.67 billion, growing from 2025 value of USD 4.20 billion with 2031 projections showing USD 7.91 billion, growing at 11.12% CAGR over 2026-2031.
This report Segments the Industry Into by Product and Service (Hardware, and More), by Solution Type (Enterprise Platform, Standalone Tool), by Deployment Model (On-Premise, and More), Imaging Modality ((MRI), (CT), and More), by Clinical Application (Oncology, Cardiovascular, and More), End User (Hospitals, and More), and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Advanced Visualization Market Trends and Insights
AI-Powered Auto-Segmentation Transforms Diagnostic Efficiency
Federal clearance of more than 1,000 clinical AI applications-77% for radiology-has legitimized workflow automation, enabling platforms like Canon Medical INSTINX to remove 40% of cardiac-CT workflow clicks and Philips SmartSpeed Precise to finish MRI scans three-times faster with 80% sharper images. These productivity gains help offset a radiologist vacancy rate of 18.1% that professional bodies project will persist well beyond 2030. In interventional suites, real-time segmentation now guides carotid stenting with 94% recall accuracy, broadening AI value from diagnostics into therapy planning.
Enterprise PACS Integration Drives Operational Consolidation
Record order bookings above SEK 4 billion for Sectra's cloud enterprise imaging suite underscore health-system appetite for unified architectures that eradicate data silos and standardize workflow across radiology, cardiology and pathology departments. Cloud-native PACS rollouts such as PACSonWEB have lifted cross-hospital referrals by 10% within 12 months because physicians can view images anywhere, anytime. Subscription pricing is overtaking perpetual licenses, lowering capital outlays and aligning vendor incentives with uptime and cybersecurity performance guarantees.
Data-Privacy Regulations Create Cloud Barriers
GDPR clauses that tie encryption-key sovereignty to national boundaries force cloud PACS vendors to deploy elaborate key-management infrastructure, elevating deployment cost and lengthening sales cycles in Europe. Cyber incidents targeting radiology grew 67% in 2024, intensifying buyer scrutiny over public-cloud risk profiles and nudging hospitals toward hybrid architectures that keep patient identifiers on-premise while pushing de-identified images into the cloud for AI inference .
Other drivers and restraints analyzed in the detailed report include:
- Reimbursement Expansion Validates Quantitative Imaging Value
- Photon-Counting CT Enables Next-Generation Spectral Imaging
- Healthcare IT Staffing Shortages Constrain Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software solutions contributed 45.12% to overall 2025 revenue, equivalent to roughly USD 1.89 billion of advanced visualization market size, due to accelerating adoption of AI analytics that automate segmentation, perfusion mapping and structured reporting. Subscription-based upgrades deliver continuous algorithm refreshes, cementing retention rates above 95%. Hardware revenues remain sizable because photon-counting CT and 3-Tesla MR systems require specialized GPUs and detector arrays, yet the value narrative is shifting toward software-defined imaging where clinical improvements come through code instead of tubes and gantries. Services out-paced every other category with a 12.74% growth outlook as providers outsource post-processing, cybersecurity and uptime guarantees to managed-service contracts.
The broader advanced visualization industry is embracing cloud orchestration that allows thin-client access across busy emergency departments, collapsing installation cycles from months to weeks. Vendor roadmaps now prioritize API-rich platforms so third-party AI developers can plug-in novel algorithms without disrupting workflow, enhancing return on earlier hardware purchases. As oncology and cardiology programs roll out dedicated AI bundles, software billing is moving to exam-based pricing that aligns vendor revenue with clinical volume.
Enterprise platforms captured 53.60% share in 2025 as health networks favor single worklist, single viewer implementations that cover radiology, cardiology and even digital pathology. These integrated hubs are poised to keep expanding because multi-hospital purchasing groups stipulate vendor-neutral archives and zero-footprint viewers to harmonize standards. Standalone AI applications nevertheless post a 12.05% CAGR by targeting unmet micro-workflows-such as spine fracture detection-that large suites integrate only slowly.
An enterprise sale often bundles photon-counting CT licenses, oncology auto-contouring and cloud disaster-recovery into a seven-year opex contract, increasing switching costs and entrenching brand loyalty. For niche developers, distribution through marketplace app-stores embedded in leading platforms offers reach without heavy field-sales overheads, broadening the advanced visualization market addressable by smaller firms.
Complete Report Scope:
- By Product & Service
- Hardware
- Software
- Services
- By Solution Type
- Enterprise Platform
- Standalone Tool
- By Deployment Model
- On-premise
- Cloud-based
- Hybrid
- By Imaging Modality
- Magnetic Resonance Imaging (MRI)
- Computed Tomography (CT)
- Ultrasound
- Nuclear Medicine (PET/SPECT)
- Emerging Modalities (Photon-Counting CT, Photoacoustic)
- By Clinical Application
- Oncology
- Cardiovascular
- Neurology
- Orthopedics & Musculoskeletal
- Gastro-Hepatology
- By End User
- Hospitals
- Diagnostic Imaging Centers
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 42.70% revenue in 2025, underpinned by dense modality install bases, earliest AI 510(k) clearances and CMS payment reforms that now reimburse coronary CTA at USD 357.13 per exam. Academic-industry partnerships-exemplified by GE HealthCare and NVIDIA's work on autonomous scanning-continue to incubate algorithms later deployed worldwide. Ongoing staff shortages create tailwinds for productivity software as radiology groups seek to meet rising demand.
Asia-Pacific registers the steepest 13.10% CAGR as Japan, Australia and South Korea upgrade to photon-counting CT while populous countries such as India deploy affordable cloud PACS to extend tertiary-level diagnostics into tier-II cities. GE HealthCare's acquisition of Nihon Medi-Physics underscores regional interest in molecular imaging supply chains that complement visualization platforms. National AI governance frameworks in Singapore and South Korea streamline regulatory paths, encouraging local startups to integrate into international device ecosystems.
Europe posts moderate gains amid complex GDPR compliance. Vendors able to guarantee encryption-key residency within EU borders gain competitive advantage. Philips' rollout of HealthSuite Imaging on sovereign-cloud instances demonstrates how regulatory adherence and innovation can coexist. Furthermore, heightened cybersecurity vigilance spurs replacement of legacy PACS with zero-trust, vendor-neutral archives-driving incremental advanced visualization market revenues.
- Agfa-Gevaert
- Canon Inc. (Canon Medical Systems)
- Carestream Health
- FUJIFILM
- GE HealthCare Technologies Inc.
- Koninklijke Philips
- Siemens Healthineers
- Sectra
- Pro Medicus Ltd (Visage Imaging)
- Terarecon
- Intelerad Medical Systems
- Vital Images (Canon Group)
- Merative (ex-IBM Watson Health)
- Rad AI
- Blackford Analysis
- Circle Cardiovascular Imaging
- Coreline Soft
- VoxelCloud
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-powered auto-segmentation cuts reading time by >40%
- 4.2.2 Integration of AV into enterprise PACS/VNA ecosystems
- 4.2.3 Reimbursement expansion for quantitative imaging CPT codes
- 4.2.4 Vendor-neutral cloud platforms enable multi-site collaboration (under-radar)
- 4.2.5 Photon-counting CT & spectral MRI drive 4-D visualisation demand (under-radar)
- 4.2.6 In-scanner decision-support for interventional suites (under-radar)
- 4.3 Market Restraints
- 4.3.1 Patchy reimbursement outside US & Japan
- 4.3.2 Data-privacy rules slowing cloud roll-outs in EU
- 4.3.3 Ongoing shortage of imaging IT staff at hospitals (under-radar)
- 4.3.4 GPU supply-chain volatility raises TCO for vendors (under-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value - USD)
- 5.1 By Product & Service
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Solution Type
- 5.2.1 Enterprise Platform
- 5.2.2 Standalone Tool
- 5.3 By Deployment Model
- 5.3.1 On-premise
- 5.3.2 Cloud-based
- 5.3.3 Hybrid
- 5.4 By Imaging Modality
- 5.4.1 Magnetic Resonance Imaging (MRI)
- 5.4.2 Computed Tomography (CT)
- 5.4.3 Ultrasound
- 5.4.4 Nuclear Medicine (PET/SPECT)
- 5.4.5 Emerging Modalities (Photon-Counting CT, Photoacoustic)
- 5.5 By Clinical Application
- 5.5.1 Oncology
- 5.5.2 Cardiovascular
- 5.5.3 Neurology
- 5.5.4 Orthopedics & Musculoskeletal
- 5.5.5 Gastro-Hepatology
- 5.6 By End User
- 5.6.1 Hospitals
- 5.6.2 Diagnostic Imaging Centers
- 5.6.3 Others
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East & Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East & Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Agfa-Gevaert Group
- 6.3.2 Canon Inc. (Canon Medical Systems)
- 6.3.3 Carestream Health
- 6.3.4 Fujifilm Holdings Corporation
- 6.3.5 GE HealthCare Technologies Inc.
- 6.3.6 Koninklijke Philips N.V.
- 6.3.7 Siemens Healthineers AG
- 6.3.8 Sectra AB
- 6.3.9 Pro Medicus Ltd (Visage Imaging)
- 6.3.10 Terarecon Inc.
- 6.3.11 Intelerad Medical Systems
- 6.3.12 Vital Images (Canon Group)
- 6.3.13 Merative (ex-IBM Watson Health)
- 6.3.14 Rad AI
- 6.3.15 Blackford Analysis
- 6.3.16 Circle Cardiovascular Imaging
- 6.3.17 Coreline Soft
- 6.3.18 VoxelCloud
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


