

|
시장보고서
상품코드
2122214
고관절 치환술 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Hip Replacement - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
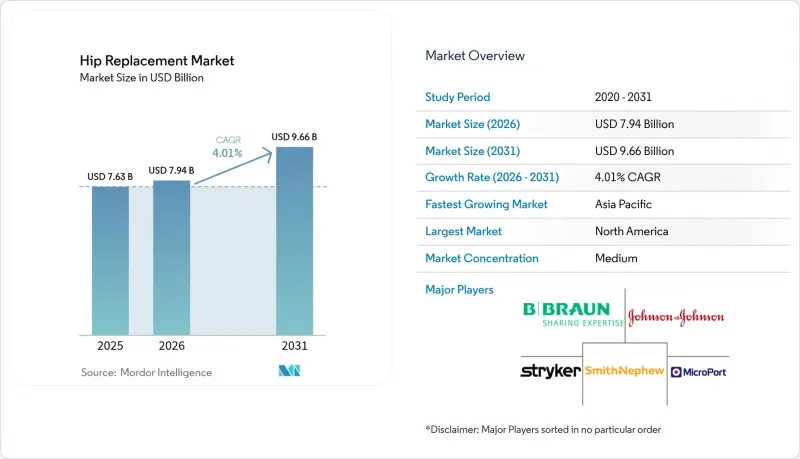
에 의하면, 2026년 고관절 치환술 시장 규모는 79억 4,000만 달러로 추정되고 2025년 76억 3,000만 달러에서 확대해, 2031년에는 96억 6,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 4.01%로 성장할 것으로 전망됩니다.
본 보고서는 제품별(인공 고관절 전치환술, 고관절 표면 치환술, 고관절 재치환술 등), 고정 방식별(시멘트 고정식 등),재질별(금속 대 폴리에틸렌, 세라믹 대 폴리에틸렌 등), 최종 사용자별(병원, 정형외과 센터 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 고관절 치환술 시장 동향 및 인사이트
퇴행성 관절염 유병률 증가
퇴행성 관절염은 전 세계적으로 6억 6,500만 명에게 영향을 미치고 있으며, 이 수치는 인구 고령화와 비만율 상승에 따라 계속 증가하고 있습니다. 고관절 질환의 진행은 특히 빠르며, 기존 베어링은 20년 생존율이 94.1%에 달하는 첨단 OXINIUM 표면과 비교하여 재치환 위험이 35% 더 높습니다. 지역별로는 동아시아 및 남아시아의 부담이 가장 크며, 체질량 지수(BMI)와 같은 수정 가능한 위험 요인이 관련 신체 장애의 5분의 1을 차지하고 있습니다. 유전체 연구에 따르면 900개 이상의 유전자좌가 이 질환과 관련이 있는 것으로 밝혀졌으며, 관련성이 시사되는 유전자의 10%는 기존 치료법과 관련이 있어 수술을 미룰 수 있는 약물 치료의 가능성이 시사되고 있습니다. 이처럼 고령화와 대사성 질환의 동반 발생으로 인해 수술 수요가 수술 수용 능력을 계속해서 초과하고 있습니다.
고령화 및 비만 인구 증가
2030년까지 미국에서만 외과의사들은 63만 5,000건의 초회 인공 고관절 치환술을 예상하고 있으며, 이는 현재 대비 171% 증가한 수치입니다. 한편, 전 세계 수술 건수는 2060년까지 123만 건을 넘어설 가능성이 있습니다. 체질량지수(BMI)가 높으면 수동으로 임플란트를 삽입하기 어려워지지만, 로봇 시스템은 이러한 문제를 해결하여 BMI가 24 kg/m²를 초과하는 환자의 경우 고관절의 정확한 위치 설정을 향상시킵니다. 고소득 국가에서는 수술 건수 증가가 가장 두드러지는 반면, 신흥 시장에서는 특히 개별 임플란트가 필요한 더 복잡한 고관절 해부학적 구조를 가진 여성 환자를 대상으로 적시에 치료를 제공하는 데 필요한 역량 부족에 직면해 있습니다.
임플란트 및 수술 비용 부담
인공 고관절 전치환술에 대한 메디케어 환급액은 수술 건수가 44.17% 증가했음에도 불구하고, 2013년부터 2021년 사이에 44.04% 감소하여 의료 제공업체의 이익률을 압박하고 있습니다. 미국 고관절·무릎 관절 외과 의사 협회는 2025년에 시행된 추가 삭감에 대응하기 위해 의회에 청원을 제기했습니다. 지역 간 격차는 현저합니다. 북동부 지역은 평균 지급액이 1,731달러에 달하지만, 감소율은 가장 높습니다. 티타늄 등 공급망의 원자재 비용은 현재 정형외과용 임플란트 제조 원가의 최대 20%를 차지하고 있으며, 지정학적 긴장이 가격 변동을 더욱 확대시키고 있습니다. 이러한 요인들로 인해 비용에 민감한 지역의 수술 건수가 감소할 위험이 있으며, 의료 접근성 불평등이 더욱 심화될 우려가 있습니다.
부문별 분석
인공 고관절 전치환술은 2025년 매출의 62.85%를 차지하며, 모든 연령대에서 임상적 주류 치료법으로서의 위상을 재확인했습니다. 이 제품의 인공 고관절 시장 규모는 2025년에 47억 9,000만 달러에 달할 것으로 예상되며, 탈구 위험을 줄여주는 듀얼 모빌리티 컵(dual mobility cup)과 같은 설계 개선이 진행됨에 따라 지속적인 성장을 이어가고 있습니다. 고관절 표면 치환술은 현재로서는 틈새 시장이지만, 장기적인 임플란트 적합성을 추구하는 활동적인 환자들 사이에서 ‘골 보존’이라는 개념이 확산됨에 따라 연평균 성장률(CAGR) 6.57%로 확대되고 있습니다.
로봇 보조 재치환 수술의 성장세는 재치환 건수 증가를 뒷받침하고 있습니다. 스트라이커(Stryker)사의 ‘Mako 4’는 알고리즘 기반 가이드를 도입하여 비구 제거 및 재삽입 워크플로우를 간소화하고 있습니다. 중증 변형에 대해 FDA 승인을 받은 리버스형 인공 고관절과 같은 관련 혁신 기술은 고액의 보험 급여가 기대되는 맞춤형 솔루션으로 제품 파이프라인이 전환되고 있음을 보여줍니다.
2025년에는 시멘트리스 구조물이 매출의 56.90%를 차지했으며, 외과의들이 젊은 층이나 활동적인 환자층에게 생체 고정 방식을 선호하는 경향에 따라 관련 인공 고관절 치환술 시장 점유율은 더욱 상승할 것으로 전망됩니다. 다공성이 높은 티타늄 및 탄탈륨은 조기 골 침투를 촉진하여 대퇴골 경부 골절의 비유합률은 2%에 그치지만, 표준 나사를 사용할 경우 이 비율은 현저히 높아집니다. 시멘트 고정식 스템은 골다공증 뼈에 여전히 필수적이며, 복잡한 해부학적 구조의 경우 두 원리를 융합한 하이브리드 수술법이 사용되고 있습니다.
적층 가공 기술은 시멘트리스 제품의 혁신을 가속화하고 있습니다. 토폴로지 최적화된 격자 구조는 임플란트의 강성을 낮추고 하중을 균일하게 분산시켜 스트레스 쉴드를 억제하며, 기능적 수명을 연장합니다. 스미스 앤 네퓨(Smith & Nephew)사의 ‘CATALYSTEM’ 스템은 전방 접근 수술에 최적화되어 있으며, 수술실 소요 시간을 단축하도록 설계된 대표적인 사례로, 이는 처리 능력이 뛰어난 ASC(외래수술센터(ASC))에서 매우 중요한 지표가 됩니다.
지역별 분석
북미는 2025년 매출의 37.20%를 차지하며, 로봇 기술, AI를 활용한 수술 전 계획, 그리고 첨단 베어링 표면의 조기 도입을 통해 기술적 리더십을 유지했습니다. 이 지역의 고관절 치환술 시장 규모는 임상적 유효성이 입증된 업그레이드에 대한 유리한 보험 환급에 힘입어 2025년에는 28억 4,000만 달러에 달했습니다. 유럽에서는 성숙한 보험 환경이 꾸준한 성장을 뒷받침하고 있지만, 비용 절감의 필요성으로 인해 고가 의료기기의 보급 속도는 둔화되고 있습니다.
아시아태평양은 성장의 원동력으로 부상하고 있으며, 중국과 인도가 임플란트 가격을 절반으로 낮추고 수술 건수 증가를 촉진하는 조달 프로그램을 시행하고 있어 2031년까지 연평균 성장률(CAGR) 5.74%를 기록할 전망입니다. 중국의 수술 건수는 2011년 16만 8,040건에서 2019년 57만 7,153건으로 급증했으며, 국산 임플란트가 수술 건수의 4분의 1 가까이 차지했습니다. 인도에서는 의료 관광 유입과 병원 투자의 뒷받침을 받아 선택적 관절 치환술 분야에서 연간 두 자릿수 성장이 예상됩니다.
남미 및 중동 및 아프리카에서는 잠재적인 가능성이 보입니다. 브라질에서는 2050년까지 하지 인공관절 치환술이 3만 9,270건에 달할 것으로 예측되지만, 현재 보급률은 10만 명당 8.01건으로 세계 평균을 크게 밑돌고 있습니다. 생산 능력 확대의 핵심은 정형외과 전문의 양성 및 의료기기 비용을 상승시키고 있는 수입 관세의 완화입니다. 탄화수소 수입이 풍부한 걸프협력회의(GCC) 회원국들은 미국 및 유럽산 시스템을 점점 더 많이 수입하는 한편, 관절 전문 연구소에 자금을 지원함으로써 장기적으로는 현지 생산을 위한 기반을 마련하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the hip arthroplasty market size in 2026 is estimated at USD 7.94 billion, growing from 2025 value of USD 7.63 billion with 2031 projections showing USD 9.66 billion, growing at 4.01% CAGR over 2026-2031.
This report is Segmented by Product (Total Hip Replacement, Hip Resurfacing, Hip Revision, and More), Fixation Type (Cemented, and More), Material (Metal-On-Polyethylene, Ceramic-On-Polyethylene, and More), End User (Hospitals, Orthopedic Centers, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Hip Replacement Market Trends and Insights
Growing Prevalence of Osteoarthritis
Osteoarthritis affects 606.5 million people worldwide, a figure that continues to climb as populations age and obesity rates rise. Hip disease progression is particularly aggressive, and traditional bearings show a 35% higher revision risk than advanced OXINIUM surfaces that deliver 94.1% twenty-year survivorship. Regional burden is heaviest in East and South Asia, yet modifiable risks such as body-mass-index contribute one-fifth of related disability. Genomic studies link more than 900 loci to disease, and 10% of implicated genes map to existing therapies, hinting at pharmacologic options that could postpone surgery. The convergence of aging and metabolic disorders thus keeps procedure demand ahead of surgical capacity.
Rising Geriatric & Obese Population
By 2030, surgeons in the United States alone anticipate 635,000 primary hip replacements-up 171% from today-while global volumes may top 1.23 million by 2060. Higher body-mass-index complicates manual component positioning; robotic systems correct these challenges and boost acetabular accuracy in patients with BMI > 24 kg/m2. High-income nations carry the steepest caseload growth, but emerging markets battle capacity gaps that restrict timely care, particularly for women who present with more complex hip anatomy requiring personalized implants.
High Implant & Procedure Cost Burden
Medicare reimbursement for total hip arthroplasty slid 44.04% between 2013 and 2021 even as volumes rose 44.17%, squeezing provider margins. The American Association of Hip and Knee Surgeons has petitioned Congress to counter another scheduled cut for 2025. Regional spreads are stark: the Northeast commands USD 1,731 average payment yet suffered the steepest percentage decline. Supply chain inputs such as titanium now represent up to 20% of orthopedic manufacturing cost bases, and geopolitical tension magnifies volatility. These factors risk curtailing uptake in cost-sensitive zones and widening inequity in care access.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Robotic-Assisted Hip Arthroplasty
- Shift Toward Outpatient & ASC-Based Procedures
- Device Recalls & Metal-On-Metal Litigation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Total hip replacement accounted for 62.85% of 2025 revenue, reaffirming its status as the clinical workhorse across age cohorts. The hip arthroplasty market size for this product reached USD 4.79 billion in 2025 and continues to grow in tandem with incremental design refinements, such as dual-mobility cups that mitigate dislocation risk. Hip resurfacing, although presently niche, is advancing at 6.57% CAGR as bone-preserving philosophy gains traction among active patients seeking long-term implant compatibility.
Momentum in robotic revision surgery underscores rising revision volumes: Stryker's Mako 4 introduces algorithmic guidance that simplifies acetabular explant and re-implant workflows. Adjacent innovations, like FDA-authorized reverse-hip constructs for severe deformity, illustrate the pipeline's tilt toward personalized solutions commanding premium reimbursement.
Cementless constructs captured 56.90% revenue in 2025, and associated hip arthroplasty market share is forecast to climb further as surgeons favor biologic fixation for younger, active cohorts. Highly porous titanium and tantalum buttress early bone infiltration, yielding 2% nonunion in femoral neck fractures compared to markedly higher rates with standard screws. Cemented stems remain indispensable for osteoporotic bone, and hybrid techniques blend both principles for complex anatomy.
Additive manufacturing accelerates cementless innovation: topology-optimized lattices reduce implant stiffness and distribute load uniformly, curbing stress shielding and extending functional lifespan. Smith+Nephew's CATALYSTEM stem, optimized for anterior approach surgery, typifies designs that shorten OR time-a critical metric in high-throughput ASC settings.
Complete Report Scope:
- By Product
- Total Hip Replacement
- Hip Resurfacing
- Hip Revision
- Other Products
- By Fixation Type
- Cemented
- Cementless
- Hybrid
- By Material (Bearing Couple)
- Metal-on-Polyethylene
- Ceramic-on-Polyethylene
- Ceramic-on-Ceramic
- Metal-on-Metal
- By End User
- Hospitals
- Orthopedic Centers
- Ambulatory Surgical Centers
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 37.20% of 2025 revenue and retains technology leadership through early adoption of robotics, AI planning, and advanced bearing surfaces. The hip arthroplasty market size for the region is estimated at USD 2.84 billion in 2025, underpinned by favorable reimbursement for clinically evidenced upgrades. Europe's mature payer environment sustains steady growth, though cost-containment imperatives temper premium device penetration speed.
Asia-Pacific emerges as the expansion engine, registering 5.74% CAGR through 2031 as China and India execute procurement programs that halve implant prices and stimulate surgical uptake. China's case volume jumped from 168,040 in 2011 to 577,153 in 2019, while domestic implants captured nearly one-quarter of procedures. India, buoyed by medical-tourism inflows and hospital investment, anticipates double-digit annual growth in elective joint replacement.
South America and the Middle East & Africa present latent potential: Brazil projects 39,270 lower-limb arthroplasties by 2050, yet current penetration is 8.01 per 100,000-far below global averages. Capacity expansion hinges on training orthopedic surgeons and easing import tariffs that elevate device cost. Gulf Cooperation Council states, flush with hydrocarbon revenue, increasingly import U.S. and European systems while funding specialty joint institutes, setting the stage for localized manufacturing over the long term.
- Zimmer Biomet
- Stryker
- Johnson & Johnson
- Smiths Group
- B. Braun
- MicroPort
- Enovis
- Exactech
- Corin Group
- Wright Medical Group
- Integra LifeSciences
- Globus Medical
- Conformis
- Medacta Group
- LimaCorporate
- Bioimpianti
- Arthrex
- Mathys Ltd Bettlach
- United Orthopedic
- JRI Orthopaedics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Prevalence of Osteoarthritis
- 4.2.2 Rising Geriatric & Obese Population
- 4.2.3 Adoption of Robotic-Assisted Hip Arthroplasty
- 4.2.4 3-D Printed Porous Implants Enabling Bone In-Growth
- 4.2.5 Shift Toward Outpatient & ASC-Based Procedures
- 4.2.6 China-India Price-Volume Tenders Expanding Access
- 4.3 Market Restraints
- 4.3.1 High Implant & Procedure Cost Burden
- 4.3.2 Device Recalls & Metal-On-Metal Litigation
- 4.3.3 Reimbursement Compression in Mature Markets
- 4.3.4 Supply-Chain Tightness for Titanium & Cobalt
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Total Hip Replacement
- 5.1.2 Hip Resurfacing
- 5.1.3 Hip Revision
- 5.1.4 Other Products
- 5.2 By Fixation Type
- 5.2.1 Cemented
- 5.2.2 Cementless
- 5.2.3 Hybrid
- 5.3 By Material (Bearing Couple)
- 5.3.1 Metal-on-Polyethylene
- 5.3.2 Ceramic-on-Polyethylene
- 5.3.3 Ceramic-on-Ceramic
- 5.3.4 Metal-on-Metal
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Orthopedic Centers
- 5.4.3 Ambulatory Surgical Centers
- 5.4.4 Other End Users
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Zimmer Biomet
- 6.3.2 Stryker Corporation
- 6.3.3 Johnson & Johnson (DePuy Synthes)
- 6.3.4 Smith & Nephew plc
- 6.3.5 B. Braun SE
- 6.3.6 MicroPort Scientific Corporation
- 6.3.7 Enovis (DJO Global)
- 6.3.8 Exactech Inc.
- 6.3.9 Corin Group
- 6.3.10 Wright Medical Group N.V.
- 6.3.11 Integra LifeSciences
- 6.3.12 Globus Medical
- 6.3.13 Conformis
- 6.3.14 Medacta Group
- 6.3.15 LimaCorporate
- 6.3.16 Bioimpianti
- 6.3.17 Arthrex
- 6.3.18 Mathys Ltd Bettlach
- 6.3.19 United Orthopedic
- 6.3.20 JRI Orthopaedics
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


