

|
시장보고서
상품코드
2122218
백업 전원 시스템 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Backup Power Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
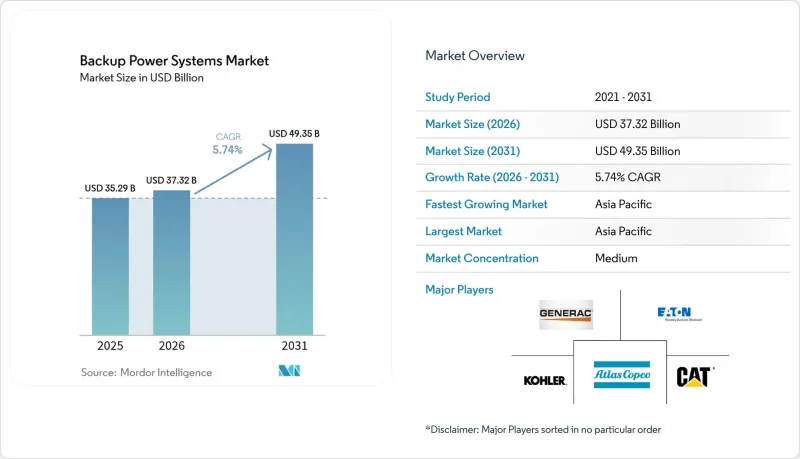
에 따르면 백업 전원 시스템 시장 규모는 2025년에 352억 9,000만 달러로 평가되며, 2026년 373억 2,000만 달러에서 2031년까지 493억 5,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 5.74%에 달할 전망입니다.
이 보고서는 기술별(디젤 발전기, 가스 발전기, 축전지 시스템 등), 출력 정격별(50KVA 이하, 51-280KVA, 501-2,000KVA 등),용도(예비/비상용 전원, 피크 부하 완화 및 부하 관리 등), 최종사용자(산업·제조, 데이터센터 및 IT 등), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다.
전 세계 백업 전원 시스템 시장의 동향 및 인사이트
정전 발생 빈도와 경제적 손실
전력 회사는 빈도가 증가하고 심각해지는 기상 요인에 의한 정전에 직면하고 있으며, 2000-2023년까지 미국에서 발생한 대규모 정전의 80%는 기상 관련이었습니다. 장시간 정전, 특히 다운타임이 시간당 10만 달러를 초과하는 경우, 기업은 백업 용량을 사업 운영의 보험으로 간주하고 있습니다. 2021년 겨울 폭풍을 계기로 텍사스주에서 마이크로그리드 건설이 급증했으며, 프로젝트 비용은 1MW당 200만-500만 달러에 달했습니다. 그 결과, 투자는 며칠 동안 지속되는 정전을 견딜 수 있는 대용량 시스템에 집중되고 있습니다. 노후화된 송전망의 현대화는 신뢰성 확보에 대한 수요를 따라가지 못하고 있으며, 2030년까지도 분산형 자산은 중요한 리스크 헤지 수단으로 남아 있을 것입니다. 이러한 상황들이 맞물려 백업 전원 시스템 시장의 성장을 촉진하고 있습니다.
하이퍼스케일 및 엣지 데이터센터의 확대
전 세계 데이터센터의 전력 수요는 2030년까지 미국에서만 35기가와트에 달할 전망이며, 그 성장의 60%를 하이퍼스케일러가 차지하고 있습니다. 현재 단일 캠퍼스에서 1기가와트 이상의 백업 용량이 요구되고 있으며, 이는 기존의 시설 기준을 훨씬 상회하는 수준입니다. 엣지 배포로 인해 노드 수가 두 배로 증가하고 있으며, 10밀리초 미만의 지연 시간을 보장하기 위해 각 노드에서 50-500킬로와트의 대기 전력 공급이 필요합니다. 배터리 시스템은 조용한 작동과 즉각적인 전환이 가능하다는 점에서 지지를 얻고 있습니다. 이는 엄격한 소음 규제가 적용되는 도시 지역에서 필수적인 요건입니다. 재생 가능 에너지를 활용한 전력 구매 계약(PPA) 도입으로 인해 간헐성이 발생함에 따라 AI 워크로드를 보호하기 위한 디젤·배터리 하이브리드 시스템 개발이 진행되고 있으며, 이로 인해 백업 전원 시스템 시장에 대한 견고한 수요가 확고해지고 있습니다.
변동이 심한 디젤 연료비와 높은 운영 비용
연료비는 디젤 발전 세트의 수명 주기 운영 비용의 최대 70%를 차지하며, 가격 변동은 예산 계획의 확실성을 저해합니다. 일본 데이터센터 협의회(JDCC)는 장기적인 비상 사태시 발전기의 동시 가동으로 인해 지역 디젤 연료 공급망에 부담이 가해질 수 있다고 경고하고 있습니다. 탄소세로 인해 연료 납품 가격이 상승하여 배터리에 비해 총 소유 비용이 높아집니다. 도심 지역의 저장 규제로 인해 부지내 저장량에 상한선이 설정되는 경우가 많으며, 배송 빈도가 증가함에 따라 물류 리스크가 커집니다. 이러한 요인들이 디젤 도입을 억제하고, 백업 전원 시스템 시장의 성장률을 둔화시키고 있습니다.
부문 분석
백업 전원 시스템 시장에서 디젤 발전기 시장 규모는 39.74%의 점유율을 차지하고 있지만, BESS(배터리 에너지 저장 시스템)는 57억 6,000만 달러 규모의 시장을 형성하고 있으며, 2031년까지 연평균 성장률(CAGR) 13.1%로 확대될 것으로 예측됩니다. 디젤은 확립된 연료 물류 체계 덕분에 외딴 지역의 광산이나 중공업 분야에서 여전히 필수적이지만, 배출 규제가 강화됨에 따라 데이터센터 및 의료 시설 운영자들은 리튬이온 배터리나 신기술인 나트륨이온 배터리로의 전환을 강요받고 있습니다. 천연가스 파이프라인이 전력망 정전시 장시간 가동을 가능하게 함에 따라 가스 발전기를 이용한 백업 전원 시스템의 시장 점유율은 견고한세를 유지하고 있습니다. UPS 플랫폼은 IT 랙을 수 초에서 수 분 동안 온라인 상태로 유지하여, 더 대규모 설비가 가동될 때까지 그 공백을 메우고 있습니다. 태양광발전, 배터리, 디젤을 결합한 하이브리드 시스템은 독립형 마이크로그리드에서 연료 소비량을 35% 절감하여 프로젝트의 경제성을 높이는 동시에 탄소 배출 감축 약속도 이동하고 있습니다. 캘리포니아주 데이터센터의 연료 전지 시범 프로젝트는 수소 공급망이 성숙해졌을 때의 미래상을 보여주고 있습니다.
공급업체 기반의 확대로 인해 BESS 시스템 비용은 연간 8-10% 감소하고 있으며, 2 MWh를 초과하는 설비는 현재 엣지 캠퍼스에서 4시간의 자율 가동 목표를 충족하고 있습니다. 기술 공급업체들은 AI 컨트롤러를 통합하여 배터리를 순환시키고 피크 부하를 완화함으로써, 정전시 이외에도 동일한 하드웨어로 수익을 창출하고 있습니다. 이러한 이중 가치 모델은 투자 수익률을 높이고, 백업 전원 시스템 시장 전반에 걸친 도입을 가속화하고 있습니다.
2025년에는 501-2,000 kVA급 유닛이 중규모 데이터 홀, 병원, 경공업 시설에 적합하므로 백업 전원 시스템 시장 점유율의 31.28%를 차지했습니다. 이 부문의 연평균 성장률(CAGR) 전망치는 7.43%로, 휴대용 발전기가 몇 시간 분량의 중요 부하만을 충당하는 소규모 주거용 등급보다 높은 성장세를 보이고 있습니다. 표준화된 1 MW 단위 블록을 통해 사업자는 1 MW 단위로 확장이 가능하며, 맞춤형 구축에 비해 설계 리드타임을 25% 단축할 수 있습니다. 2,000 kVA를 초과하는 패키지는 유틸리티 규모의 발전소 및 석유화학 단지에서 주류를 이루고 있지만, 수주 주기는 불규칙하며 메가 프로젝트의 승인 여부에 좌우됩니다.
280kVA 미만의 부문은 통신 타워나 소매점에 이용되고 있으며, 현장 유지보수를 줄이기 위해 납산 배터리를 대신해 인산철리튬 배터리가 채택되고 있습니다. 각 공급업체는 원격 진단 기능을 통합하여, 한 명의 기술자가 수백 곳에 분산된 설비를 관리할 수 있게 됨에 따라 운영 비용 절감과 백업 전원 시스템 시장의 규모 확대가 촉진되고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 39.12%를 차지하며, 중국, 인도, 일본이 하이퍼스케일 데이터센터와 스마트 팩토리의 생산 능력을 확대하고 있는 덕분에 이 지역의 연평균 성장률(CAGR) 6.18%는 여전히 각 지역 중 최고 수준을 유지하고 있습니다(CBRE.COM). 중국의 정책에 따라 현지 배터리 공급업체들은 생산 확대를 강요받고 있으며, 이는 지역 전체의 비용을 낮추고 추가적인 보급을 촉진하고 있습니다. 인도의 전자기기용 ‘생산 연계형 인센티브 제도’는 신규 팹 건설을 촉진하고 있으며, 이 모든 시설에는 높은 신뢰성을 갖춘 백업 시스템이 요구됩니다. 일본의 전력 회사는 데이터센터 클러스터와 관련된 송전망 강화에 1,500억 엔(10억 4,000만 달러)을 투자하겠다고 약속했으며, 이에 따라 병렬 백업 시스템의 수주가 확대되고 있습니다.
북미는 2위를 차지하고 있으며, 미국 클라우드 제공업체의 지출과 고객사 1곳당 연간 평균 7시간 이상에 달하는 기상 요인에 의한 정전 위험이 이를 주도하고 있습니다. 이 지역의 백업 전원 시스템 시장 규모는 ‘인플레이션 억제법(Inflation Reduction Act)’에 따른 배터리 세액 공제의 혜택을 받고 있으며, 피크 부하 감축용 리튬이온 배터리 팩의 조달이 증가하고 있습니다. 캐나다의 외딴 광산 지역에서는 여전히 디젤이 주류를 이루고 있지만, 수소·디젤 듀얼 연료 사양의 시범 운영을 통해 배출량을 15% 감축하는 것을 목표로 하고 있습니다.
유럽에서는 재생 가능 에너지의 보급에 따라 간헐성 위험이 높아지는 가운데, 시장이 꾸준히 확대되고 있습니다. 독일의 송전망에서는 2024년에 6.4 TWh의 풍력발전이 제한됨에 따라 공장에서는 예비 전원으로 기능하는 열병합 발전 엔진의 도입이 진행되고 있습니다. 런던과 파리의 초저배출 구역에서는 스모그 경보가 발령될 때 구형 디젤 발전기의 사용이 금지되어 있으며, 이는 BESS(배터리 에너지 저장 시스템)의 개조를 촉진하고 있습니다. 남유럽에서는 산불 시즌이 장기화되고 있으며, 통신 사업자들은 저소음 운영 관련 조례를 충족하는 컨테이너형 태양광발전 및 배터리 저장 솔루션 도입을 추진하고 있습니다.
중동 및 아프리카에서는 데이터 현지화 의무화가 호재로 작용하여 리야드, 두바이, 나이로비에 새로운 Tier III 코로케이션 사이트가 잇달아 생겨나고 있습니다. 주변 온도가 높으면 배터리 수명이 단축되므로 초기 구축 단계에서는 가스와 배터리를 결합한 하이브리드 솔루션이 종종 우선적으로 선택되고 있습니다. 남미에서는 전력망에 대한 투자가 수요 증가를 따라가지 못하고 있으며, 가뭄으로 인한 수력 발전 부족시 디젤 연료 수입이 급증함에 따라 발전기 수주가 호조를 보이고 있습니다. 이러한 동향들이 맞물려 백업 전원 시스템 시장 전체에 걸쳐 성장이 폭넓게 분산되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the backup power systems market size was valued at USD 35.29 billion in 2025 and estimated to grow from USD 37.32 billion in 2026 to reach USD 49.35 billion by 2031, at a CAGR of 5.74% during the forecast period (2026-2031).
This report is Segmented by Technology (Diesel Generators, Gas Generators, Battery Energy Storage Systems, and More), Power Rating (Up To 50 KVA, 51 To 280 KVA, 501 To 2, 000 KVA, and More), Application (Standby/Emergency Power, Peak Shaving and Load Management, and More), End-User (Industrial and Manufacturing, Data Centres and IT, and More), and Geography (North America, Europe, Asia-Pacific, and More).
Global Backup Power Systems Market Trends and Insights
Grid-Outage Frequency & Economic Losses
Utilities are facing more frequent and severe-weather failures, and 80% of major U.S. outages between 2000 and 2023 were weather-related. Prolonged blackouts prompt enterprises to view backup capacity as operational insurance, particularly when downtime exceeds USD 100,000 per hour. Texas microgrid construction surged after the 2021 winter storm, with projects costing USD 2 million-USD 5 million per MW. Investments therefore favor higher-capacity systems that bridge multi-day disruptions. The modernization of aging grids trails behind reliability needs, so distributed assets remain a critical hedge through 2030. These conditions collectively drive the growth of the backup power systems market.
Expansion of Hyperscale & Edge Data-Centres
Global data-center power demand is on track to reach 35 GW in the United States alone by 2030, with hyperscalers accounting for 60% of that growth. Single campuses now request 1 GW or more of backup capacity, dwarfing previous facility norms. Edge roll-outs multiply the node count, each demanding 50-500 kW of standby supply to guarantee sub-10-millisecond latency. Battery systems gain favor for their silent operation and instantaneous switchover, a must in urban zones with strict noise limits. Renewable-energy power-purchase agreements introduce intermittency, prompting the development of hybrid diesel-battery stacks to protect AI workloads, thereby solidifying robust demand for the backup power systems market.
Volatile Diesel-Fuel Costs & High OPEX
Fuel accounts for up to 70% of a diesel set's lifetime operating expense, and price swings erode budgeting certainty. The Japan Data Center Council cautioned that simultaneous generator runs could strain regional diesel supply chains during lengthy emergencies.Carbon levies inflate delivered fuel prices, raising the total cost of ownership relative to batteries. Storage regulations in city centers often cap on-site volumes, forcing more frequent deliveries that raise logistics risk. These factors temper diesel uptake and moderate the growth rate of the backup power systems market.
Other drivers and restraints analyzed in the detailed report include:
- 24 X 7 Automated Industrial Operations
- Regulatory Mandates for Critical Facilities
- Substitution by Long-Duration BESS
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The backup power systems market size for diesel generators accounted for a 39.74% share, whereas BESS captured USD 5.76 billion and is projected to advance at a 13.1% CAGR through 2031. Diesel's entrenched fuel logistics keep it essential for remote mines and heavy industry, yet emissions caps motivate data-center and healthcare operators to pivot toward lithium-ion and emerging sodium-ion packs. The backup power systems market share for gas generators remains resilient because natural-gas pipelines offer extended runtimes during grid failures. UPS platforms keep IT racks online for seconds to minutes, bridging the gap until larger assets engage. Hybrid sets that blend PV, batteries, and diesel cut fuel consumption by 35% on islanded microgrids, improving project economics while satisfying carbon-reduction pledges. Fuel-cell pilots in California data centers illustrate future pathways if hydrogen supply chains mature.
A widening supplier base is reducing BESS system costs by 8-10% annually, and installations above 2 MWh now meet four-hour autonomy targets for edge campuses. Technology vendors embed AI controllers to cycle batteries for peak shaving, thereby monetizing the same hardware outside outage events. That dual-value model lifts return on investment and accelerates adoption across the backup power systems market.
Units rated 501-2,000 kVA captured 31.28% of the backup power systems market share in 2025, due to their suitability for mid-tier data halls, hospitals, and light-industrial campuses. Their 7.43% CAGR outlook exceeds that for smaller residential classes, where portable power stations satisfy only critical loads for a few hours. Standardized 1 MW blocks enable operators to scale in 1 MW increments, reducing engineering lead times by 25% compared to bespoke builds. Above-2,000 kVA packages dominate utility-scale stations and petrochemical complexes; however, order cycles are lumpy and tied to the approval of megaprojects.
Segments below 280 kVA serve telecom towers and retail stores, with lithium-iron-phosphate batteries replacing lead-acid banks to curb field maintenance. Vendors integrate remote diagnostics, allowing a single technician to oversee hundreds of dispersed installations, thereby lowering operating costs and supporting volume growth in the backup power systems market.
Complete Report Scope:
- By Technology
- Diesel Generators
- Gas Generators
- Uninterruptible Power Supply (UPS)
- Battery Energy Storage Systems (BESS)
- Hybrid Power Solutions
- Fuel-Cell Backup Systems
- Portable Power Stations
- By Power Rating
- Up to 50 kVA
- 51 to 280 kVA
- 281 to 500 kVA
- 501 to 2,000 kVA
- Above 2,000 kVA
- By Application
- Standby/Emergency Power
- Prime/Continuous Power
- Peak Shaving and Load Management
- Off-Grid and Remote Power
- By End-User
- Residential
- Commercial (Retail, Offices, Hospitality)
- Industrial and Manufacturing
- Data Centres and IT
- Healthcare Facilities
- Telecom Towers
- Utilities and Energy
- Government and Defence
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific captured 39.12% of 2025 revenue, and its 6.18% CAGR remains the highest among regions as China, India, and Japan add both hyperscale data halls and smart-factory capacity CBRE.COM. Chinese policy drives local battery suppliers to ramp production, which lowers regional costs and fuels further adoption. India's Production-Linked Incentive scheme for electronics stimulates the construction of new fabs, all of which require high-reliability backup. Japan's utilities pledge JPY 150 billion (USD 1.04 billion) in grid reinforcements tied to data-center clusters, spurring parallel backup system orders.
North America ranks second, driven by US cloud-provider spending and weather-related outage exposure that averages over 7 hours per customer annually. The backup power systems market size for the region benefits from tax credits on battery storage under the Inflation Reduction Act, tipping procurement toward lithium packs for peak shaving. Canada's remote mining belts still favor diesel, but pilot hydrogen-diesel dual-fuel rigs aim to cut emissions 15%.
Europe advances steadily as renewable penetration lifts intermittency risks. Germany's grid had 6.4 TWh of curtailed wind power in 2024, prompting factories to adopt combined heat-and-power engines that also serve as standby units. Ultra-Low-Emission Zones in London and Paris ban older diesel sets during smog alerts, catalyzing BESS retrofits. Southern Europe's wildfire seasons are lengthening, prompting telecoms to deploy containerized solar-battery solutions that meet silent-operation bylaws.
The Middle East and Africa benefit from data localization mandates that seed new Tier III colocation sites in Riyadh, Dubai, and Nairobi. High ambient temperatures shorten battery life, so hybrid gas-plus-battery solutions are often the preferred choice in initial builds. South America's grid investments trail demand growth, and diesel imports swell during drought-linked hydro-power deficits, keeping generator orders brisk. Together, these dynamics distribute growth widely across the backup power systems market.
- Caterpillar Inc.
- Cummins Inc.
- Generac Holdings Inc.
- Kohler Co.
- Eaton Corporation plc
- Schneider Electric SE
- ABB Ltd.
- Vertiv Group Corp.
- Mitsubishi Heavy Industries Ltd.
- Rolls-Royce Holdings plc (MTU)
- Siemens AG
- Honda Motor Co., Ltd.
- Yanmar Holdings Co., Ltd.
- Atlas Copco AB
- Doosan Portable Power
- Delta Electronics Inc.
- Huawei Technologies Co. Ltd.
- Toshiba Corporation
- Perkins Engines Co. Ltd.
- FG Wilson
- Briggs & Stratton LLC
- Goal Zero LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Grid-outage frequency & economic losses
- 4.2.2 Expansion of hyperscale & edge data-centres
- 4.2.3 24 X 7 automated industrial operations
- 4.2.4 Regulatory mandates for critical facilities
- 4.2.5 Off-grid EV fast-charging corridors
- 4.2.6 AI-driven predictive maintenance adoption
- 4.3 Market Restraints
- 4.3.1 Volatile diesel-fuel costs & high OPEX
- 4.3.2 Substitution by long-duration BESS
- 4.3.3 Capital-intensive large-scale installs
- 4.3.4 Urban low-noise/ultra-low-emission zoning
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Diesel Generators
- 5.1.2 Gas Generators
- 5.1.3 Uninterruptible Power Supply (UPS)
- 5.1.4 Battery Energy Storage Systems (BESS)
- 5.1.5 Hybrid Power Solutions
- 5.1.6 Fuel-Cell Backup Systems
- 5.1.7 Portable Power Stations
- 5.2 By Power Rating
- 5.2.1 Up to 50 kVA
- 5.2.2 51 to 280 kVA
- 5.2.3 281 to 500 kVA
- 5.2.4 501 to 2,000 kVA
- 5.2.5 Above 2,000 kVA
- 5.3 By Application
- 5.3.1 Standby/Emergency Power
- 5.3.2 Prime/Continuous Power
- 5.3.3 Peak Shaving and Load Management
- 5.3.4 Off-Grid and Remote Power
- 5.4 By End-User
- 5.4.1 Residential
- 5.4.2 Commercial (Retail, Offices, Hospitality)
- 5.4.3 Industrial and Manufacturing
- 5.4.4 Data Centres and IT
- 5.4.5 Healthcare Facilities
- 5.4.6 Telecom Towers
- 5.4.7 Utilities and Energy
- 5.4.8 Government and Defence
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 NORDIC Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Cummins Inc.
- 6.4.3 Generac Holdings Inc.
- 6.4.4 Kohler Co.
- 6.4.5 Eaton Corporation plc
- 6.4.6 Schneider Electric SE
- 6.4.7 ABB Ltd.
- 6.4.8 Vertiv Group Corp.
- 6.4.9 Mitsubishi Heavy Industries Ltd.
- 6.4.10 Rolls-Royce Holdings plc (MTU)
- 6.4.11 Siemens AG
- 6.4.12 Honda Motor Co., Ltd.
- 6.4.13 Yanmar Holdings Co., Ltd.
- 6.4.14 Atlas Copco AB
- 6.4.15 Doosan Portable Power
- 6.4.16 Delta Electronics Inc.
- 6.4.17 Huawei Technologies Co. Ltd.
- 6.4.18 Toshiba Corporation
- 6.4.19 Perkins Engines Co. Ltd.
- 6.4.20 FG Wilson
- 6.4.21 Briggs & Stratton LLC
- 6.4.22 Goal Zero LLC
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


