

|
시장보고서
상품코드
2122222
경화기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Light Weapons - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 경화기 시장 규모는 2025년에 155억 달러로 평가되며, 2026년 162억 6,000만 달러에서 2031년까지 206억 4,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 4.89%에 달할 전망입니다.

이 보고서는 유형(중기관총(HMG), 수류탄 및 유탄 발사기, 박격포 등), 기술(유도식 및 비유도식), 플랫폼(육상, 항공, 해군),최종사용자(육군, 특수부대 등), 소재(강철 및 특수 합금, 폴리머 복합재 등), 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 경무기 시장의 동향 및 인사이트
지정학적 긴장을 배경으로 한 국방 예산 확대
나토(NATO) 회원국들이 러시아의 우크라이나 침공에 대응한 결과, 2024년 유럽의 군사 지출은 17% 증가하여 6,930억 달러에 달했습니다. 폴란드는 2025년까지 국방비를 GDP의 4.7%로 끌어올리는 한편, 독일이 설립한 1,000억 유로(1,090억 달러) 규모의 특별 기금은 장기적인 노력을 지원하고 있습니다. 유럽연합(EU)의 ‘ReArm Europe’ 제안은 8,000억 유로(8,700억 달러)의 자금 조달을 목표로 하고 있으며, 여기에는 공동 조달을 위한 대출로 1,500억 유로(1,630억 달러)가 포함되어 있습니다. 이 구상로 인해 독일이 라인메탈(Rheinmetall)사와 체결한 85억 유로(92억 달러) 규모의 탄약 계약 등 대규모 보병용 무기 수주가 잇따르며, 경무기 시장의 수요를 지원하고 있습니다.
비대칭 전쟁의 확대가 휴대용 시스템의 수요를 견인
우크라이나 전장의 경험은 휴대용 미사일이 중무장 부대를 어떻게 무력화할 수 있는지를 보여주고 있으며, 이로 인해 지역 이해관계자들이 유사한 무기를 비축하도록 촉구하고 있습니다. 2019-2023년까지 유럽의 무기 수입액은 2014-2018년에 비해 2배로 증가했습니다. 대만이 3억 6,020만 달러 상당의 ‘스위치블레이드 300’ 로터링 탄약을 구매한 것은 아시아태평양에서 도입이 진행되고 있음을 여실히 보여줍니다. 미 육군의 1,300만 달러 규모 프로그램 하에 배치된 ‘SMASH 2000L’과 같은 스마트 라이플스코프는 드론 대응 대책의 한 예입니다. 이처럼 비대칭 전술의 개념이 경무기 시장에서 다용도로 사용 가능한 소형 제품에 대한 수요를 지원하고 있습니다.
엄격한 국제 무기 이전 규제
미국 상무부는 2024년 5월, 많은 상업 거래에 대해 수출 거부를 전제로 하는 보다 엄격한 총기 수출 규정을 시행했습니다. 워싱턴이 개정된 기존형 무기 이전 정책은 인권 침해를 조장할 가능성이 있는 선적을 차단하고 있습니다. 현재 113개국이 가입한 ‘무기무역조약’은 사전 위험 평가를 의무화하고 있습니다. 영국의 2024년 수출관리법 개정에 따라 신규 기술에 대한 규제 대상이 추가되었습니다. 규정 준수 부담과 라이선스 발급의 불확실성으로 인해 소규모 수출업체의 경무기 시장 진입이 저해되고 있습니다.
부문 분석
MANPADS(휴대용 지대공 미사일)는 2025년 매출의 33.02%를 차지하며, 경무기 시장 규모 내에서 가장 큰 개별 점유율을 기록했습니다. 이는 대만과 동유럽 동맹국들의 스팅어급 미사일에 대한 광범위한 조달을 반영한 것입니다. 로터링 드론에 의한 대체 위협이 존재하지만, 확립된 물류망과 즉각적인 가용성 덕분에 수요는 견고한 추세를 보이고 있습니다. 중기관총과 박격포는 수명 연장 계약을 통해 틈새 시장에서 중요한 위치를 유지하고 있는 반면, 대드론용 소총은 아직 발전 단계에 있지만 중요한 카테고리를 형성하고 있습니다.
수류탄 및 유탄발사기는 8.74%라는 가장 높은 연평균 성장률(CAGR)이 예상됩니다. 프로그래밍 가능한 공중폭발탄이나 콜트 CZ가 인수한 Mk 47과 같은 정밀 발사 장치는 유도식 서브탄두로의 가치 전환을 보여줍니다. 시가지전 교리 및 치안 유지 요건이 군민 양용 제품의 판매를 지원하고 있습니다. 이러한 동향들이 맞물리면서 경무기 시장내 제품 구성을 다각화하는 추세가 확실해지고 있습니다.
유도 탄약은 2025년에 매출의 55.12%를 차지하며, 연평균 성장률(CAGR) 7.28%로 다른 기술을 앞지를 전망이며, 경무기 시장의 점유율 구조에서 그 존재감을 두드러지게 하고 있습니다. 빔 추적형 레이저 유도 모델과 적외선(IR) 방식의 ‘발사 후 방치형’ 미사일은 조작원의 위험을 경감시키고 부수적 피해 허용 기준을 충족합니다. 이는 탈레스(Thales)사의 ‘경량 다목적 미사일(Lightweight Multi-role Missile)’ 시험을 통해도 입증되었습니다.
비유도형 시스템은 가격 면에서의 우위와 전파 방해에 대한 내성 덕분에 여전히 입지를 유지하고 있습니다. 예산 제약이 있는 군대는 공급 안정성을 확보하기 위해 저렴한 탄약을 비축하고 있습니다. 전자전(EW)의 위협이 확대되는 가운데, 스마트형과 비유도형을 모두 갖추면 유연한 리스크 헤지가 가능해지며, 경무기 업계에서 비유도형 제품이 안정적인 틈새 시장을 확보하고 있습니다.
지역별 분석
2025년, 북미는 매출의 38.33%를 차지하며 시장을 주도했습니다. 이는 미국의 9,970억 달러 국방 예산에 힘입은 결과입니다. 견고한 국내 수주가 규모의 경제를 지원하는 한편, 대외 군사 판매(FMS)를 통해 동맹국 군대에 대한 전개 범위가 확대되고 있습니다. 록히드 마틴의 미사일 및 화기 통제 부문 매출은 수주 잔고 전망이 개선됨에 따라 2025년 1분기에 13% 증가한 33억 7,000만 달러를 기록했습니다.
아시아태평양의 경무기 시장 규모는 2031년까지 연평균 성장률(CAGR) 7.53%로 확대될 것으로 예측되며, 이는 지역별로는 가장 높은 성장률입니다. 인도에서는 2024 회계연도부터 2029 회계연도에 걸쳐 국방 자본 지출이 연평균 20% 증가하고 있으며, 계약의 65%를 차지하는 현지 조달 의무가 유지되고 있습니다. 필리핀은 ‘Re-Horizon 3’ 계획에 따라 350억 달러를 편성했으며, 한편 일본의 예산은 21% 증가하여 1952년 이후 최대 규모의 증액을 기록했습니다. 중국을 둘러싼 안보 우려가 고조되면서 다자간 재군비 움직임이 가속화되고 있으며, 공급업체들에게는 광범위한 수주 전망이 열리고 있습니다.
유럽의 군사 지출은 전년 대비 17% 증가한 6,930억 달러로 급증하고 있으며, 이것이 가장 시급한 조달 수요의 급증을 초래하고 있습니다. 독일의 1,000억 유로(1,090억 달러) 기금, 폴란드의 GDP 대비 4.7% 목표, 그리고 EU의 ‘ReArm’ 제안은 보병용 무기의 광범위하고 다년간 걸친 갱신을 지원하고 있습니다. 영국과 독일의 장거리 타격 미사일 등 공동 프로그램은 유럽내 산업적 결속을 보여주며, 지역 경무기 시장을 활성화시키고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the light weapons market size was valued at USD 15.50 billion in 2025 and estimated to grow from USD 16.26 billion in 2026 to reach USD 20.64 billion by 2031, at a CAGR of 4.89% during the forecast period (2026-2031).
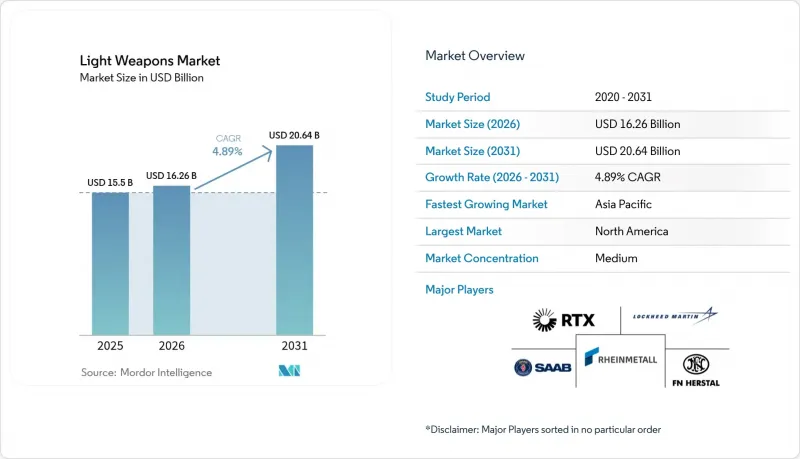
This report is Segmented by Type (Heavy Machine Guns (HMGs), Grenades and Grenade Launchers, Mortars, and More), Technology (Guided and Unguided), Platform (Land-Based, Airborne, and Naval), End-User (Army, Special Forces, and More), Material (Steel and Specialty Alloys, Polymer Composites, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Light Weapons Market Trends and Insights
Escalating Defense Budgets Amid Geopolitical Tensions
European military outlays climbed 17% to USD 693 billion in 2024 as NATO states reacted to Russia's invasion of Ukraine. Poland will raise defense spending to 4.7% of GDP by 2025, while Germany's EUR 100 billion (USD 109 billion) special fund underlines long-term commitment. The European Union's ReArm Europe proposal aims to mobilize EUR 800 billion (USD 870 billion), which includes EUR 150 billion (USD 163 billion) in joint-procurement loans. This initiative has led to significant infantry weapon orders, such as Germany's EUR 8.5 billion (USD 9.2 billion) ammunition contract with Rheinmetall, strengthening the demand in the light weapons market.
Proliferation of Asymmetric Warfare Driving Demand for Man-Portable Systems
Ukraine's battlefield experience shows how man-portable missiles blunt heavier forces, prompting regional actors to stockpile similar assets; European arms imports doubled in 2019-2023 versus 2014-2018. Taiwan's purchase of Switchblade 300 loitering munitions worth USD 360.2 million highlights Asia-Pacific uptake. Smart-rifle scopes such as the SMASH 2000L, fielded under a USD 13 million US Army program, illustrate counter-drone. Asymmetric doctrine thus sustains multi-role, low-footprint products within the light weapons market.
Stringent International Arms-Transfer Regulations
The US Commerce Department imposed tighter firearms-export rules in May 2024, presuming denial for many commercial deals. Washington's revised Conventional Arms Transfer policy blocks shipments likely to enable rights abuses. The Arms Trade Treaty, now at 113 parties, mandates prior risk assessments.The UK's 2024 Export Control amendment added emerging-tech coverage. Compliance overhead and license uncertainty curb smaller exporters' access to the light weapons market.
Other drivers and restraints analyzed in the detailed report include:
- Modernization of Infantry Units with Lightweight Modular Weaponry
- Rising Counter-Terror Operations and Urban Warfare Requirements
- Volatile Raw-Material Prices for Specialty Alloys and Electronics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
MANPADS generated 33.02% of 2025 revenue, the highest individual slice of the light weapons market size, reflecting broad procurement of Stinger-class missiles by Taiwan and Eastern European allies. Although loitering drones threaten substitution, established logistics chains and immediate availability keep demand resilient. Heavy machine guns and mortars retain niche relevance through service-life extension contracts, while counter-drone rifles form a fledgling but important category.
Grenades and grenade launchers delivered the fastest 8.74% CAGR outlook. Programmable air-burst rounds and precision launchers, such as the Mk 47 acquired by Colt CZ, illustrate value migration toward guided sub-munitions. Urban warfare doctrines and policing requirements underpin dual-use sales. Together, these trends ensure product-mix diversification inside the light weapons market.
Guided munitions commanded 55.12% revenue in 2025 and will outpace other technologies at 7.28% CAGR, underlining their mass in the light weapons market share hierarchy. Beam-riding laser models and IR fire-and-forget missiles reduce operator exposure and meet collateral-damage thresholds, as evidenced by Thales' Lightweight Multi-role Missile trials.
Unguided systems persist due to their price advantage and resilience against jamming. Budget-constrained forces stockpile inexpensive rounds to ensure supply sufficiency. As electronic warfare (EW) threats expand, dual inventories-smart and dumb-provide hedge flexibility, securing a stable niche for unguided products within the light weapons industry.
Complete Report Scope:
- By Type
- Heavy Machine Guns (HMGs)
- Grenades and Grenade Launchers
- Mortars
- Man-portable Anti-tank Systems (MANPATS)
- Man-portable Air-Defense Systems (MANPADS)
- Other Types
- By Technology
- Guided
- Laser Guided
- Infra-red Guided
- Satellite Guided
- Semi-automatic Command to Line of Sight
- Unguided
- Guided
- By Platform
- Land-based
- Airborne
- Naval
- By End-user
- Army
- Special Forces
- Law Enforcement Agencies
- Homeland Security/Paramilitary
- Others
- By Material
- Steel and Specialty Alloys
- Aluminum and Light-Metal Alloys
- Polymer Composites
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- Israel
- UAE
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led the market with 38.33% revenue in 2025, anchored by the United States' USD 997 billion defense budget. Robust domestic orders underpin economies of scale, while Foreign Military Sales extend reach into allied fleets. Lockheed Martin's Missiles and Fire Control sales climbed 13% to USD 3.37 billion in Q1 2025 as backlog visibility improved.
Asia-Pacific's light weapons market size is projected to grow at a 7.53% CAGR through 2031, the fastest regional rate. India's 20% compound defense-capital growth through FY24-FY29 sustains local sourcing mandates covering 65% of contracts. The Philippines earmarked USD 35 billion under Re-Horizon 3, while Japan's 21% budget hike marks the largest since 1952. Rising China-related security anxiety fuels multi-country rearmament, giving suppliers an expansive pipeline.
Europe's surge in military spending-up 17% year-on-year to USD 693 billion-creates the most immediate procurement spike. Germany's EUR 100 billion (USD 109 billion) fund, Poland's 4.7% of GDP target, and the EU's ReArm proposal underpin a broad, multi-year refresh of infantry weapons. Joint programs such as the UK-Germany deep-strike missile demonstrate intra-European industrial cohesion, boosting the regional light weapons market.
- FN Herstal, S.A. (FN Browning Group)
- Saab AB
- RTX Corporation
- MBDA
- Thales Group
- BAE Systems plc
- Rheinmetall AG
- Rostec
- Lockheed Martin Corporation
- Rafael Advanced Defense Systems Ltd.
- Denel SOC Ltd.
- Heckler & Koch GmbH
- Israel Aerospace Industries Ltd.
- LIG Nex1 Co. Ltd.
- SIG Sauer Inc.
- Fabbrica d'Armi Pietro Beretta SpA
- Northrop Grumman Corporation
- Colt's Manufacturing Company LLC
- China North Industries Group Corporation Limited (NORINCO)
- Barrett Firearms Manufacturing Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating defense budgets amid geopolitical tensions
- 4.2.2 Proliferation of asymmetric warfare driving demand for man-portable systems
- 4.2.3 Modernization of infantry units with lightweight modular weaponry
- 4.2.4 Rising counter-terror operations and urban warfare requirements
- 4.2.5 Integration of AI-enabled fire-control modules into legacy light weapons
- 4.2.6 Emergence of polymer-cased ammunition reducing soldier load
- 4.3 Market Restraints
- 4.3.1 Stringent international arms-transfer regulations
- 4.3.2 Volatile raw-material prices for specialty alloys and electronics
- 4.3.3 Battlefield shift toward loitering munitions curbing MANPATS demand
- 4.3.4 Environmental/health concerns over legacy propellants
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Heavy Machine Guns (HMGs)
- 5.1.2 Grenades and Grenade Launchers
- 5.1.3 Mortars
- 5.1.4 Man-portable Anti-tank Systems (MANPATS)
- 5.1.5 Man-portable Air-Defense Systems (MANPADS)
- 5.1.6 Other Types
- 5.2 By Technology
- 5.2.1 Guided
- 5.2.1.1 Laser Guided
- 5.2.1.2 Infra-red Guided
- 5.2.1.3 Satellite Guided
- 5.2.1.4 Semi-automatic Command to Line of Sight
- 5.2.2 Unguided
- 5.2.1 Guided
- 5.3 By Platform
- 5.3.1 Land-based
- 5.3.2 Airborne
- 5.3.3 Naval
- 5.4 By End-user
- 5.4.1 Army
- 5.4.2 Special Forces
- 5.4.3 Law Enforcement Agencies
- 5.4.4 Homeland Security/Paramilitary
- 5.4.5 Others
- 5.5 By Material
- 5.5.1 Steel and Specialty Alloys
- 5.5.2 Aluminum and Light-Metal Alloys
- 5.5.3 Polymer Composites
- 5.5.4 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 France
- 5.6.2.3 Germany
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 Israel
- 5.6.5.1.3 UAE
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 FN Herstal, S.A. (FN Browning Group)
- 6.4.2 Saab AB
- 6.4.3 RTX Corporation
- 6.4.4 MBDA
- 6.4.5 Thales Group
- 6.4.6 BAE Systems plc
- 6.4.7 Rheinmetall AG
- 6.4.8 Rostec
- 6.4.9 Lockheed Martin Corporation
- 6.4.10 Rafael Advanced Defense Systems Ltd.
- 6.4.11 Denel SOC Ltd.
- 6.4.12 Heckler & Koch GmbH
- 6.4.13 Israel Aerospace Industries Ltd.
- 6.4.14 LIG Nex1 Co. Ltd.
- 6.4.15 SIG Sauer Inc.
- 6.4.16 Fabbrica d'Armi Pietro Beretta SpA
- 6.4.17 Northrop Grumman Corporation
- 6.4.18 Colt's Manufacturing Company LLC
- 6.4.19 China North Industries Group Corporation Limited (NORINCO)
- 6.4.20 Barrett Firearms Manufacturing Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


