

|
시장보고서
상품코드
2122258
정형외과용 의지 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Orthopedic Prosthetics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
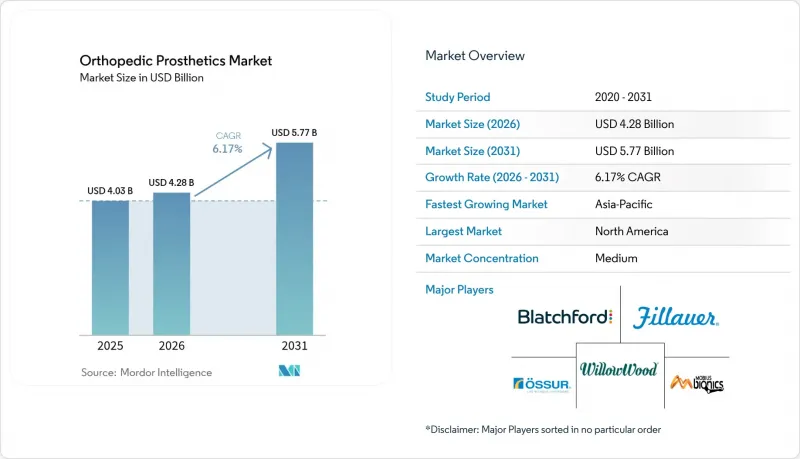
에 따르면 2026년 정형외과용 의지 시장의 규모는 42억 8,000만 달러로 추정되고 있으며, 2025년 40억 3,000만 달러에서 확대하며, 2031년에는 57억 7,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지 연평균 성장률(CAGR) 6.17%로 성장할 것으로 전망됩니다.
이 보고서는 제품 유형(상지 의지, 하지 의지, 라이너,소켓, 모듈형 부품, 특수·스포츠용 의수·의족), 기술(기존형, 전동식/근전도식, 기타), 최종사용자(병원, 의수·의족 클리닉, 기타) 및 지역(북미, 유럽, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 정형외과용 의지 시장의 동향 및 인사이트
당뇨병 관련 절단 수술 증가가 시장 확대를 주도
연간 100만 건 이상의 당뇨병 관련 하지 절단 수술이 이루어지고 있으며, 전단력을 줄이고 취약한 피부 표면의 감염 관리를 개선하는 첨단 소켓 설계에 대한 수요가 급증하고 있습니다. 미국, 중국, 인도의 전문적인 풋케어 시스템 덕분에 환자들은 더 이른 시기에 의족 치료를 받게 되었으며, 이로 인해 의족 교체 주기가 앞당겨지고, 부품의 정기적인 판매가 확대되고 있습니다. 이러한 수요 증가에 대응하기 위해 각 제조사들은 신경 손상으로 인한 보행 패턴에 대응하고 에너지 소비를 줄여주는 더 가벼운 탄소 복합재 파이론에 대한 투자를 확대하고 있습니다. 이러한 현상은 급속한 생활 방식의 변화가 당뇨병 유병률 상승을 초래하고 있는 아시아태평양의 도시에서 특히 두드러지며, 이 지역의 시장 확대는 공중 보건의 우선 과제와 기부금을 통한 사지 결손자 지원 구상과 맥을 같이하고 있습니다.
고령화가 진행됨에 따라 퇴행성 관절염과 관련된 수요가 증가
북유럽, 일본, 호주에서는 연령 중앙값이 40세를 넘어서는 추세이며, 관절 치환술이나 재치환술의 경우 부분 의족이 필요한 고령자 층이 확대되고 있습니다. 베이비붐 세대는 골프, 하이킹, 가벼운 조깅을 지원하는 고활동형 의족 무릎 관절을 강력히 요구한다는 점에서 이전 세대와는 다릅니다. 그 결과, 설계상의 우선순위는 스윙 단계를 실시간으로 조정하는 적응형 댐핑 기능을 갖춘 마이크로프로세서 유닛으로 이동하고 있습니다. 보험사들은 낙상 감소 효과와 연관된 증거가 있을 경우, 이러한 고급 의료기기에 대한 보험 적용을 점점 더 인정하고 있으며, 고령 운동선수들의 장비 업그레이드 주기를 촉진하고 있습니다. 병원에서는 골밀도 검사와 인공관절 선정을 통합한 노인 정형외과 프로그램을 도입하여, 의료기기의 지속적인 교체를 더욱 지원하고 있습니다.
보상 제도의 불일치가 시장 접근을 저해
미국의 메디케어 수급자는 보험에 가입되어 있더라도 사지당 여전히 3,580달러의 본인 부담금을 지불해야 합니다. 이러한 장벽으로 인해 기기 사용이 중단되고, 그 결과 교체 주기가 단축되며 애프터마켓 매출이 감소하고 있습니다. 프랑스에서는 2025년에 환급률이 25% 삭감됨에 따라 공급업체의 철수나 산발적인 임플란트 부족 현상이 발생하여, 정책 변동이 공급 상황에 어떤 영향을 미치는지가 여실히 드러났습니다. 스타트업 기업은 마이크로프로세서 탑재형 인공 무릎 관절을 판매하는 대신 리스 방식을 채택하고, 소프트웨어 업데이트 및 유지보수를 지불자의 예산 주기에 맞춘 구독형 플랜에 포함시킴으로써 이익률 압박에 대응하고 있습니다.
부문 분석
2025년 현재, 하지용 솔루션은 정형외과용 의지 시장 규모의 55.12%를 차지하고 있으며, 그 주요 원인은 발생률이 높은 경골 절단 및 대퇴골 절단 수술에 있습니다. 수요가 집중됨에 따라 규모의 경제가 발생하고, 제조업체는 이를 활용하여 스포츠 중 높은 비틀림 하중을 견딜 수 있는 차세대 회전 어댑터의 연구개발 자금을 조달하고 있습니다. 라이너는 수익 규모는 작지만, 의족 사용 중단과 밀접한 관련이 있는 두 가지 요인, 즉 피부 발한 관리와 잔존 사지의 부피 변동을 해결함으로써 2031년까지 연평균 성장률(CAGR) 9.52%를 달성하고 있습니다. 항균성 나노입자가 배합된 새로운 열가소성 엘라스토머 젤 덕분에 라이너 교체 주기가 연장되어, 임상적 감독을 최소화하면서도 지속적인 매출을 창출하고 있습니다. 특수 스포츠용 의수는 틈새 시장이지만, 높은 가격 책정이 가능하며, 주류 상지 의수의 업그레이드를 촉진하는 브랜딩의 쇼케이스 역할을 하고 있습니다. 소켓 부문에서 정형외과용 의지의 시장 점유율은 수작업으로 적층된 유리섬유 쉘을 대체하여 맞춤형 3D 프린팅 격자 구조가 채택됨에 따라 점차 상승하고 있으며, 이로 인해 무게가 30% 경감되고 마라톤 주자에게 더 나은 통기성을 제공하고 있습니다.
지역별 분석
북미는 2025년, 고급 마이크로프로세서 탑재형 무릎 의수 및 의족 비용을 보상하는 보험 제도와 인증된 의료 전문가들의 긴밀한 네트워크에 힘입어 지역 매출 점유율 41.88%를 유지했습니다. 미국은 정형외과용 의수·의족 시장 전체에서 기술적 리더십의 후광 효과를 공고히 하는 획기적인 AMI 및 OMP 연구의 거점으로서, 이 지역의 혁신을 주도하고 있습니다. 캐나다는 주를 넘나드는 원격 보조기 플랫폼을 활용하여 북부 지역으로의 접근성을 확대하고 있는 반면, 멕시코는 마키라도라(수출가공구) 집적지를 통합하여 수출용 경량 파이론을 공동 생산하고 있습니다.
연평균 성장률(CAGR) 10.71%의 성장이 예상되는 아시아태평양에서는 당뇨병 유병률이 매우 높은 상황과 야심 찬 국민건강보험 제도의 도입이 맞물려 시장이 확대되고 있습니다. 중국의 현지 혁신 기업은 수입품보다 35% 저렴한 저비용 3D 프린팅 소켓 개발을 가속화하고 있습니다. 인도에서는 지역 수준의 외상 센터를 대상으로 모듈식 다리에 대한 공공 조달이 이루어져 수요를 더욱 끌어올리고 있습니다. 일본과 한국은 감각 피드백 기술의 최첨단을 추구하고 있으며, 첨단 펌웨어 업그레이드에 대한 지역적 수요를 주도하고 있습니다. 호주에서는 전문가 부족에도 불구하고 인력 부족을 보완하는 AI 가이드 방식 정렬 툴의 도입률이 높은 수준을 유지하고 있습니다. 분쟁 지역에서의 원격 의족 지원 등 지역적 인도주의 지원 프로젝트는 위성 네트워크를 통한 설계 파일의 국경을 초월한 보급을 여실히 보여주고 있습니다. 유럽은 규제가 엄격한 성숙한 환경에 있으며, 가격 상한제로 인해 이익률은 압박받고 있지만, 임상 실무 기준은 여전히 엄격하게 유지되고 있습니다. 독일은 자재 부족을 완화하기 위한 탄소섬유 재활용 노력을 주도하고 있는 반면, 영국은 NHS 장기 계획에 따라 디지털 정형외과 시범 사업을 신속하게 추진하고 있습니다. 프랑스에서는 환급액 삭감으로 인해 국지적인 공급 부족이 발생하고 있으며, 병행 수입 경로가 활성화되는 동시에 지속가능한 가격 책정에 대한 논의가 일고 있습니다. 남미, 중동 및 아프리카는 현재 시장 점유율이 낮은 편이지만, 브라질과 UAE에 3D 프린팅 거점이 부상하고 있으며, 문화적 요구에 맞춘 심미 커버와 충격 흡수형 족부 부품의 리드타임이 점차 단축되고 있으며, 한 자릿수 후반대의 높은 성장률을 보이고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.07According to Mordor Intelligence, orthopedic prosthetics market size in 2026 is estimated at USD 4.28 billion, growing from 2025 value of USD 4.03 billion with 2031 projections showing USD 5.77 billion, growing at 6.17% CAGR over 2026-2031.
This report is Segmented by Product Type (Upper Extremity Prosthetics, Lower Extremity Prosthetics, Liners, Sockets, Modular Components, and Specialty & Sports Prosthetics), Technology (Conventional, Electric Powered/Myoelectric, and More), End-User (Hospitals, Prosthetic Clinics, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Orthopedic Prosthetics Market Trends and Insights
Rising Diabetes-Linked Amputations Drive Market Expansion
More than 1 million diabetes-related lower-limb amputations occur yearly, sharply lifting demand for sophisticated socket designs that reduce shear forces and improve infection control for fragile skin surfaces. Specialized foot-care pathways in the United States, China, and India now funnel patients toward earlier prosthetic intervention, bringing forward replacement cycles and expanding recurring component sales. Manufacturers responding to this volume uptick are investing in lighter carbon-composite pylons that accommodate neuropathic gait patterns and reduce energy expenditure. The phenomenon is particularly acute in urban Asia-Pacific where rapid lifestyle changes drive higher diabetes prevalence, aligning regional market expansion with public-health priorities and donor-funded limb-loss initiatives.
Ageing Population Amplifies Osteoarthritis-Related Demand
Median ages are climbing above 40 years in Northern Europe, Japan, and Australia, widening the pool of seniors requiring joint replacements and, in revision scenarios, partial limb prostheses. Baby-boomer cohorts differ from earlier generations by insisting on high-activity prosthetic knees that support golfing, hiking, and light-jogging. Consequently, design priorities have shifted toward adaptive damping microprocessor units that modulate swing phase in real time. Payers increasingly reimburse for such higher-end devices when linked to fall-reduction evidence, reinforcing the upgrade cycle for elderly athletes. Hospitals have introduced geriatric-orthopedics programs integrating bone-density screening with prosthetic selection, further supporting sustained device turnover.
Reimbursement Inconsistencies Constrain Market Access
Medicare beneficiaries in the United States still pay USD 3,580 out-of-pocket per limb despite insurance, a barrier prompting device abandonment that reduces replacement cycles and aftermarket sales. France's 25% reimbursement cut in 2025 led to supplier exits and sporadic implant shortages, underscoring how policy swings reshape supply availability. Start-ups counteract margin pressure by leasing rather than selling microprocessor knees, bundling software updates and maintenance into subscription plans aligned with payer budget cycles.
Other drivers and restraints analyzed in the detailed report include:
- Microprocessor and Myoelectric Technology Breakthrough
- 3-D Printing Democratizes Access in Emerging Markets
- Workforce Shortages Limit Service Delivery Capacity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lower-extremity solutions represented 55.12% of the orthopedic prosthetics market size in 2025, anchored by high-incidence transtibial and transfemoral procedures. Demand concentration creates scale economies that manufacturers leverage to fund R&D for next-generation rotary adapters that tolerate higher torsional loads during sports. Liners, while a smaller revenue pool, deliver 9.52% CAGR through 2031 by addressing skin-sweat management and residual-limb volume fluctuation, two factors strongly correlated with device abandonment. New thermoplastic elastomer gels infused with antimicrobial nanoparticles extend liner replacement intervals, generating recurring sales with minimal clinical oversight. Specialty-sports prosthetics, though niche, attract premium pricing and act as branding showcases that inspire mainstream upper-limb upgrades. The orthopedic prosthetics market share for sockets climbs gradually as custom 3-D printed lattices displace hand-laminated fiberglass shells, reducing weight by 30% and improving airflow for marathon runners.
Complete Report Scope:
- By Product Type
- Upper Extremity Prosthetics
- Lower Extremity Prosthetics
- Liners
- Sockets
- Modular Components
- Specialty & Sports Prosthetics
- By Technology
- Conventional
- Electric Powered / Myoelectric
- Hybrid
- 3-D Printed / Additively Manufactured
- Robotic / Microprocessor Controlled
- By End-User
- Hospitals
- Prosthetic Clinics
- Rehabilitation Centers
- Ambulatory Surgical Centers
- Home-care Settings
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 41.88% regional revenue share in 2025, powered by insurance coverage that reimburses high-end microprocessor knees and arms, as well as dense networks of certified practitioners. The United States drives regional innovation, hosting landmark AMI and OMP research that secures technology-leadership halo effects across the orthopedic prosthetics market. Canada leverages cross-provincial tele-orthotics platforms to extend access to northern communities, whereas Mexico integrates maquiladora clusters to co-manufacture lightweight pylons for export.
Asia-Pacific, forecast to rise at a 10.71% CAGR, combines outsized diabetes prevalence with ambitious universal-health coverage rollouts. China's local innovators accelerate low-cost 3-D printed sockets that undercut imports by 35%. India's public procurement of modular feet for district-level trauma centers further lifts volume. Japan and South Korea push the frontier in sensory feedback, driving regional demand for advanced firmware upgrades. Australia, despite practitioner scarcity, maintains high adoption of AI-guided alignment tools that compensate for workforce gaps. Regional humanitarian projects, such as remote prosthetic aid in conflict zones, illustrate cross-border dissemination of design files over satellite networks. Europe presents a mature, regulation-intensive environment where price caps squeeze margins yet clinical practice standards remain rigorous. Germany pioneers carbon-fiber recycling initiatives to mitigate material scarcity, while the United Kingdom fast-tracks digital orthopedics pilots under the NHS Long-Term Plan. France's reimbursement cuts create localized shortages, prompting parallel-import channels and sparking debate on sustainable pricing. South America, Middle East, and Africa collectively account for modest share today yet post high single-digit growth as 3-D printing hubs emerge in Brazil and the UAE, gradually reducing lead times for culturally attuned cosmetic covers and shock-absorbing feet.
- Ossur
- Ottobock
- Zimmer Biomet
- Stryker
- Smiths Group
- DePuy Synthes (J&J)
- Medtronic
- Enovis (DJO)
- Blatchford
- Willow Wood
- Freedom Innovations
- Touch Bionics
- Steeper Group
- College Park Industries
- Ultraflex Systems
- Fillauer
- SHL Medical
- ReWalk Robotics
- Proteor
- Ability Dynamics
- Mobius Bionics, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising diabetes-linked amputations
- 4.2.2 Ageing population & osteoarthritis prevalence
- 4.2.3 Advancements in microprocessor & myoelectric limbs
- 4.2.4 Expansion of 3-D printing service hubs in emerging markets
- 4.2.5 Defence-veteran rehab funding surge in Asia-Pacific
- 4.2.6 E-commerce aftermarket component sales growth
- 4.3 Market Restraints
- 4.3.1 High device cost & inconsistent reimbursement
- 4.3.2 Shortage of certified prosthetists in developing nations
- 4.3.3 Titanium & carbon-fibre supply bottlenecks
- 4.3.4 Cyber-security scrutiny of smart prosthetics
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Upper Extremity Prosthetics
- 5.1.2 Lower Extremity Prosthetics
- 5.1.3 Liners
- 5.1.4 Sockets
- 5.1.5 Modular Components
- 5.1.6 Specialty & Sports Prosthetics
- 5.2 By Technology
- 5.2.1 Conventional
- 5.2.2 Electric Powered / Myoelectric
- 5.2.3 Hybrid
- 5.2.4 3-D Printed / Additively Manufactured
- 5.2.5 Robotic / Microprocessor Controlled
- 5.3 By End-User
- 5.3.1 Hospitals
- 5.3.2 Prosthetic Clinics
- 5.3.3 Rehabilitation Centers
- 5.3.4 Ambulatory Surgical Centers
- 5.3.5 Home-care Settings
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Ossur
- 6.3.2 Ottobock
- 6.3.3 Zimmer Biomet
- 6.3.4 Stryker
- 6.3.5 Smith & Nephew
- 6.3.6 DePuy Synthes (J&J)
- 6.3.7 Medtronic
- 6.3.8 Enovis (DJO)
- 6.3.9 Blatchford
- 6.3.10 Willow Wood
- 6.3.11 Freedom Innovations
- 6.3.12 Touch Bionics
- 6.3.13 Steeper Group
- 6.3.14 College Park Industries
- 6.3.15 Ultraflex Systems
- 6.3.16 Fillauer
- 6.3.17 SHL Medical
- 6.3.18 ReWalk Robotics
- 6.3.19 Proteor
- 6.3.20 Ability Dynamics
- 6.3.21 Mobius Bionics, LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


