

|
시장보고서
상품코드
2122259
인공 발목 관절 치환술 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Total Ankle Replacement - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
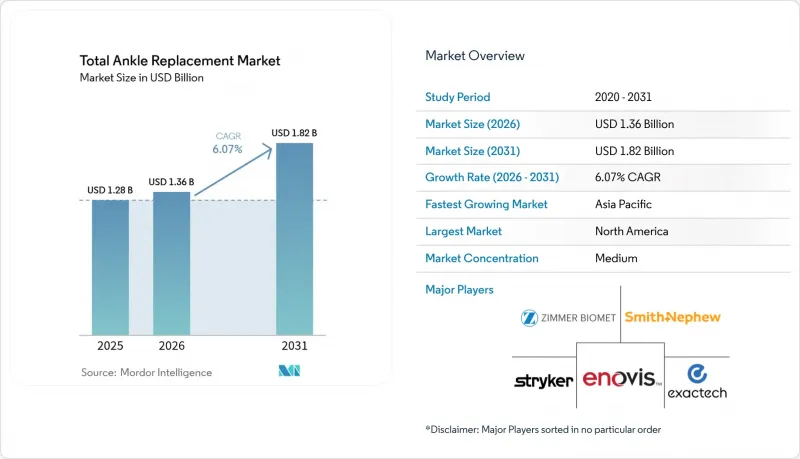
에 의하면, 인공 발목 관절 치환술 시장 규모는 2025년에 12억 8,000만 달러로 평가되었고, 2026년 13억 6,000만 달러에서 2031년까지 18억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.07%를 나타낼 전망입니다.
본 보고서는 설계별(HINTEGRA, STAR, SALTO/SALTO Talaris 등), 베어링 유형별(가동 베어링 시스템, 고정 베어링 시스템, 하이브리드/세미컨스트레인드), 최종 사용자별(병원, 외래수술센터(ASC) 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 인공 발목 관절 치환술 시장 동향 및 인사이트
발목 퇴행성 관절염 유병률 증가 및 고령화
고령이면서도 활동적인 성인층으로의 인구 구성 변화로 인해 발목 퇴행성 관절염의 발생률이 상승하고 있으며, 이는 인공 발목 관절 치환술 시장을 견인하고 있습니다. 외상이 주된 원인이기 때문에 스포츠 참여나 교통사고로 인한 부상 증가에 따라 질병 부담도 확대되고 있습니다. 임상 연구에 따르면, 수술 후 스포츠 복귀율은 31.1%에서 85.4%로 상승했으며, 최신 임플란트가 고령자의 가동성과 자립성을 유지하고 있음이 확인되었습니다. 따라서 다국적 의료 시스템에서는 인공 발목 관절 치환술술을 ‘최후의 수단’이 아닌 ‘삶의 질(QOL)을 향상시키는 치료법’으로 규정하고, 관절염 치료 경로에 포함시킴으로써 장기적인 수요를 견인하고 있습니다.
저침습·영상 유도·로봇 보조 인공 발목 관절 치환술(TAR)의 급증
내비게이션 및 로봇 플랫폼은 절제 정밀도 향상, 연부 조직 손상 최소화, 학습 곡선 단축을 통해 무릎 관절 치환술에서 얻은 인사이트를 발목 관절 수술에 적용하고 있습니다. 미국에서 시행되는 무릎 관절 치환술의 약 13%에서는 이미 로봇 기술이 채택되고 있으며, 주요 정형외과 센터에서는 현재 발목 관절 수술에도 유사한 워크플로우를 도입하고 있습니다. 로봇 기술은 뼈를 보존하고 침하를 완화하는 외측 접근법을 지원하는 동시에, 수술 중 센서가 임플란트의 정렬 상태를 실시간으로 정량화합니다. 이러한 장점 덕분에, 기존에는 고정술이 예정되었던 변형 사례로도 적응 범위가 확대되어 외래 치료 프로토콜의 매력이 높아지고 있습니다. 이러한 요인들이 맞물려 인공 발목 관절 치환술 시장을 가속화하고 있습니다.
수술 후 합병증과 재치환의 부담
장기 데이터에 따르면, 10년 후 재치환율은 10.9%에 가까우며, 20년 후에는 13.5%에 달하는데, 이는 고관절이나 무릎 관절 치환술에 비해 현저히 높은 수치입니다. 인공관절 주변의 감염 위험은 1%에서 14% 사이이며, 발목의 연부 조직 구조가 상처 치유를 복잡하게 만들고 있습니다. FDA는 2024년, Hintermann H3 시스템의 고장률이 16.1%를 초과한다며 주의를 환기하고 경계의 필요성을 강조했습니다. 이에 대해 외과의사들은 적응증 기준 강화, 수술 전 준비 철저화, 양측 수술 제한 등의 조치를 취하고 있으며, 이 모든 요소가 인공 발목 관절 치환술술 시장의 수술 건수 증가를 억제하는 요인이 되고 있습니다.
부문 분석
2025년, INBONE II 및 INFINITY 플랫폼은 합계 매출 점유율 33.12%를 차지했으며, 발목 관절 전치환 시장에서 가장 큰 점유율을 확보했습니다. 이러한 모듈식 경골 스템은 짧은 골간단 포스트부터 긴 골수내 부문에 이르기까지 맞춤형 고정이 가능하며, 이러한 접근 방식은 재치환술이나 골다공증 사례에서 초기 안정성을 향상시킵니다. 95.9%라는 7년 생존율은 신뢰할 수 있는 중기적 성능을 입증하며, 2024년까지 전 세계 사용자의 임플란트 시술 건수는 4만 8,000건을 넘어섰습니다. 경쟁사와의 차별화의 핵심은 환자별로 최적화된 가이드와, 세팅 시간 및 방사선 피폭을 줄여주는 간소화된 기구 세트이며, 이러한 점들은 외래 진료 현장에서 높은 평가를 받고 있습니다. 병행하여 진행 중인 임상 프로그램에서는 형광 투시법을 통한 운동학적 데이터가 수집되고 있으며, 이는 거의 자연스러운 시상면 및 관상면의 움직임을 보여주고 있습니다. 이를 통해 보험사에 제출하는 데 필요한 근거가 강화되어, 발목 관절 전치환 시장에서의 리더십이 더욱 공고해지고 있습니다.
CADENCE는 폴리에틸렌 배합, 종골 돔의 곡률, 그리고 간소화된 외측 접근용 기구 세트의 획기적인 발전에 힘입어 2031년까지 연평균 성장률(CAGR) 8.63%의 성장 궤도를 기록했습니다. 초기 치료 성과 등록부에 따르면, 수술 후 2년 시점의 환자 만족도는 98%를 기록했으며, 외과의사들로부터는 골절제술이 간소화되고 지역 병원의 숙련도 습득 기간이 단축되었다는 보고가 접수되었습니다. ‘VANTAGE’, ‘STAR’ 및 ‘SALTO Talaris’는 각각 독자적인 베어링 설계 철학과 지역별 보험 급여 체계를 활용하여 꾸준한 지지를 유지하고 있습니다. ‘Paragon 28’의 3D 프린팅 APEX 시스템은 다공성 해면골 표면과 산화 및 마모를 방지하는 비타민 E로 안정화된 라이너를 채택하고 있습니다. 예측 기간 동안 설계 혁신은 스마트 센서 통합과 MRI 호환 합금 채택에 초점이 맞추어질 것입니다. 이를 통해 임상의는 원격으로 임플란트의 상태를 모니터링할 수 있게 되어, 재수술 증가 및 제조업체에게 2차 수익원 창출로 이어질 것입니다.
지역별 분석
북미는 2025년 매출의 42.71%를 차지한 것으로 평가되었으며, CMS(미국 의료보험 서비스 센터)의 보험 적용 범위, 높은 외과 의사 밀도, 그리고 소비자들이 고품질 임플란트에 대해 지불할 의사가 있다는 점 등에 힘입어 전 세계 임상 지침 수립의 핵심 역할을 담당하고 있습니다. 미국 의사들은 연간 1만 1,000건 이상의 발목 관절 치환술을 시행하고 있으며, 정렬을 최적화하기 위해 인대 재건술 등의 수술을 병행하는 경우가 빈번합니다. 캐나다는 온타리오주와 앨버타주에 위치한 공공 자금 지원 전문 의료 센터를 통해 시장에 기여하고 있는 반면, 멕시코의 민간 부문은 관절 가동성을 보존하는 수술을 원하는 중미 출신의 의료 관광객을 유치하고 있습니다.
유럽은 여전히 2위 시장 규모를 유지하고 있으며, 독일, 프랑스, 영국이 엄격한 CE 마크 요건 및 비용 대비 효과 기준 하에서 수술 건수를 주도하고 있습니다. 각국의 공적 의료 제도에서는 장기적인 재치환율을 면밀히 검토하는 의료 기술 평가(HTA)가 실시되고 있으며, 이에 따라 제조업체들은 동료 심사를 거친 생존율 데이터를 공개하도록 권장받고 있습니다. 스칸디나비아 국가들은 등록부에서 얻은 인사이트를 공유하고 있으며, 이는 유럽 전체의 보험 급여 협상에 영향을 미치고 있습니다.
아시아태평양은 고령화와 가처분 소득 증가로 인해 고도의 정형외과 의료에 대한 수요가 높아지고 있어, 2031년까지 연평균 성장률(CAGR) 10.35%로 가장 빠르게 성장하는 지역입니다. 중국에서는 상하이와 베이징에서 펠로우십 프로그램이 확대되고 있으며, 일본에서는 국민건강보험 제도를 활용하여 특정 의료 기술을 보험 적용 대상으로 하고 있고, 인도의 최고급 병원들은 국내 의료 관광객을 유치하고 있습니다. 외상 발생률이 높고 당뇨병 환자 수가 많은 것이 맞물려 관절염 부담이 증가하고 있어, 인공 발목 관절 치환술 시장에 유망한 성장의 길이 열리고 있습니다. 중동 및 아프리카 및 남미에서는 민간 병원 체인이 전문 지식을 도입하고 있어 도입이 초기 단계에 있지만, 환율 변동과 본인 부담금 동향으로 인해 단기적인 수술 건수는 제한되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the total ankle replacement market size was valued at USD 1.28 billion in 2025 and estimated to grow from USD 1.36 billion in 2026 to reach USD 1.82 billion by 2031, at a CAGR of 6.07% during the forecast period (2026-2031).
This report is Segmented by Design (HINTEGRA, STAR, SALTO / SALTO Talaris, and More), Bearing Type (Mobile-Bearing Systems, Fixed-Bearing Systems, Hybrid / Semi-Constrained), End User (Hospitals, Ambulatory Surgical Centers, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Total Ankle Replacement Market Trends and Insights
Rising Prevalence of Ankle Osteoarthritis & Aging Population
The demographic shift toward older, more active adults elevates the incidence of ankle osteoarthritis and fuels the total ankle replacement market. Trauma is the leading etiology, so the disease burden grows as sports participation and road traffic injuries increase. Clinical studies show postoperative return-to-sport rates climbing from 31.1% to 85.4%, confirming that modern implants maintain mobility and independence among seniors. Multinational health systems, therefore, position total ankle arthroplasty as a quality-of-life intervention rather than a last resort, embedding it into arthritis care pathways and driving long-term demand.
Surge in Minimally-Invasive, Image-Guided & Robotic TAR Procedures
Navigation and robotic platforms translate lessons from knee arthroplasty to the ankle by improving resection accuracy, minimizing soft-tissue disruption, and shortening learning curves. About 13% of United States knee replacements already use robotics, and leading orthopedic centers now deploy similar workflows for ankles. Robotics supports lateral approaches that conserve bone and mitigate subsidence, while intraoperative sensors quantify implant alignment in real time. These advantages widen candidacy to deformity cases previously slated for fusion and enhance the appeal of outpatient protocols, together accelerating the total ankle replacement market.
Surgical-Site Complications & Revision Burden
Long-term datasets reveal 10-year revision rates near 10.9% and 20-year rates at 13.5%, materially higher than hip or knee arthroplasty. Periprosthetic infection risks run from 1% to 14%, and ankle soft-tissue envelopes complicate wound healing. The FDA flagged the Hintermann H3 system in 2024 for failure rates exceeding 16.1%, underscoring vigilance requirements. Surgeons respond by tightening indications, extending preoperative optimization, and limiting bilateral cases, all of which temper procedure volume growth within the total ankle replacement market.
Other drivers and restraints analyzed in the detailed report include:
- Favourable Reimbursement Expansion
- Additive-Manufactured, Patient-Specific Ankle Implants Gain FDA Clearances
- High Device & Procedure Costs Limit Adoption in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
INBONE II and INFINITY platforms combined for a 33.12% revenue share in 2025, giving them the most significant stake in the total ankle replacement market. Their modular tibial stems provide customizable fixation ranging from short metaphyseal posts to long intramedullary segments, an approach that improves initial stability in revision and osteoporotic cases. Seven-year survivorship of 95.9% underscores dependable mid-term performance, and global users passed 48,000 implants by 2024. Competitive differentiation centers on integrated patient-specific guides and streamlined instrumentation sets that cut setup time and radiation exposure, advantages prized in ambulatory settings. Parallel clinical programs collect fluoroscopic kinematic data that illustrate near-native sagittal and coronal plane motion, bolstering evidence packages for payer submissions and further fortifying leadership in the total ankle replacement market.
CADENCE rose on an 8.63% CAGR trajectory through 2031, propelled by breakthroughs in polyethylene formulation, talar dome curvature, and streamlined lateral approach instrumentation. Early outcome registries show 98% patient satisfaction at two years, and surgeons report simplified bone resections that trim learning curves for community hospitals. VANTAGE, STAR, and SALTO Talaris retain loyal followings, each leveraging distinct bearing philosophies and regional reimbursement footholds. Paragon 28's 3D-printed APEX system adds porous trabecular surfaces and vitamin E stabilized liners to resist oxidation and wear. Over the forecast, design innovations will hinge on smart sensor integration and MRT-compatible alloys that let clinicians monitor implant health remotely, fueling repeat procedures and secondary revenue streams for manufacturers.
Complete Report Scope:
- By Design
- HINTEGRA
- STAR
- SALTO / SALTO Talaris
- INBONE II / INFINITY
- CADENCE
- Other Designs
- By Bearing Type
- Mobile-Bearing Systems
- Fixed-Bearing Systems
- Hybrid / Semi-constrained
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Orthopaedic Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 42.71% of revenue in 2025 and anchors global clinical guideline development, driven by CMS coverage, high surgeon density, and consumer willingness to pay for premium implants. United States physicians perform more than 11,000 ankle replacements annually and frequently combine procedures such as ligament reconstruction to optimize alignment. Canada contributes through publicly funded specialist centers in Ontario and Alberta, whereas Mexico's private sector captures medical tourists from Central America seeking motion-preserving procedures.
Europe remains the second-largest cluster, with Germany, France, and the United Kingdom leading volumes under stringent CE-mark requirements and cost-utility thresholds. National health systems conduct health-technology assessments that scrutinize long-term revision rates, encouraging manufacturers to publish peer-reviewed survivorship data. Scandinavian countries share registry insights that influence broader European reimbursement negotiations.
Asia-Pacific is the fastest-growing region at a 10.35% CAGR to 2031 as aging populations and rising disposable income heighten demand for advanced orthopedic care. China ramps fellowship programs in Shanghai and Beijing, Japan leverages universal insurance to cover select technologies, and India's tier-1 hospitals attract domestic medical tourists. The combination of heavy trauma incidence and large diabetes populations increases arthritis burden, creating a fertile expansion corridor for the total ankle replacement market. Middle East and Africa plus South America show nascent uptake as private hospital chains import expertise, though currency fluctuations and out-of-pocket dynamics temper near-term procedure counts.
- Stryker
- Zimmer Biomet
- Smiths Group
- Paragon 28
- Exactech
- Enovis (DJO)
- Vilex
- restor3d
- Conmed
- Allegra Orthopaedics
- Integra LifeSciences
- Wright Medical Group
- Arthrex
- Medartis
- Johnson & Johnson
- Ossur
- Corin Group
- Zimmer Surgical
- Medtronic
- BioPoly LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Ankle Osteoarthritis & Aging Population
- 4.2.2 Surge in Minimally-Invasive, Image-Guided & Robotic TAR Procedures
- 4.2.3 Favourable Reimbursement Expansion
- 4.2.4 Additive-Manufactured, Patient-Specific Ankle Implants Gain FDA Clearances
- 4.2.5 Growing Demand from Younger, Sports-Injury Cohort Seeking Motion Preservation
- 4.2.6 Outpatient TAR Adoption in ASC Settings after CMS Rule Changes
- 4.3 Market Restraints
- 4.3.1 Surgical-Site Complications & Revision Burden
- 4.3.2 High Device & Procedure Costs Limit Adoption in Emerging Markets
- 4.3.3 Absence of Long-Term Global Implant Registry Data Hampers Surgeon Confidence
- 4.3.4 Joint-Preserving Alternatives Delaying TAR
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Design
- 5.1.1 HINTEGRA
- 5.1.2 STAR
- 5.1.3 SALTO / SALTO Talaris
- 5.1.4 INBONE II / INFINITY
- 5.1.5 CADENCE
- 5.1.6 Other Designs
- 5.2 By Bearing Type
- 5.2.1 Mobile-Bearing Systems
- 5.2.2 Fixed-Bearing Systems
- 5.2.3 Hybrid / Semi-constrained
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Specialty Orthopaedic Clinics
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Stryker Corporation
- 6.3.2 Zimmer Biomet
- 6.3.3 Smith + Nephew
- 6.3.4 Paragon 28
- 6.3.5 Exactech
- 6.3.6 Enovis (DJO)
- 6.3.7 Vilex
- 6.3.8 restor3d
- 6.3.9 CONMED
- 6.3.10 Allegra Orthopaedics
- 6.3.11 Integra LifeSciences
- 6.3.12 Wright Medical
- 6.3.13 Arthrex
- 6.3.14 Medartis
- 6.3.15 DePuy Synthes (Johnson & Johnson)
- 6.3.16 Ossur
- 6.3.17 Corin Group
- 6.3.18 Zimmer Surgical
- 6.3.19 Medtronic
- 6.3.20 BioPoly LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


