

|
시장보고서
상품코드
2122278
액티브 지오펜싱 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Active Geofencing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 액티브 지오펜싱 시장 규모는 2025년 22억 3,000만 달러로 평가되었고, 2026년에는 27억 달러로 추정되고, 2026-2031년 CAGR 20.94%로 성장을 지속할 전망이며, 2031년에는 69억 7,000만 달러에 이를 것으로 예측됩니다.
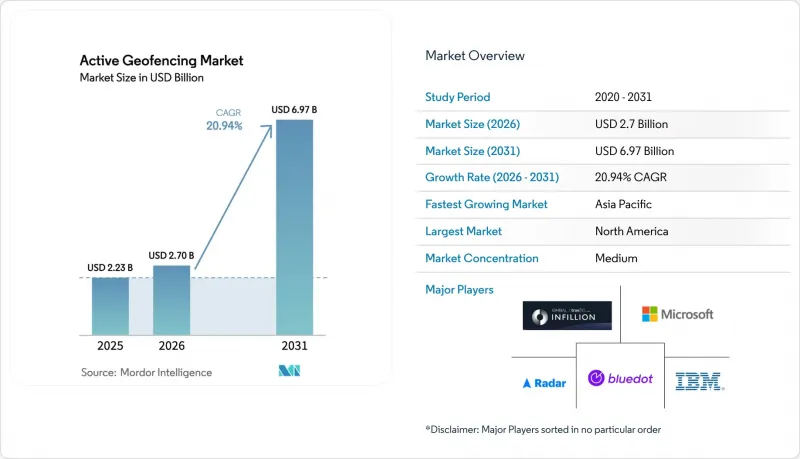
본 보고서는 구성 요소별(솔루션, 서비스), 도입 형태별(클라우드, 온프레미스, 하이브리드), 기술별(GPS/GNSS, 셀룰러 등), 최종 사용자 기업 규모별(중소기업, 대기업), 최종 사용자 산업 분야별(은행, 금융서비스 및 보험(BFSI), 소매 및 전자상거래 등), 지역별(북미, 남미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 액티브 지오펜싱 시장 동향 및 인사이트
IoT 지원 모바일 기기의 보급
2025년까지 전 세계적으로 약 300억 대의 연결 기기가 가동되었으며, 이에 따라 지오펜싱 엔진에 고해상도 위치 정보 스트림을 공급하는 고밀도 센서 네트워크가 형성될 것입니다. 최신 스마트폰은 GPS, 휴대전화, Wi-Fi RTT, Bluetooth Low Energy를 융합하여 1미터 미만의 정확도를 실현하고 있으며, 병원 내 자산 추적이나 산업 자동화 등 안전성이 극히 중요한 이용 사례를 가능하게 하고 있습니다. 5G의 초저지연 덕분에 지오펜싱의 응답 시간이 더욱 단축되어, 경보 및 제어 메시지가 미션 크리티컬한 임계치 내에서 확실하게 실행될 수 있게 됩니다.
하이퍼로컬 마케팅에 대한 수요 증가
소매업체와 패스트푸드점은 지오펜싱을 활용하여 시간 한정 혜택을 제공함으로써, 타겟을 지정하지 않은 메시지 전송에 비해 고객 확보율을 3배나 높이고 있습니다. 인쇄 매체나 옥외 광고 매체보다 낮은 CPM에 더해, 매장 방문객 수에 대한 기여도를 측정할 수 있기 때문에 주요 체인점들은 지오펜싱을 옴니채널 전략에 통합하고 있습니다. 또한, 실시간 이동 시간 모델을 기반으로 한 동적 반경 설정을 통해 메시지의 관련성이 높아져 높은 참여도를 유지하면서 광고 낭비를 줄이고 있습니다.
강화되는 소비자 개인정보 보호 규제
FTC의 기밀성이 높은 위치 정보 판매 금지 조치에 더해, 미국 통신 사업자들에게 수백만 달러 규모의 벌금이 부과됨에 따라, 각 벤더들은 세밀한 동의 관리 및 단말기 내 익명화에 대한 투자를 할 수밖에 없게 되었습니다. 유럽의 GDPR(EU 개인정보보호규정)은 여전히 전 세계적인 기준으로 자리 잡고 있으며, 위치 정보 추적에는 명시적인 옵트인과 엄격한 데이터 최소화가 요구됩니다. 미국에서는 각 주의 규정에 맞추어 액티브 지오펜싱 워크플로우를 조정해야 하며, 이에 따른 규정 준수 부담이 도입 지연으로 이어질 가능성이 있습니다.
부문 분석
솔루션 부문은 2025년 매출의 65.74%를 차지한 것으로 평가되었으며, 서비스 부문은 희소한 공간 분석 전문 지식이 필요한 설계, 도입, 최적화 업무를 기업이 외부에 위탁함에 따라 연평균 성장률(CAGR) 17.55%를 달성할 전망입니다. 시스템 통합사업자는 규정 준수 감사, 로우코드 앱 개발, 관리형 모니터링을 묶어 제공함으로써 고객이 분기가 아닌 몇 주 만에 캠페인을 시작할 수 있도록 지원하고 있습니다. 규제가 엄격한 업계에서는 서비스 제공업체가 동의 절차 및 암호화 설정을 미세 조정하여, HIPAA 및 PCI 감사를 첫 시도에서 통과할 수 있도록 지원하고 있습니다. 성과 기반 계약에 대한 수요가 증가함에 따라, 벤더들은 방문객 수 증가나 도난 건수 감소에 따라 요금을 연동하도록 유도받고 있으며, 이를 통해 인센티브의 일관성이 확보되고 고객 충성도가 높아지고 있습니다.
또한 플랫폼 벤더들은 인재 풀을 확대하기 위해 인증 프로그램을 추진하고 있으며, 대학 측에서도 위치 엔지니어링 분야의 마이크로 크레덴셜을 신설하고 있습니다. 이러한 노력으로 중소기업의 진입 장벽이 낮아지고, 액티브 지오펜싱 시장의 전체 규모가 확대되고 있습니다. 폴리곤 경계 갱신, 체류 시간 규칙 수정, 크리에이티브 자산에 대한 A/B 테스트를 수행하는 지속적인 최적화 서비스를 통해 도시의 인구 밀도, 교통 패턴, 매장 면적의 변화에 따라 캠페인의 효과를 유지할 수 있게 됩니다.
클라우드는 탄력적인 확장성과 전 세계적인 커버리지 덕분에 2025년에도 65.95%의 점유율을 유지했으나, 하이브리드 아키텍처는 기업이 기밀성이 높은 좌표 정보를 온프레미스에서 처리하면서도분석 처리를 클라우드로 오프로드할 수 있어 연평균 성장률(CAGR) 19.11%로 가장 빠르게 성장하고 있습니다. 예를 들어, 병원에서는 환자 수준의 위치 정보를 프라이빗 서브넷 내에 보관하면서 클라우드 AI를 활용해 병상 수요를 예측했습니다. 금융 기관도 유사한 패턴을 따르고 있습니다. 부정 방지를 위한 지오펜스 검사는 로컬에서 실행되는 반면, 집계된 히트맵은 마케팅 인사이트를 얻기 위해 클라우드로 전송됩니다.
엣지 디바이스(라우터, 게이트웨이, 스마트폰)에는 현재 각 위치 정보 규칙을 어디에서 실행할지 밀리초 단위로 결정하는 경량 브로커가 탑재되어 있습니다. 이러한 적응형 라우팅을 통해 안전성이 극히 중요한 알림의 지연이 줄어들고, 아웃바운드 통신 비용도 절감됩니다. 각국의 데이터 주권 관련 법률이 잇달아 제정되는 가운데, 각 벤더사는 지오펜싱 정책 엔진에 데이터 거주지 관리 기능을 결합하고 있으며, 이를 통해 여러 관할 구역에 걸친 대규모 도입 환경의 향후 대응 능력을 확보하고 있습니다.
지역별 분석
북미는 5G의 광범위한 보급, 성숙한 광고 생태계, 그리고 견조한 기업 IT 예산 덕분에 2025년에는 매출 점유율의 38.02%를 차지했습니다. 미국의 소매업체들은 로열티 앱에 지오펜싱 기능을 추가함으로써 매장 방문객 수가 두 자릿수 증가를 기록하고 있으며, 물류 사업자들은 적재장의 유휴 시간을 줄이기 위해 풀필먼트 센터에 지오펜싱을 일상적으로 도입하고 있습니다. FTC(연방거래위원회)의 명확한 집행 태도로 인해 예측 가능한 규정 준수 규칙이 확립되어, 공급업체는 규제 방향을 추측할 필요 없이 혁신을 추진할 수 있습니다. 캐나다에서는 정부 디지털 서비스 포털에서 지오펜싱이 활용되고 있으며, 멕시코에서는 전자상거래의 급속한 성장을 배경으로 택배 업체와 쇼핑몰 운영자에 의한 도입이 진행되고 있습니다.
아시아태평양은 도시화, 스마트폰 보급률의 포화, 그리고 메가시티의 스마트 인프라 프로젝트에 힘입어 2031년까지 연평균 성장률(CAGR)이 17.01%에 달하며 가장 빠르게 성장하는 지역입니다. 중국의 ‘슈퍼 앱’은 결제, 차량 호출 서비스, 지역 밀착형 상거래의 모든 영역에 지오펜싱을 통합하고 있어, 10억 명의 소비자에게 이 기술이 일상적인 것이 되었습니다. 인도의 ‘통합 물류 인터페이스 플랫폼(Unified Logistics Interface Platform)’은 운송업체의 API와 지오펜싱을 통해 검증된 배송 마일스톤을 연동하여 규제 당국에 대한 신고 절차를 효율화하고 체류료를 절감하고 있습니다. 한국과 일본의 선진적인 5G 프라이빗 네트워크 시범 프로젝트는 공장 자동화를 지원하고 있으며, 로봇 작업 셀 주변의 마이크로 지오펜스가 작업자의 안전과 자산 보호를 보장하고 있습니다.
유럽에서는 ‘프라이버시 퍼스트’ 패러다임 아래 꾸준한 성장세를 유지하고 있습니다. 스톡홀름이나 바르셀로나 같은 도시에서는 지오펜스로 구분된 ‘그린 존’을 활용해 오염 물질을 배출하는 차량을 우회시켜 교통 체증과 배기가스 감축을 도모하고 있습니다. 제조업체들은 예측 유지보수 및 사고 방지를 위해 인더스트리 4.0 생산 라인에 지오펜싱을 통합하고 있습니다. 유럽연합 집행위원회가 추진하는 도시 모빌리티 공통 데이터 레이어 구축은 상호 운용 가능한 지오펜싱 표준 제정을 촉진하여 국경을 넘는 물류의 효율화를 도모하고 있습니다. 동유럽의 물류 허브와 북유럽의 재생에너지 발전소도 해당 지역의 다양한 도입 사례에 포함되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the active geofencing market size is expected to grow from USD 2.23 billion in 2025 to USD 2.7 billion in 2026 and is forecast to reach USD 6.97 billion by 2031 at 20.94% CAGR over 2026-2031.
This report is Segmented by Component (Solutions, Services), Deployment Mode (Cloud, On-Premise, Hybrid), Technology (GPS/GNSS, Cellular, and More), End-User Enterprise Size (SMEs, Large Enterprises), End-User Industry Vertical (BFSI, Retail and E-Commerce, and More), and Geography (North America, South America, Europe, Asia Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Active Geofencing Market Trends and Insights
Proliferation of IoT-enabled Mobile Devices
Roughly 30 billion connected devices will be active worldwide by 2025, providing a dense sensor fabric that feeds high-granularity location streams into geofencing engines. Modern smartphones fuse GPS, cellular, Wi-Fi RTT, and Bluetooth Low Energy to achieve sub-meter accuracy, enabling safety-critical use cases such as hospital asset tracking and industrial automation. 5G's ultra-low latency further tightens geofence response times, ensuring that alerts or control messages execute inside mission-critical thresholds.
Rising Demand for Hyper-local Marketing
Retailers and quick-service restaurants use geofencing to push time-sensitive offers that triple acquisition rates versus untargeted messaging. Lower CPMs than print or out-of-home media, combined with measurable foot-traffic attribution, have led major chains to embed geofencing into omnichannel playbooks. Dynamic radius sizing based on real-time travel time models also raises message relevance, sustaining high engagement while lowering ad waste.
Heightened Consumer-privacy Regulations
The FTC's prohibition on selling sensitive geolocation data, combined with multimillion-dollar penalties levied on U.S. carriers, compels vendors to invest in granular consent management and on-device anonymization. Europe's GDPR remains the global template, requiring explicit opt-in for location tracking and rigorous data minimization. Adapting active geofencing workflows to multiple state-level rules in the United States adds compliance overhead that can slow roll-outs.
Other drivers and restraints analyzed in the detailed report include:
- Integration with Fleet Telematics and Last-mile Logistics
- Expansion of Drone-based Inspections
- Battery-drain and Device-performance Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solution contributed 65.74% of 2025 revenue, and the services segment is on track for 17.55% CAGR as enterprises outsource design, deployment, and optimization tasks that demand scarce spatial-analytics expertise. System integrators bundle compliance audits, low-code app development, and managed monitoring so that customers can launch campaigns in weeks instead of quarters. In regulated sectors, service providers fine-tune consent flows and encryption settings to pass HIPAA or PCI audits on the first attempt. Rising demand for outcome-based contracts is encouraging vendors to peg fees to lift in foot traffic or reduction in theft incidents, aligning incentives and deepening client stickiness.
Platform vendors also promote certification programs to enlarge the talent pool, while universities add micro-credentials in location engineering. These initiatives ease the entry barrier for small businesses and expand the overall active geofencing market. Continuous optimization services updating polygon boundaries, modifying dwell-time rules, and A/B testing creative assets ensure that campaigns remain effective as urban density, traffic patterns, or store footprints evolve
Cloud retained 65.95% share in 2025 thanks to elastic scaling and global coverage, but hybrid architectures are growing fastest at 19.11% CAGR because they let firms process sensitive coordinates on-premise while offloading analytics to the cloud. Hospitals, for example, keep patient-level location events inside a private subnet yet use cloud AI to forecast bed demand. Financial institutions follow a similar pattern: geofence checks for fraud prevention run locally, whereas aggregated heat maps go to the cloud for marketing insights.
Edge devices routers, gateways, and smartphones now host lightweight brokers that decide, in milliseconds, where to execute each location rule. This adaptive routing lowers latency for safety-critical alerts and trims egress fees. As national data-sovereignty laws proliferate, vendors bundle geo-fencing policy engines with data-residency controls, thereby future-proofing large deployments across multiple jurisdictions.
Complete Report Scope:
- By Component
- Solution
- Services
- By Deployment Mode
- Cloud
- On-premise
- Hybrid
- By Technology
- GPS/GNSS
- Cellular
- Wi-Fi/BLE
- RFID/NFC
- UAV/Drone Geofencing Systems
- By End-User Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By End-User Industry Vertical
- Banking, Financial Services and Insurance (BFSI)
- Retail and E-commerce
- Transportation and Logistics
- Healthcare and Life Sciences
- Government and Defense
- Industrial Manufacturing
- Media and Entertainment
- Other End-user Industry Vertical
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- ASEAN
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 38.02% revenue share in 2025 owing to widespread 5G coverage, mature advertising ecosystems, and strong enterprise IT budgets. U.S. retailers report double-digit foot-traffic lift when adding geofencing to loyalty apps, and logistics providers routinely geofence fulfilment centres to shave loading-dock idle time. The FTC's clear enforcement stance creates predictable compliance rules that let vendors innovate without guessing the regulatory direction. Canada leverages geofencing in government digital-service portals, while Mexico's e-commerce boom fuels adoption among parcel carriers and mall operators.
Asia Pacific is the fastest-growing region at 17.01% CAGR through 2031, helped by urbanization, smartphone saturation, and megacity smart-infrastructure projects. China's "super-apps" embed geofencing across payments, ride-hailing, and local commerce, normalizing the technology for 1 billion consumers. India's Unified Logistics Interface Platform links carrier APIs with geofence-verified delivery milestones, streamlining regulatory filings and reducing demurrage. Advanced 5G private-network pilots in South Korea and Japan support factory automation, where micro-geofences around robotic workcells ensure worker safety and asset protection.
Europe maintains steady momentum under a privacy-first paradigm. Cities such as Stockholm and Barcelona use geofenced "green zones" to redirect polluting vehicles, cutting congestion and emissions. Manufacturers integrate geofencing into Industry 4.0 lines for predictive maintenance and accident prevention. The European Commission's push for common urban-mobility data layers is spurring interoperable geofencing standards, enhancing cross-border logistics efficiency. Eastern European logistics hubs and Nordic renewable-energy plants add to a diverse set of regional deployments.
- Google LLC
- Apple Inc.
- Microsoft Corporation
- IBM Corporation
- Amazon Web Services, Inc.
- ESRI, Inc.
- Bluedot Innovation Pty Ltd
- Radar Labs Inc.
- Infillion Inc. (Gimbal)
- Verve Group, Inc.
- HERE Technologies
- Qualcomm Technologies, Inc.
- GeoComply Solutions Inc.
- LocationSmart
- Skyhook Holdings, Inc.
- Samsung Electronics Co., Ltd.
- Oracle Corporation
- SAP SE
- TomTom International B.V.
- Uber Technologies, Inc. (Uber Map Services)
- Unacast, Inc.
- Foursquare Labs, Inc.
- SZ DJI Technology Co., Ltd.
- Geofeedia, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of IoT-enabled mobile devices driving precise location data
- 4.2.2 Rising demand for hyper-local marketing among retailers and QSRs
- 4.2.3 Integration of geofencing in fleet telematics and last-mile logistics
- 4.2.4 Expansion of drone-based industrial inspections requiring dynamic geofence safety zones
- 4.2.5 Government smart-city initiatives mandating geo-aware public services
- 4.2.6 Emergence of spatial computing and AR platforms needing real-time geofencing layers
- 4.3 Market Restraints
- 4.3.1 Heightened consumer-privacy regulations limiting persistent tracking
- 4.3.2 Battery-drain and device-performance concerns with always-on apps
- 4.3.3 Fragmented accuracy across indoor/outdoor geolocation technologies
- 4.3.4 Competitive substitution from broad LBS platforms commoditising geofencing
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solution
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.2.3 Hybrid
- 5.3 By Technology
- 5.3.1 GPS/GNSS
- 5.3.2 Cellular
- 5.3.3 Wi-Fi/BLE
- 5.3.4 RFID/NFC
- 5.3.5 UAV/Drone Geofencing Systems
- 5.4 By End-User Enterprise Size
- 5.4.1 Small and Medium Enterprises (SMEs)
- 5.4.2 Large Enterprises
- 5.5 By End-User Industry Vertical
- 5.5.1 Banking, Financial Services and Insurance (BFSI)
- 5.5.2 Retail and E-commerce
- 5.5.3 Transportation and Logistics
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Government and Defense
- 5.5.6 Industrial Manufacturing
- 5.5.7 Media and Entertainment
- 5.5.8 Other End-user Industry Vertical
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Australia and New Zealand
- 5.6.4.6 ASEAN
- 5.6.4.7 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Kenya
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Google LLC
- 6.4.2 Apple Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 IBM Corporation
- 6.4.5 Amazon Web Services, Inc.
- 6.4.6 ESRI, Inc.
- 6.4.7 Bluedot Innovation Pty Ltd
- 6.4.8 Radar Labs Inc.
- 6.4.9 Infillion Inc. (Gimbal)
- 6.4.10 Verve Group, Inc.
- 6.4.11 HERE Technologies
- 6.4.12 Qualcomm Technologies, Inc.
- 6.4.13 GeoComply Solutions Inc.
- 6.4.14 LocationSmart
- 6.4.15 Skyhook Holdings, Inc.
- 6.4.16 Samsung Electronics Co., Ltd.
- 6.4.17 Oracle Corporation
- 6.4.18 SAP SE
- 6.4.19 TomTom International B.V.
- 6.4.20 Uber Technologies, Inc. (Uber Map Services)
- 6.4.21 Unacast, Inc.
- 6.4.22 Foursquare Labs, Inc.
- 6.4.23 SZ DJI Technology Co., Ltd.
- 6.4.24 Geofeedia, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


