

|
시장보고서
상품코드
2122280
하드웨어 지갑 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hardware Wallet - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
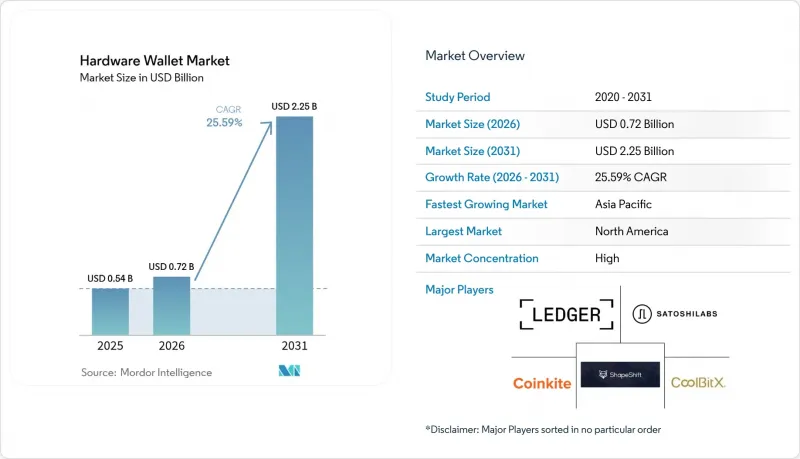
에 의하면, 하드웨어 지갑 시장 규모는 2025년 5억 4,000만 달러에서 2026년에는 7억 2,000만 달러, 2031년까지 22억 5,000만 달러에 이르고, 2026-2031년 CAGR 25.6%를 기록할 전망입니다.

본 보고서는 연결 방식(USB, NFC, 블루투스, 기타), 지갑 유형(핫 월렛, 콜드 월렛), 최종 사용자별(개인·소매, 기관·기업), 유통 채널(온라인, 오프라인), 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 하드웨어 지갑 시장 동향 및 인사이트
기관 투자자들의 자체 관리 솔루션 도입 가속화
기업의 재무 부서, 패밀리 오피스, 연금 운용사는 FTX의 파산과 15억 달러 규모의 Bybit 보안 침해 사건을 계기로, 거래소 보관의 편의성보다 상대방 리스크가 더 크다는 결론에 도달하여 기기 조달을 가속화했습니다. Gnosis Safe는 하드웨어로 보호되는 다중 서명 계약을 통해 보호되는 자산이 2025년에 1,000억 달러를 돌파했다고 밝히며, 다층 거버넌스가 분산형 자율 조직(DAO)에서 주류가 되고 있음을 뒷받침했습니다. 미국 은행은 해석 지침 1170호 및 1172호에 따라 암호화폐를 보관할 수 있지만, 많은 기관은 여전히 키 관리 권한을 완전히 보유하기 위해 On-Premise 콜드 월렛을 선호하고 있습니다. 유럽에서는 MiCA 제76조에 따라 제공업체는 고객 자산을 분리 보관해야 할 의무가 있으며, 이 요건은 하드웨어로 보호되는 콜드 스토리지를 통해 가장 쉽게 충족될 수 있습니다. 2024년 1월 비트코인 현물 상장지수펀드(ETF)의 승인으로 감사에 대한 기대가 높아지면서, 평가 보증 수준 5(EAL5) 인증이 기업의 구매에 있어 사실상 표준이 되었습니다.
사이버 침해 보도 급증에 따른 오프라인 키 수요 증가
뉴스 헤드라인을 장식하는 해킹 사건들은 인터넷에 연결된 키가 공격자를 유인한다는 사실을 구매자들에게 다시금 일깨워주고 있습니다. 라자루스 그룹의 소행으로 추정되는 Bybit에 대한 공격은 2024년 3월 Safe{Wallet}의 컨텐츠 전송 네트워크 침해 사건과 마찬가지로, 완벽한 에어 갭을 갖춘 기기의 판매 급증을 촉발했습니다. ELLIPAL 및 Keystone과 같은 공급업체들은 각 사건 발생 후 몇 주 이내에 주문 수가 3자리 수로 증가했다고 보고했습니다. 2024년 인터넷 기술 태스크포스(IETF)가 제정한 포스트 양자 키 캡슐화 관련 표준 초안은 제조업체에 명확한 구현 로드맵을 제공하여 소비자의 신뢰를 더욱 높였습니다. 일반 사용자들도 위조 기기를 보내는 피싱 공격에 직면하고 있어, 첫 사용 전에 제조업체의 앱을 통해 홀로그램 스티커를 확인할 것을 권고받고 있습니다. 전반적으로 보안 침해에 대한 보도는 거래소에서 자금을 인출하여 냉장 보관으로 옮기기로 하는 의사 결정 주기를 단축시키고 있습니다.
여전히 남아 있는 소비자 경험(UX)의 복잡성
처음 사용하는 사용자에게는 시드 문구 백업, 펌웨어 업데이트, 주소 확인과 같은 작업이 여전히 진입 장벽으로 느껴집니다. Tangem의 화면이 없는 카드형 지갑은 초기 설정을 간소화했지만, 거래 확인이 스마트폰에서만 이루어지기 때문에 구매자는 ‘눈 감고 서명’하는 위험에 노출되어 있습니다. Ledger의 Nano Gen5는 대형 디스플레이와 블루투스 페어링을 통해 가시성을 높였지만, 사용자는 결제를 승인하기 전에 여전히 주소 전체를 스크롤하여 확인해야 합니다. 표준의 불일치가 혼란을 가중시키고 있습니다. BIP39와 SLIP39는 호환되지 않는 백업을 생성하기 때문에 여러 브랜드를 함께 사용하는 가정에서는 서로 다른 복원 워크플로를 동시에 관리해야 합니다. OpenZeppelin의 ERC-7913은 비-EVM 키를 이더리움 계약과 연동하는 것을 목표로 하고 있지만, 그 채택은 여전히 고급 사용자로 제한되어 있습니다. 일반 구매자가 모바일 뱅킹만큼 직관적인 워크플로를 체감할 수 있게 될 때까지는 암호화폐의 보급 곡선에 비해 지갑의 보급은 뒤처질 것으로 보입니다.
부문 분석
USB 장치는 2025년 매출의 45.21%를 차지하고 있으며, 무선 통신 기능을 일절 거부하는 기업의 서명자에게는 감사 대응에 뛰어난 기본 선택지로서의 역할이 확인되고 있습니다. 한편, 블루투스 지갑은 2031년까지 연평균 성장률(CAGR) 26.0%로 확대될 전망이며, 기기 화면을 통한 인증이 중간자 공격에 대한 우려를 완화함에 따라 USB 지갑의 선두 위상은 점차 축소될 것으로 보입니다. 금융 기관에서 하드웨어 지갑 시장의 우위는 여전히 유선 모델에 있지만, 일반 소비자층은 대면 결제나 분산형 앱(DApp) 이용 시 스마트폰과 원활하게 페어링할 수 있다는 점 때문에 블루투스 모델을 선호하는 경향이 있습니다. Tangem의 NFC 카드 번들 및 Coinkite의 Coldcard Q는 도청 범위를 제한하는 비접촉식 서명 기능을 갖춘 중도적인 선택지로 자리 잡고 있습니다. 대조적으로, Keystone이나 ELLIPAL의 QR 코드 지원 에어 갭 제품은 무선 통신을 완전히 차단하고 있어, 속도를 희생하더라도 최대한의 보안을 추구하는 부유층 사용자를 끌어들이고 있습니다. 모든 연결 유형용 펌웨어에는 조만간 기존 키 교환과 래티스 키 교환을 결합한 하이브리드 방식이 통합될 전망입니다. 또한 무선 업데이트로 인해 냉장 보관에 대한 순수주의가 일시적으로 모호해질 가능성도 있지만, 보급 곡선을 보면 모바일 우선 사용자층에서 블루투스가 USB의 점유율을 서서히 잠식해 나갈 것으로 보입니다.
USB는 서벤스-옥슬리법의 내부 통제 프레임워크를 충족하는 불변의 감사 추적을 남기기 때문에 다중 서명을 통한 자금 관리 워크플로우에서 여전히 필수적입니다. 따라서 소비자용 지갑의 무선화가 진행되더라도, 수탁업체 내 USB 지원 하드웨어 지갑 시장 점유율은 계속해서 높은 수준을 유지할 것으로 보입니다. 단기적인 블루투스의 성장은 과거 암호화폐 사이클을 건너뛴 기존 사용자를 위해 설계되고, 조작하기 쉬운 컴패니언 앱의 출시에도 달려 있습니다. 전반적으로 양극화된 추세가 예상됩니다. 하드웨어 지갑 시장에서는 블루투스 제품의 출하 대수가 수량 면에서의 성장을 견인하는 한편, USB는 기관 투자자층의 핵심에서 가치 밀도를 계속 유지할 것으로 보입니다.
MiCA 제76조와 미국 은행 권고에 따른 엄격한 분리 조항 덕분에 콜드 월렛은 2025년 매출의 63.19%를 차지했습니다. 보험사는 키가 평가 보증 수준 5(EAL5) 이상의 보안 요소에 보관되어 있는 경우에만 보험료를 환급하기 때문에 이러한 우위는 2031년까지 연평균 성장률(CAGR) 26.2%로 지속될 것으로 전망됩니다. 핫 월렛의 하드웨어 지갑 시장 규모는 여전히 소규모이며, 주로 실시간 서명이 필요한 탈중앙화 금융(DeFi) 트레이더를 대상으로 합니다. 그러나 Bybit 해킹 사건 등 공개되는 각 익스플로잇 사례로 인해 온라인 키에 대한 리스크 프리미엄에 대한 인식이 높아지고 있습니다. Ledger의 Nano Gen5와 같은 기기는 블루투스 세션 중에도 키를 보안 요소 내에 격리함으로써 콜드 월렛의 보안성과 핫 월렛의 편의성을 융합하려 하고 있으며, 이로 인해 카테고리 간의 경계가 모호해지고 있습니다.
보험사나 규정 준수 감사 기관은 여전히 에어갭을 필수 요건으로 간주하고 있기 때문에 트레이더가 웹 확장 기능에 소액의 잔고를 보유하고 있는 경우에도 기업의 재무 담당자는 콜드 스토리지 하드웨어 지갑을 계속 일괄 구매하고 있습니다. 규정 문구에는 해석의 여지가 거의 없기 때문에 냉장 보관용 하드웨어 지갑 시장 점유율은 서서히 상승할 가능성이 있습니다. 향후 포스트 양자암호화의 도입이 의무화되면, 보유 기간이 길다는 특성상 콜드 부문에 집중된 업데이트 주기가 유발될 것으로 예측됩니다.
지역별 분석
2025년, 북미는 전 세계 매출의 38.95%를 차지했습니다. 이는 통화감독청(OCC)의 조기 규제 명확화와 증권거래위원회(SEC)의 ETF 승인에 힘입은 결과입니다. 기관 자산 운용사는 감사 통과를 위해 평가 보증 레벨 5(EAL5) 장치를 필수로 요구하고 있으며, 미국에 본사를 둔 분산형 자율 조직(DAO)의 재무 부문은 다중 서명 계약 내 자산의 상당 부분을 차지하고 있습니다. 캐나다에서는 주 규제 당국이 시행하는 규정 중심의 분리 프레임워크 덕분에, 규모는 작지만 꾸준한 개인 투자자의 자금 유입이 관찰되었습니다. 한편, 멕시코의 이용 사례는 국경 간 송금에서 NFC 카드 지갑이 선호되는 송금 경로에 중점을 두고 있습니다. 이러한 동향들이 결합되어 높은 가치의 기반이 확립되었으며, 포스트 양자 기술에 대한 강화가 이루어질 때마다 기업들의 장비 교체 주문이 지속적으로 발생하고 있습니다.
2024년 12월부터 완전히 시행되고 있는 유럽의 MiCA 제도는 결제 기관이 제76조의 요건을 충족하기 위해 커스토디 스택을 업그레이드함에 따라 광범위한 하드웨어 교체 주기를 촉발했습니다. 독일은 보유자에게 냉장 보관을 의무화하는 40건의 암호화폐 보관 라이선스를 발급했으며, 프랑스의 PSAN 레지스트리도 유사한 오프라인 요건을 적용하고 있습니다. 유럽은행감독청(EBA)은 모범 사례로 평가 보증 수준 6+를 권장하고 있으며, 이는 장치의 평균 가격 상승을 부추기고 있습니다. 영국은 브렉시트 이후의 규제를 MiCA에 부합하도록 조정하고 있는 반면, 이탈리아와 스페인은 개인용 시장 침투에서는 뒤처지고 있지만, 패밀리 오피스를 통한 투자를 통해 기관용 시장에서는 증가 추세를 보이고 있습니다.
중동은 2031년까지 26.5%라는 지역별 최고 연평균 성장률(CAGR)을 나타낼 전망입니다. 이는 아랍에미리트(UAE)의 국부펀드와 사우디아라비아에서 수립 중인 수탁 체계가 주도하고 있습니다. 두바이의 VARA 라이선스에는 안전한 키 관리가 명시적으로 규정되어 있어, 현지 카스토디언들은 인증된 기기를 대량으로 주문하고 있습니다. 바레인과 카타르도 유사한 지침을 제시하고 있으며, 걸프 지역 부유층은 고급 가전 전문점에서 직접 구매하는 것을 선호합니다. 아프리카 시장은 여전히 소규모이지만, 남아프리카공화국과 나이지리아에서는 활기를 띠고 있으며, 이들 국가에서는 하드웨어 지갑이 통화 평가절하나 자본 규제와 같은 역풍을 해소하고 있습니다.
아시아태평양에서는 홍콩과 싱가포르에서 급속한 보급이 관찰됩니다. 두 지역 모두 분리 보관을 의무화하는 완전한 라이선스 제도가 마련되어 있습니다. 일본에서는 ‘지급 서비스법’ 개정에 따라 거래소 규제가 강화되면서, 회의적인 개인 투자자들이 자가 관리로 방향을 틀고 있습니다. 호주에서는 규제에 관한 협의가 계속되고 있지만, 구매자들이 정책의 불확실성에 대한 헤지 수단으로 하드웨어 지갑을 구매하고 있어 판매는 주춤하지 않고 있습니다. 인도에서는 과세에 대한 불투명성으로 인해 여전히 상황이 불안정하지만, 때때로 거래소 폐쇄설이 돌고 있음에도 일반 가정의 관심은 식지 않고 있습니다. 중국 본토는 2021년 거래 금지 조치의 영향으로 침체된 상태가 지속되고 있어, 해당 지역의 성장 여지는 제한적입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the hardware wallet market size is expected to increase from USD 0.54 billion in 2025 to USD 0.72 billion in 2026 and reach USD 2.25 billion by 2031, growing at a CAGR of 25.6% over 2026-2031.
This report is Segmented by Connectivity (USB, NFC, Bluetooth, and More), Wallet Type (Hot Wallet, and Cold Wallet), End User (Individual/Retail, and Institutional/Enterprise), Distribution Channel (Online, and Offline), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Hardware Wallet Market Trends and Insights
Intensifying Institutional Adoption of Self-Custody Solutions
Corporate treasuries, family offices, and pension managers accelerated device procurement after the FTX collapse and the USD 1.5 billion Bybit breach, concluding that counterparty risk outweighs the convenience of exchange custody. Gnosis Safe disclosed that assets protected by hardware-backed multi-signature contracts topped USD 100 billion in 2025, confirming that multi-layer governance has become mainstream for decentralized autonomous organizations. United States banks can custody crypto under Interpretive Letters 1170 and 1172, yet many institutions still prefer on-premises cold wallets to maintain total key control. In Europe, MiCA Article 76 obliges providers to segregate client assets, a requirement satisfied most easily with hardware-secured cold storage. The January 2024 approval of spot Bitcoin exchange-traded funds hardened audit expectations, making Evaluation Assurance Level 5 certification the de facto baseline for enterprise purchases.
Surge In Cyber-Breach Publicity Pushing Demand for Offline Keys
Headline hacks remind buyers that internet-connected keys invite adversaries. The Bybit attack attributed to the Lazarus Group triggered a sales spike for fully air-gapped devices, as did the March 2024 compromise of Safe{Wallet}'s content delivery network. Vendors such as ELLIPAL and Keystone reported triple-digit order growth within weeks of each incident. Draft standards on post-quantum key encapsulation finalized by the Internet Engineering Task Force in 2024 gave manufacturers a clear implementation roadmap, further bolstering consumer confidence. Retail users also confront phishing campaigns that ship counterfeit devices, prompting them to verify holographic seals via manufacturer apps before first use. Altogether, publicity around breaches shortens the decision cycle for moving funds off exchanges and into cold storage.
Persistent Consumer UX Complexity
First-time users still find seed-phrase backup, firmware updates, and address verification intimidating. Tangem's screen-less card wallets simplify onboarding but expose buyers to blind-signing risk because transactions are confirmed only on a smartphone. Ledger's Nano Gen5 improves readability through a larger display and Bluetooth pairing, yet users must still scroll full addresses before approving payments. Standards divergence compounds confusion: BIP39 and SLIP39 generate incompatible backups, so households with multiple brands juggle different recovery workflows. OpenZeppelin's ERC-7913 aims to bridge non-EVM keys into Ethereum contracts, but adoption remains limited to advanced users. Until mainstream buyers see workflows as intuitive as mobile banking, adoption will trail the broader crypto ownership curve.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Segregated Crypto Custody (MiCA, OCC)
- Integration Of Secure Element Chips with Post-Quantum Cryptography Support
- Hardware Supply-Chain Shortages for Secure Elements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
USB devices owned 45.21% of 2025 revenue, confirming their role as the audit-friendly default for enterprise signers who refuse any radios. Bluetooth wallets, however, are set to expand at a 26.0% CAGR through 2031, shrinking the USB lead as screen-on-device verification mitigates man-in-the-middle concerns. The hardware wallet market size advantage still belongs to wired models among financial institutions, yet retail buyers gravitate to Bluetooth because it pairs seamlessly with smartphones during in-person payments or decentralized-app interactions. Tangem's NFC card bundle and Coinkite's Coldcard Q illustrate a middle path, offering contactless signing that limits interception range. In contrast, QR-code air-gap products from Keystone and ELLIPAL isolate radio entirely, attracting high-net-worth users who trade speed for maximal security. Firmware for all connectivity types will soon integrate hybrid classical-and-lattice key exchange, and over-the-air updates may momentarily blur cold-storage purism, but adoption curves suggest Bluetooth will keep eroding USB share among mobile-first demographics.
USB remains indispensable for multi-signature treasury workflows because it leaves an immutable audit trail that satisfies Sarbanes-Oxley internal-control frameworks. Hardware wallet market share for USB will therefore stay overweight inside custodians, even as consumer-grade portfolios turn wireless. Near-term Bluetooth growth also hinges on the rollout of easier-to-navigate companion apps designed for grandfathered users who skipped prior crypto cycles. Overall, expect a bifurcated path: hardware wallet market Bluetooth shipments lead volume growth, while USB retains value density in the institutional core.
Cold wallets captured 63.19% of 2025 sales thanks to strict segregation clauses under MiCA Article 76 and United States banking advisories. That dominance will persist with a 26.2% CAGR to 2031 because insurance carriers rebate premiums only when keys rest in Evaluation Assurance Level 5 or better secure elements. The hardware wallet market size for hot wallets remains modest, catering chiefly to decentralized-finance traders who need real-time signing. Yet each publicized exploit, such as the Bybit breach, widens the perceived risk premium on online keys. Devices like Ledger's Nano Gen5 try to blend cold-wallet security with hot-wallet convenience by isolating keys in secure elements even during Bluetooth sessions, softening the boundary between categories.
Insurance carriers and compliance auditors continue to treat airgap as table stakes, so corporate treasurers still bulk-buy cold storage even when traders keep small balances in web extensions. Hardware wallet market share for cold storage may inch higher because regulatory language leaves little room for alternative interpretations. Looking forward, the mandatory adoption of post-quantum cryptography will likely trigger refresh cycles concentrated in the cold segment, given its longer retention horizons.
Complete Report Scope:
- By Connectivity
- USB
- NFC
- Bluetooth
- Others, Connectivity
- By Wallet Type
- Hot Wallet
- Cold Wallet
- By End User
- Individual / Retail
- Institutional / Enterprise
- By Distribution Channel
- Online
- Offline
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 38.95% of global revenue in 2025, energized by early regulatory clarity from the Office of the Comptroller of the Currency and the Securities and Exchange Commission ETF approvals. Institutional asset managers insist on Evaluation Assurance Level 5 devices to pass audits, and decentralized-autonomous-organization treasuries headquartered in the United States represent a large share of assets inside multi-signature contracts. Canada's prescriptive segregation framework, enforced by provincial regulators, brought small but steady retail inflows, while Mexico's use case centers on remittance corridors that favour NFC card wallets for cross-border transfers. Combined, these trends anchor a high-value base that continues to spin off enterprise refresh orders each time post-quantum enhancements arrive.
Europe's MiCA regime, fully live since December 2024, ignited a broad hardware replacement cycle as payment institutions upgraded custody stacks to meet Article 76 mandates. Germany issued 40 crypto-custody licenses that bind holders to cold storage, and France's PSAN registry applies similar offline requirements. The European Banking Authority has suggested Evaluation Assurance Level 6+ as best practice, driving higher average device prices. The United Kingdom is aligning post-Brexit rules with MiCA, while Italy and Spain trail on retail penetration yet show institutional upticks via family-office allocations.
The Middle East will record the fastest regional CAGR at 26.5% through 2031, driven by sovereign funds in the United Arab Emirates and pending custody frameworks in Saudi Arabia. Dubai's VARA licensing explicitly references secure key management, so local custodians place bulk orders for certified devices. Bahrain and Qatar have followed with similar directives, and high-net-worth individuals in the Gulf favour in-person purchases at upscale electronics boutiques. Africa's market remains small but vibrant in South Africa and Nigeria, where hardware wallets solve currency-devaluation and capital-control headwinds.
Asia-Pacific features pockets of rapid adoption in Hong Kong and Singapore, each with full licensing that insists on segregated custody. Japan tightened exchange rules under its amended Payment Services Act, pushing sceptical retail holders toward self-custody. Australia's ongoing regulatory consultations have not slowed hardware sales, as buyers hedge against policy uncertainty. India remains volatile due to taxation ambiguities, but household interest persists despite occasional exchange-shutdown rumours. Mainland China stays chilled by the 2021 trading ban, limiting regional upside.
- Ledger SAS
- SatoshiLabs s.r.o.
- ShapeShift AG
- Coinkite Inc.
- CoolBitX Technology Ltd.
- Shift Crypto AG
- Penta Security Systems Inc.
- SecuX Technology Inc.
- ARCHOS S.A.
- ELLIPAL Ltd.
- BitLox Limited
- SafePal Technology Ltd.
- Keystone (Cobo Technology Ltd.)
- OPOLO SARL
- zSofitto NV (Sugi)
- KeepKey LLC
- IoTrust Co., Ltd. (D'CENT)
- Prokey Technologies Co., Ltd.
- CryoBit LLC
- BC VAULT d.o.o.
- Tangem AG
- OneKey Technology Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Intensifying Institutional Adoption of Self-Custody Solutions
- 4.2.2 Surge in Cyber-Breach Publicity Pushing Demand for Offline Keys
- 4.2.3 Regulatory Push for Segregated Crypto Custody (MiCA, OCC)
- 4.2.4 Integration of Secure Element Chips with Post-Quantum Cryptography Support
- 4.2.5 Rising Demand for Multi-Signature Workflows in DAO Treasury Management
- 4.2.6 Insurance Underwriters Providing Premium Rebates for Certified Hardware Wallets
- 4.3 Market Restraints
- 4.3.1 Persistent Consumer UX Complexity
- 4.3.2 Hardware Supply-Chain Shortages for Secure Elements
- 4.3.3 Lack of Uniform Seed Phrase Recovery Standards Across Wallets
- 4.3.4 Growing Secondary Grey-Market Reselling Increasing Counterfeit Risk
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Hardware Wallet Product Comparison
- 4.9 Impact of Macroeconomic Factors
- 4.10 Case Study Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Connectivity
- 5.1.1 USB
- 5.1.2 NFC
- 5.1.3 Bluetooth
- 5.1.4 Others, Connectivity
- 5.2 By Wallet Type
- 5.2.1 Hot Wallet
- 5.2.2 Cold Wallet
- 5.3 By End User
- 5.3.1 Individual / Retail
- 5.3.2 Institutional / Enterprise
- 5.4 By Distribution Channel
- 5.4.1 Online
- 5.4.2 Offline
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Australia
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Ledger SAS
- 6.4.2 SatoshiLabs s.r.o.
- 6.4.3 ShapeShift AG
- 6.4.4 Coinkite Inc.
- 6.4.5 CoolBitX Technology Ltd.
- 6.4.6 Shift Crypto AG
- 6.4.7 Penta Security Systems Inc.
- 6.4.8 SecuX Technology Inc.
- 6.4.9 ARCHOS S.A.
- 6.4.10 ELLIPAL Ltd.
- 6.4.11 BitLox Limited
- 6.4.12 SafePal Technology Ltd.
- 6.4.13 Keystone (Cobo Technology Ltd.)
- 6.4.14 OPOLO SARL
- 6.4.15 zSofitto NV (Sugi)
- 6.4.16 KeepKey LLC
- 6.4.17 IoTrust Co., Ltd. (D'CENT)
- 6.4.18 Prokey Technologies Co., Ltd.
- 6.4.19 CryoBit LLC
- 6.4.20 BC VAULT d.o.o.
- 6.4.21 Tangem AG
- 6.4.22 OneKey Technology Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


