|
시장보고서
상품코드
2122296
데이터 분석 아웃소싱 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Data Analytics Outsourcing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 데이터 분석 아웃소싱 시장 규모는 2025년에 108억 9,000만 달러로 평가되었고, 2026년 145억 4,000만 달러에서 2031년까지 615억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 33.47%를 나타낼 전망입니다.
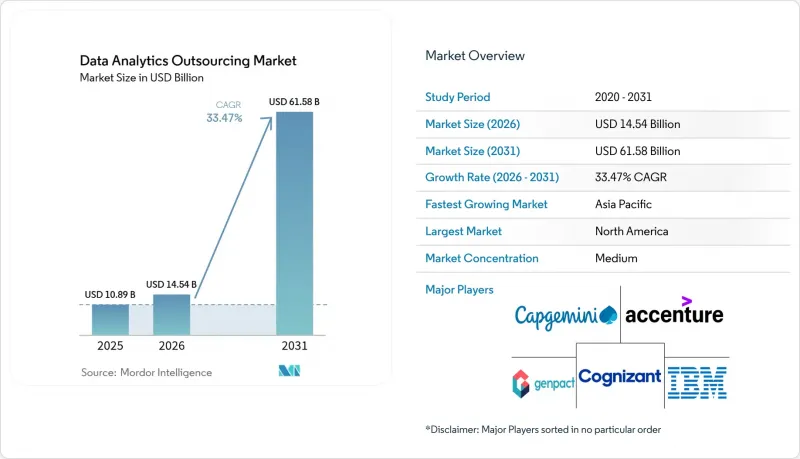
본 보고서는 분석 유형별(기술적 분석, 진단적 분석 등), 최종 사용자 산업별(소매 및 전자상거래, BFSI 등), 서비스 모델별(오프쇼어, 니어쇼어, 온쇼어/온사이트), 조직 규모별(대기업 및 중소기업), 도입 모델별(클라우드 전용 및 하이브리드 클라우드), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 데이터 분석 아웃소싱 시장 동향 및 인사이트
급증하는 기업 데이터의 양과 복잡성
현재 전 세계 조직들은 모바일 앱, IoT 기기, 옴니채널 접점을 통해 페타바이트 규모의 구조화 데이터, 반구조화 데이터, 비구조화 데이터를 생성하고 있으며, 이는 사내 처리 능력을 압도하고 있습니다. 데이터 엔지니어링 및 머신러닝에 대한 사내 역량이 제한적인 점도 처리 속도를 더욱 저해하고 있습니다. 아웃소싱 파트너는 미리 구축된 데이터 수집 파이프라인, 확장 가능한 클라우드 인프라, 그리고 산업별 데이터 모델을 활용하여 이러한 격차를 해소하고, 인사이트 확보까지 걸리는 시간을 단축하는 동시에 총 소유 비용(TCO)을 절감하고 있습니다. 많은 고객사는 종량제 방식의 ‘데이터-어-서비스(Data-as-a-Service)’ 계약을 채택하고 있으며, 변동 가격의 이점을 활용하여 제한된 자본을 핵심 혁신 전략으로 재분배할 수 있게 되었습니다.
옴니채널 커머스에서의 준실시간 의사결정 필요성
디지털 쇼핑객은 웹, 모바일, 오프라인 매장 등 어떤 채널을 이용하든 즉각적인 개인화와 원활한 재고 가시성을 기대합니다. 이러한 기대에 따라 이벤트 스트림 처리, 추천 알고리즘 업데이트, 그리고 밀리초 단위의 개입을 가능하게 하는 분석 엔진에 대한 수요가 높아지고 있습니다. 이러한 저지연 스택을 사내에서 구축하려면 스트림 처리 플랫폼, 인메모리 데이터베이스, 엣지 서버에 대한 막대한 설비 투자가 필요합니다. 전문 아웃소싱 벤더는 연중무휴 24시간 운영 지원을 갖춘 턴키 방식의 실시간 분석 플랫폼을 제공하며, 소매업체와 소비자 브랜드는 고정 투자를 사용량에 따른 변동 요금제로 전환하면서 신속하게 본격적인 운영을 시작할 수 있습니다.
데이터 상주 요건 및 국경을 넘는 데이터 전송에 관한 규제
GDPR(EU 개인정보보호규정)의 시행과 향후 제정될 AI 관련 법령에 따라 시민 데이터의 저장 및 처리 장소에 관한 규제가 강화되고 있습니다. 다국적 기업들은 규정 준수 문서, 안전한 연결성 및 지오펜싱 기능을 확보하기 위해 벤더의 포트폴리오를 재검토하고 있습니다. 현재 아웃소싱 계약에는 하도급 처리자에 관한 상세한 공개 사항 및 감사 조항이 포함되어 있어, 이로 인해 법적 복잡성이 증가하고 계약 체결까지의 기간이 길어지거나, 인증된 현지 시설을 보유하지 않은 공급업체의 비용이 증가할 가능성이 있습니다.
부문 분석
2025년에는 처방형 도구가 총 수익의 39.48%를 차지하며 예측 모델을 제쳤으나, 기업들이 사후적인 대시보드보다 권장 사항을 점점 더 많이 요구함에 따라 그 점유율은 계속 상승하고 있습니다. 처방형 솔루션 분야의 데이터 분석 아웃소싱 시장 규모는 2026-2031년 연평균 성장률(CAGR) 34.32%로 확대될 것으로 예측됩니다. 각 아웃소싱 파트너사는 시나리오 최적화 엔진과 대화형 AI를 통합하여 차별화를 꾀하고, 전문 코딩 인력이 필요 없는 의사 결정 자동화를 실현하고 있습니다.
생성형 AI는 도메인 전문가가 비즈니스 제약을 자연어로 표현할 수 있게 하고, 엔진이 이를 최적화 로직으로 변환함으로써 처방적 분석을 더욱 보급하고 있습니다. 각 벤더는 모델 거버넌스, 버전 관리 및 규제상 설명 가능성을 관리하는 프레임워크를 통합하여, 단순한 보고서 작성자가 아닌 전략적 의사 결정의 파트너로서의 입지를 확립하고 있습니다. 고객의 기대가 지속적인 개선으로 전환되는 가운데, 각 제공업체는 반복적인 모델 튜닝 및 A/B 테스트를 성과 기반 계약에 포함시켜 계약 기간 전반에 걸쳐 가치 실현을 보장하고 있습니다.
BFSI(은행 및 금융 및 보험) 부문은 신용 리스크 스코어링, 사기 감지, 규제 보고에 대한 다년간의 투자를 통해 2025년 데이터 분석 아웃소싱 시장 점유율의 27.05%를 차지했습니다. 그럼에도 불구하고 원격 의료의 보급, 전자 건강 기록의 통합, 그리고 맞춤형 의료 프로토콜에 힘입어 헬스케어 분야는 2031년까지 연평균 성장률(CAGR) 34.15%라는 가장 빠른 성장세를 보이고 있습니다. HIPAA 준수 데이터 레이크 및 사전 인증된 임상 분석 라이브러리를 제공하는 공급업체는 선구자로서의 우위를 누리고 있습니다.
생명과학 기업들은 실세계 증거 수집 및 유전체 시퀀싱 분석의 아웃소싱을 늘리고 있어, 전문적인 도메인 지식을 갖춘 벤더들에게 높은 수익 기회를 창출하고 있습니다. 한편, 보험사는 분석 기업과 제휴하여 보험 청구 데이터와 웨어러블 센서 입력 데이터를 결합함으로써, 입원 비용을 절감하는 조기 경보 모델을 추진하고 있습니다. 지불자와 의료 제공업체가 가치 기반 의료(value-based care)로 수렴함에 따라, 임상 데이터, 행동 데이터 및 건강의 사회적 결정 요인 데이터를 포괄하는 환자의 경과 시간에 따른 분석에 대한 수요가 증가하고 있습니다.
지역별 분석
북미는 2025년 매출의 38.35%를 차지했으며, 이는 해당 지역의 풍부한 기업 기술 예산, 성숙한 규제 체계, 그리고 성과 기반 벤더 계약의 조기 도입을 반영합니다. 포춘 500대 다국적 기업들은 서벤스-옥슬리법 및 HIPAA 요건을 충족하면서 전 세계 사업 운영을 뒷받침하는 데이터 자산을 관리하기 위해 아웃소싱 파트너에 의존하고 있습니다. 그러나 해외 아웃소싱 관행에 대한 감시가 강화되고, 연방 정부가 국내 AI 연구를 장려함에 따라 일부 업무 부하는 문화적 친화성과 이중 언어 구사 인력을 모두 갖춘 캐나다 및 멕시코의 니어쇼어 센터로 이전되고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 2026-2031년 연평균 성장률(CAGR) 34.62%를 나타낼 것으로 예측됩니다. 인도의 디지털 정부 이니셔티브, 동남아시아의 스마트 시티 전개, 그리고 중국의 대규모 제조 분석 프로그램은 모두 데이터 분석 아웃소싱 시장의 확장을 위한 비옥한 토양이 되고 있습니다. 인도는 여전히 주요 서비스 제공 거점이지만, 베트남과 인도네시아의 신생 기업들도 AI 어노테이션, 엣지 컴퓨팅, 그리고 도메인별 모델 테스트에 중점을 둔 전문적인 분석 업무를 수주하고 있습니다. 인도의 국가 프로그램인 ‘디지털 인디아(Digital India)’가 주도하는 디지털 정부 이니셔티브는 공공 부문 및 민간 프로젝트 전반에 걸쳐 분석 아웃소싱 성장을 위한 비옥한 토대를 마련하고 있습니다.
유럽의 동향은 GDPR(EU 개인정보보호규정)의 시행과 데이터 출처 및 알고리즘의 투명성을 더욱 중시하는 AI 리스크 규제의 도입이 임박함에 따라 크게 좌우되고 있습니다. 고객들은 유럽 사이버 보안 인증 체계(ECCS) 기준을 준수하는 지역 내 데이터센터를 제공할 수 있는 공급업체를 점점 더 선호하고 있습니다. 폴란드와 포르투갈에 위치한 니어쇼어 거점은 EU 규정 준수를 충족하면서도 서유럽 주요 도시에 비해 비용 면에서 우위를 갖추고 있어 투자를 유치하고 있습니다. 남미, 중동 및 아프리카 3개 지역을 합치면 현재 지출에서 차지하는 비중은 그리 크지 않지만, 각국의 디지털 경제 계획과 데이터 기반 의사결정에 대한 민간 부문의 인식이 높아짐에 따라 수요가 가속화되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the data analytics outsourcing market size was valued at USD 10.89 billion in 2025 and estimated to grow from USD 14.54 billion in 2026 to reach USD 61.58 billion by 2031, at a CAGR of 33.47% during the forecast period (2026-2031).
This report is Segmented by Analytics Type (Descriptive, Diagnostic, and More), End-User Industry (Retail and E-Commerce, BFSI, and More), Service Model (Offshore, Nearshore, and On-shore/On-site), Organization Size (Large Enterprises and SMEs), Deployment Model (Cloud-Only and Hybrid Cloud), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Data Analytics Outsourcing Market Trends and Insights
Surging Enterprise Data Volumes and Complexity
Global organizations now generate petabytes of structured, semi-structured, and unstructured data from mobile apps, IoT devices, and omnichannel touchpoints, overwhelming in-house processing capacity. Limited internal skills in data engineering and machine learning further hamper timeliness. Outsourcing partners address these gaps with pre-built ingestion pipelines, scalable cloud infrastructure, and industry-specific data models that shorten time to insight while lowering total cost of ownership. Many clients adopt pay-as-you-go data-as-a-service contracts that unlock variable pricing advantages, enabling redeployment of scarce capital toward core innovation initiatives.
Need for Near-Real-Time Decision-Making in Omnichannel Commerce
Digital shoppers expect instant personalization and seamless inventory visibility whether they engage on web, mobile, or physical channels. This expectation drives demand for analytics engines capable of processing event streams, updating recommendation algorithms, and triggering interventions within milliseconds. Building such low-latency stacks in-house requires large capital outlays in stream-processing platforms, in-memory databases, and edge servers. Specialist outsourcing vendors offer turnkey real-time analytics platforms, complete with 24X7 operations support, that let retailers and consumer brands go live quickly while converting fixed investments into variable fees tied to usage.
Persistent Data-Residency and Cross-Border Transfer Regulations
GDPR enforcement and forthcoming AI-specific statutes tighten rules on where citizen data can be stored and processed. Multinationals reassess vendor portfolios to ensure compliance documentation, secure connectivity, and geo-fencing capabilities. Outsourcing agreements now include detailed sub-processor disclosures and audit clauses, adding legal complexity that can slow deal cycles and raise costs for providers that lack certified local facilities.
Other drivers and restraints analyzed in the detailed report include:
- Cost Pressure to Convert Capex Analytics Stacks into Variable Opex
- BFSI Shift to Outcome-Based Pricing for Fraud and Risk Analytics
- Talent Attrition and Wage Inflation in India-Centric Delivery Hubs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Prescriptive tools translated 39.48% of total revenue into predictive models during 2025, yet their share continues to rise because enterprises increasingly demand recommendations rather than retrospective dashboards. The data analytics outsourcing market size for prescriptive solutions is projected to advance at a 34.32% CAGR over 2026-2031. Outsourcing partners differentiate by integrating scenario optimization engines with conversational AI, delivering decision automation that bypasses the need for specialized coding talent.
Generative AI further democratizes prescriptive analytics by allowing domain specialists to articulate business constraints in natural language, which engines then translate into optimization logic. Vendors embed frameworks that manage model governance, version control, and regulatory explainability, positioning themselves as partners in strategic decision making instead of report builders. As client expectations shift toward continuous improvement, providers bundle iterative model tuning and A/B testing into outcome-based contracts, ensuring value realization throughout the engagement lifecycle.
BFSI retained 27.05% of data analytics outsourcing market share in 2025 owing to longstanding investment in credit-risk scoring, fraud detection, and regulatory reporting. Nonetheless, healthcare is climbing fastest with a 34.15% CAGR to 2031, propelled by telehealth adoption, electronic health record integration, and personalized medicine protocols. Providers offering HIPAA-compliant data lakes and pre-certified clinical analytics libraries enjoy a first-mover advantage.
Life-science firms increasingly outsource real-world evidence gathering and genomic sequencing analytics, creating high-margin opportunities for vendors with specialist domain expertise. Meanwhile, insurers partner with analytics firms to combine claims data and wearable sensor inputs, driving early-warning models that reduce hospitalization costs. As payers and providers converge around value-based care, demand rises for longitudinal patient-journey analytics that span clinical, behavioral, and social determinants of health data.
Complete Report Scope:
- By Analytics Type
- Descriptive Analytics
- Diagnostic Analytics
- Predictive Analytics
- Prescriptive Analytics
- By End-user Industry
- Retail and e-Commerce
- Banking, Financial Services and Insurance (BFSI)
- Healthcare and Life Sciences
- Manufacturing
- IT and Telecom
- Automotive and Transport
- Energy, Utilities and Oil-and-Gas
- Others (Media, Public Sector, etc.)
- By Service Model
- Offshore
- Nearshore
- On-shore
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Deployment Model
- Cloud-Only
- Hybrid Cloud
- By Geography
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South-East Asia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 38.35% of 2025 revenue, reflecting the region's deep enterprise technology budgets, mature regulatory frameworks, and early adoption of outcome-based vendor agreements. Fortune 500 multinationals rely on outsourced partners to manage data estates that underpin global operations while meeting Sarbanes-Oxley and HIPAA mandates. However, rising scrutiny of offshore labor practices and federal incentives for on-shore AI research push some workloads into Canadian and Mexican nearshore centers that offer both cultural proximity and bilingual talent.
Asia Pacific is the fastest-growing geography with a projected 34.62% CAGR between 2026 and 2031. Digital-government initiatives in India, smart-city rollouts in Southeast Asia, and large-scale manufacturing analytics programs in China all create fertile ground for data analytics outsourcing market expansion. Though India remains the primary delivery hub, emerging players in Vietnam and Indonesia secure specialized analytics work focused on AI annotation, edge computing, and domain-specific model testing. Digital-government initiatives in India, spearheaded by the national Digital India programme, are creating fertile ground for analytics-outsourcing growth across public-sector and commercial projects.
Europe's trajectory is heavily shaped by GDPR enforcement and impending AI-risk regulations that heighten emphasis on data provenance and algorithmic transparency. Clients increasingly favor providers that can supply in-region data centers certified to European Cybersecurity Certification Scheme standards. Nearshore centers in Poland and Portugal attract investment because they blend EU compliance with cost advantages compared to Western European capitals. South America and the Middle East and Africa together account for a modest slice of current spending but display accelerating demand tied to national digital-economy plans and growing private-sector awareness of data-driven decision making.
- Accenture plc
- Tata Consultancy Services Ltd.
- International Business Machines Corporation
- Cognizant Technology Solutions Corporation
- Wipro Limited
- Infosys Limited
- Genpact Limited
- Capgemini SE
- Deloitte Touche Tohmatsu Limited
- Ernst and Young Global Limited
- PricewaterhouseCoopers International Limited
- KPMG International Limited
- EXL Service Holdings, Inc.
- Mu Sigma Inc.
- Fractal Analytics Inc.
- LatentView Analytics Corporation
- Tiger Analytics, LLC
- ZS Associates, Inc.
- Opera Solutions, LLC
- LTI Mindtree Limited
- WNS (Holdings) Limited
- Happiest Minds Technologies Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging enterprise data volumes and complexity
- 4.2.2 Need for near-real-time decision-making in omnichannel commerce
- 4.2.3 Cost-pressure to convert capex analytics stacks into variable opex
- 4.2.4 BFSI shift to outcome-based pricing for fraud and risk analytics
- 4.2.5 Emerging Gen-AI copilots that compress insight-delivery cycles
- 4.2.6 Sovereign-cloud mandates triggering offshore/nearshore re-balancing
- 4.3 Market Restraints
- 4.3.1 Persistent data-residency and cross-border transfer regulations
- 4.3.2 Talent attrition and wage inflation in India-centric delivery hubs
- 4.3.3 Buyer concerns over LLM "model leakage" when outsourcing Gen-AI analytics
- 4.3.4 Vendor lock-in risk due to proprietary accelerators and templates
- 4.4 Impact of Macroeconomic Factors
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Intensity of Competitive Rivalry
- 4.7.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Analytics Type
- 5.1.1 Descriptive Analytics
- 5.1.2 Diagnostic Analytics
- 5.1.3 Predictive Analytics
- 5.1.4 Prescriptive Analytics
- 5.2 By End-user Industry
- 5.2.1 Retail and e-Commerce
- 5.2.2 Banking, Financial Services and Insurance (BFSI)
- 5.2.3 Healthcare and Life Sciences
- 5.2.4 Manufacturing
- 5.2.5 IT and Telecom
- 5.2.6 Automotive and Transport
- 5.2.7 Energy, Utilities and Oil-and-Gas
- 5.2.8 Others (Media, Public Sector, etc.)
- 5.3 By Service Model
- 5.3.1 Offshore
- 5.3.2 Nearshore
- 5.3.3 On-shore
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises (SMEs)
- 5.5 By Deployment Model
- 5.5.1 Cloud-Only
- 5.5.2 Hybrid Cloud
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South-East Asia
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 Tata Consultancy Services Ltd.
- 6.4.3 International Business Machines Corporation
- 6.4.4 Cognizant Technology Solutions Corporation
- 6.4.5 Wipro Limited
- 6.4.6 Infosys Limited
- 6.4.7 Genpact Limited
- 6.4.8 Capgemini SE
- 6.4.9 Deloitte Touche Tohmatsu Limited
- 6.4.10 Ernst and Young Global Limited
- 6.4.11 PricewaterhouseCoopers International Limited
- 6.4.12 KPMG International Limited
- 6.4.13 EXL Service Holdings, Inc.
- 6.4.14 Mu Sigma Inc.
- 6.4.15 Fractal Analytics Inc.
- 6.4.16 LatentView Analytics Corporation
- 6.4.17 Tiger Analytics, LLC
- 6.4.18 ZS Associates, Inc.
- 6.4.19 Opera Solutions, LLC
- 6.4.20 LTI Mindtree Limited
- 6.4.21 WNS (Holdings) Limited
- 6.4.22 Happiest Minds Technologies Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment