|
시장보고서
상품코드
2122300
서명 검증 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Signature Verification - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
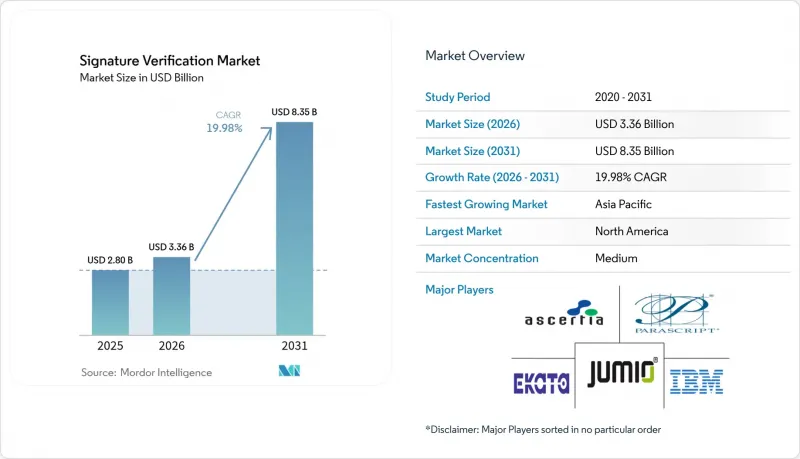
에 의하면, 서명 검증 시장 규모는 2025년 28억 달러로 평가되었고, 2026년에는 33억 6,000만 달러로 추정되고, 2026-2031년 CAGR 19.98%로 성장을 지속할 전망이며, 2031년에는 83억 5,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 솔루션 유형별(하드웨어, 소프트웨어), 도입 모델별(온프레미스, 클라우드/SaaS), 인증 모드별(독립형 서명, 멀티모달(서명+문서 이미지/신분증/생체 인증)), 최종 사용자 산업별(금융 서비스, 의료 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 서명 검증 시장 동향 및 인사이트
eIDAS 2.0 및 미국 CFR 제11편에 기반한 규정 준수 요건
브뤼셀과 워싱턴의 협력적인 움직임에 따라 기업들은 구식 전자 기록 시스템을 현대화해야만 하는 상황에 처해 있습니다. eIDAS 2.0에서는 2026년까지 모든 EU 시민이 상호 운용 가능한 디지털 ID 지갑을 보유해야 할 의무가 부과되었으며, 인증된 신뢰 서비스 제공업체가 뒷받침하는 적격 전자 서명에 대한 기준이 강화되었습니다. 동시에, 개정된 FDA 지침에서는 감사 추적 및 위험 기반 검증이 강조되고 있어, 제약 기업 스폰서들은 AI를 활용한 서명 검증 플랫폼으로의 전환을 서둘러야 하는 상황에 놓여 있습니다. 그 결과, 다국적 기업들은 두 가지 규제 요건을 모두 충족하는 통합된 검증 아키텍처를 모색하고 있으며, 전 세계적인 규정 준수가 가능한 클라우드 제공업체로의 집약이 가속화되고 있습니다.
2024년 이후 선거에 따른 우편 투표 서명 확인 업무의 급증
현재 미국 31개 주에서 부재자 투표 서명 검증이 의무화되어 있어, 높은 처리량을 갖춘 시스템에 대한 수요가 증가하고 있습니다. 노스캐롤라이나주에서 진행된 시범 사업에서는 자동화 플랫폼이 시간당 1,000표를 처리하여 수동 심사 시간을 95% 단축할 수 있음이 입증되었습니다. 이에 따라 캘리포니아주는 속도보다 감사 가능성을 우선시하여, 수동 방식의 안전 장치를 갖춘 기술 지원형 심사를 의무화했습니다. 다문화적 서명 차이나 노화에 따른 변화에 대응할 수 있는 공급업체는 선거 관리 기관이 정확성, 판정의 투명성, 그리고 규제상 감사 기능에 대해 대가를 지불하기 때문에 높은 가격을 책정할 수 있게 되었습니다.
캡처 장치 간의 편차와 레거시 시스템의 사일로화로 인한 통합 문제
많은 조직에서 서명 패드, 태블릿, 모바일 앱 등이 뒤죽박죽으로 사용되고 있으며, 각각 다른 해상도와 샘플링 속도로 데이터를 생성하고 있습니다. 알고리즘은 불균일한 필압 곡선이나 타이밍 데이터를 보정해야 하지만, 이로 인해 오거절률이 상승하고 총 소유 비용(TCO)이 증가합니다. 최신 검증 시스템과 기존 기록 시스템을 통합하는 것은 데이터가 사일로화되어 있어 종합적인 부정 분석이 방해받기 때문에 복잡성이 가중됩니다. 소규모 기관의 경우, 하드웨어 교체에 드는 비용이 기대되는 이점을 상회하기 때문에 업그레이드를 미루고 있으며, 보안상 큰 이점이 있음에도 불구하고 단기적인 도입이 억제되고 있습니다.
부문 분석
2025년 서명 검증 시장에서 소프트웨어가 57.30%를 차지했습니다. 이는 웹, 모바일, 지점 채널 전반에 걸쳐 실시간 부정 감지를 실현하는 클라우드 네이티브 AI 모델의 보급을 반영한 것입니다. 서명 패드와 같은 하드웨어 장치는 규제가 엄격한 환경에서는 여전히 자리 잡고 있지만, 원격 워크플로가 주류가 됨에 따라 그 점유율은 계속해서 감소할 것입니다. 소프트웨어 부문은 은행, 의료, 정부 포털 내에 검증 기능을 통합하는 SDK에 힘입어 2031년까지 연평균 성장률(CAGR) 22.85%를 나타낼 것으로 예측됩니다. 각 벤더는 정적 이미지 비교에 행동 분석을 더함으로써 수동 심사 비율을 줄이고 의사 결정 지연을 단축하고 있습니다. 엣지 배포가 가능한 모델은 통신 연결이 불안정한 장소에서도 대응할 수 있어, 물류나 현장 서비스와 같은 이용 사례에 대한 매력을 높이고 있습니다. 또한, 모델의 지속적인 재학습을 통해 벤더들은 고객 측의 코드 변경 없이도 새로운 공격 패턴에 대응할 수 있게 되어, 서명 검증 시장에서 소프트웨어의 구조적 우위가 두드러지고 있습니다.
하드웨어의 성장 속도는 둔화되고 있지만, 잉크 서명의 물리적 보관이 필수적인 틈새 분야에서는 여전히 그 중요성을 유지하고 있습니다. 법원, 공증인 및 일부 생명과학 연구소에서는 암호화된 타임스탬프를 부착하는 인증 장치를 사용한 대면 서명 획득이 여전히 요구되고 있습니다. 그러나 이러한 업계의 조달 주기는 여전히 길고, 자본 예산은 고정되어 있으며, 기존 시스템의 개조 비용도 고액입니다. 클라우드의 경제성이 의사 결정 기준을 운영 비용(OPEX)으로 전환시키는 가운데, 많은 구매자들은 현재 수명이 다한 장치를 단계적으로 폐기하고, 모바일 기반 수집 및 백엔드 AI 검증으로의 전환을 추진하고 있습니다. 이러한 전환은 소프트웨어 중심의 비즈니스 모델 부상을 뒷받침하며, 공급업체들이 하드웨어의 일회성 판매가 아닌 구독 기반의 수익원에 집중하는 추세를 공고히 하고 있습니다.
2025년 시점에서는 엄격한 규제를 받는 은행, 보험사, 생명과학 기업들이 감사 및 지연 측면에서 온프레미스 관리를 선호했기 때문에 서명 검증 시장 규모의 53.90%를 온프레미스 도입이 차지했습니다. 그러나 클라우드/SaaS 도입은 2031년까지 연평균 27.05%의 복합 성장률로 확대될 것으로 예측되며, 규모의 경제와 범용 API의 보급으로 인해 도입 기반의 격차는 점차 줄어들 것으로 보입니다. 클라우드 플랫폼은 모델 훈련을 중앙 집중화된 환경에 집중시키고 다양한 데이터 세트를 활용함으로써 딥페이크 위협에 대한 정확도를 높이고 있습니다. 탄력적인 컴퓨팅 프로비저닝을 통해 유휴 인프라에 대한 지출을 절감할 수 있으며, 이는 투표 성수기에 집중적인 워크로드를 처리해야 하는 선거관리위원회에 중요한 이점이 됩니다.
지역별 클라우드 존은 통일된 정책 엔진을 유지하면서 GDPR(EU 개인정보보호규정) 및 eIDAS 2.0에 기반한 데이터 거주 요건을 충족합니다. 하이브리드 아키텍처(서명 아티팩트의 로컬 저장과 클라우드 기반 추론을 결합한 것)는 도입에 신중한 조직에게 규정 준수를 고려한 가교 역할을 합니다. 프로바이더는 가동률에 관한 SLA, 자동 패치 적용, 원활한 기능 배포를 통해 가치 제안을 강화하고 있으며, 이는 고립된 데이터센터에서는 비용 면에서 실현하기 어려운 사항입니다. 조직들이 운영상의 민첩성이 주권 관련 위험보다 더 중요하다고 판단함에 따라, 서명 검증 시장은 SaaS 구독으로의 전환이 가속화될 전망입니다.
지역별 분석
북미는 성숙한 규제 체계와 벤처 자본에 힘입은 혁신 생태계의 지원에 힘입어 2025년 매출의 33.40%를 차지했습니다. 각 주에서는 2024년 선거 주기 이후 선거의 공정성을 높이기 위해 투표용지 서명 자동 검증 시스템을 도입하여 선거관리위원회의 신속한 시스템 업데이트를 촉진했습니다. 금융 기관 또한 교묘해지고 대규모화된 수표 사기 수법을 차단하기 위해 도입을 가속화하고 있으며, AI 분석을 활용하여 예금 시 미묘한 서명 차이를 감지하고 있습니다. 특허권 집행은 여전히 양날의 검입니다. USAA의 지속적인 라이선싱 소송 승리는 수익을 창출하고 있지만, 원격 예금 모듈을 통합하는 은행의 경우 규정 준수 비용 증가로 이어지고 있습니다. 또한, 이 지역에서는 FDA 파트 11에 따른 감사 대응에 대한 관심이 높아짐에 따라, 서명의 출처와 보관 이력(체인 오브 커스터디)을 기록하는 전문 플랫폼에 대한 수요가 더욱 증가하고 있습니다.
아시아태평양은 인도의 Aadhaar와 연동된 디지털 지갑 및 급성장하는 모바일 결제 생태계를 견인력으로 삼아, 2026-2031년 24.60%라는 지역 내 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 막대한 거래량과 간헐적으로 발생하는 부정 사건을 감안하여 인도 중앙은행은 KYC(고객 신원 확인) 기준을 강화하고 있으며, 이에 따라 각 은행은 신규 고객 등록 워크플로우에 다중 모드 서명 인증을 도입하도록 권장받고 있습니다. 일본과 한국에서는 손가락 정맥 인증 및 행동 생체 인식에 대한 연구가 진행되고 있으며, 대부분의 경우 이러한 기술을 서명 분석과 결합하여 신뢰성이 높은 기업용 로그인을 실현하고 있습니다. 현지 데이터 주권 관련 규제로 인해 지역 내에서 호스팅되는 추론 클러스터에 대한 수요가 증가하고 있으며, 하이퍼스케일 클라우드 제공업체들은 국내 가용성 영역을 통해 이를 제공함으로써, 서명 검증 시장이 엄격한 거주 규정을 충족하면서도 전 세계적인 위협 인텔리전스 피드를 활용할 수 있도록 하고 있습니다.
유럽 성장의 열쇠를 쥔 것은 eIDAS 2.0으로, 이는 적격 전자 서명을 공식적으로 규정하고 EU 전역에서 국경을 초월한 상호 운용성을 의무화하고 있습니다. 인증된 신뢰 서비스 제공업체는 서명 페이로드에 내장된 디지털 인증서 발급에 있어 매우 중요한 역할을 수행하고 있으며, 이로 인해 알고리즘 기반 검증에 대한 기술적 요구 사항이 높아지고 있습니다. 브렉시트로 인해 영국과 EU 간의 워크플로가 복잡해지면서, 벤더들은 원활한 사용자 경험을 제공하면서도 이중 규정 준수 체계를 유지할 수밖에 없게 되었습니다. GDPR(EU 개인정보보호규정)이 요구하는 ‘프라이버시 바이 디자인(Privacy by Design)’ 요건으로 인해, 제공업체는 연합 학습(federated learning) 기술을 채택하여 서명 데이터를 관할 구역 밖으로 반출하지 않고도 모델을 학습시켜야 하는 상황에 직면해 있습니다. 그 결과, 유럽의 구매자들은 알고리즘의 정확도와 입증 가능한 개인정보 보호 조치를 종합적으로 평가하며, 이 두 가지를 모두 제공할 수 있는 공급업체를 우선적으로 선택하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the signature verification market size is expected to grow from USD 2.8 billion in 2025 to USD 3.36 billion in 2026 and is forecast to reach USD 8.35 billion by 2031 at 19.98% CAGR over 2026-2031.
This report is Segmented by Solution Type (Hardware, Software), Deployment Model (On-Premises, Cloud / SaaS), Authentication Mode (Stand-Alone Signature, Multimodal (signature + Doc Image / ID / Liveness)), End-User Industry (Financial Services, Healthcare and More), Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Signature Verification Market Trends and Insights
Compliance mandates under eIDAS 2.0 & U.S. CFR Part 11
The harmonized push from Brussels and Washington is forcing enterprises to modernize outdated electronic-record systems. eIDAS 2.0 obliges all EU citizens to hold interoperable digital identity wallets by 2026, raising the bar for qualified electronic signatures backed by certified trust service providers. Simultaneously, updated FDA guidance stresses audit trails and risk-based validation, compelling pharmaceutical sponsors to shift toward AI-enabled signature verification platforms. Multinationals consequently seek unified verification architectures that satisfy both regimes, accelerating consolidation around cloud players capable of global policy compliance.
Surge in mail-in ballot signature checks post-2024 elections
Thirty-one U.S. states now require signature verification for absentee ballots, elevating demand for high-throughput systems. North Carolina's pilot demonstrated that automated platforms processed 1,000 ballots per hour, cutting manual review time by 95%. California subsequently mandated technology-assisted review with manual fail-safes, placing auditability above speed. Vendors able to accommodate multicultural signature variation and age-related changes command premium pricing as election agencies pay for accuracy, adjudication transparency, and regulatory audit features.
Variability across capture devices & legacy silo integration
Organizations often rely on a patchwork of signature pads, tablets, and mobile apps, each producing data at different resolutions and sampling rates. Algorithms must compensate for inconsistent pressure curves and timing data, which inflates false-reject rates and raises total cost of ownership. Integrating modern verification with legacy record systems adds complexity, as siloed data prevents holistic fraud analytics. Smaller institutions postpone upgrades because replacing hardware exceeds perceived benefits, restraining near-term adoption despite compelling security gains.
Other drivers and restraints analyzed in the detailed report include:
- Fin-crime losses driving AI-based check-fraud analytics
- Cloud-native APIs embedded in e-signature suites
- High FRR in multicultural voter rolls sparks litigation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software accounted for 57.30% of the 2025 signature verification market, reflecting widespread adoption of cloud-native AI models that deliver real-time fraud detection across web, mobile, and branch channels. Hardware devices such as signature pads remain entrenched in regulated environments, yet their share will continue to erode as remote workflows dominate. The software segment is forecast to post a 22.85% CAGR through 2031, propelled by SDKs that embed verification inside banking, healthcare, and government portals. Vendors are layering behavioral analytics atop static image comparison, thereby reducing manual review rates and shrinking decision latency. Edge-deployable models address locations with intermittent connectivity, broadening appeal to logistics and field-service use-cases. Continuous model retraining also enables vendors to counter emerging attack patterns without customer-side code changes, underscoring software's structural advantage within the signature verification market.
Hardware, though slower-growing, retains niche relevance where physical custody of wet-ink signatures is non-negotiable. Courts, notaries, and select life-sciences labs still require in-person capture using certified devices that append cryptographic timestamps. Yet procurement cycles in these verticals remain long, capital budgets fixed, and retrofit costs high. As cloud economics shift decision criteria toward operating expenditure, many buyers now phase out devices at end-of-life, migrating to mobile capture plus back-end AI validation. This transition reinforces the ascendancy of software-centric business models and cements provider focus on subscription revenue streams rather than one-time hardware sales.
On-premises deployments represented 53.90% of the signature verification market size in 2025 as heavily regulated banks, insurers, and life-sciences firms favored local control for audit and latency reasons. However, cloud/SaaS installations are projected to compound at 27.05% annually through 2031, narrowing the installed-base gap on economies of scale and universal API reach. Cloud platforms concentrate model training in centralized environments, leveraging diverse datasets that sharpen accuracy against deepfake threats. Elastic compute provisioning cuts idle infrastructure spending, a critical advantage for election boards that process workloads in intense bursts during peak voting periods.
Regional cloud zones support data-residency mandates under GDPR and eIDAS 2.0 while maintaining uniform policy engines. Hybrid architectures-local storage of signature artefacts combined with cloud-based inference-offer a compliance-friendly bridge for cautious adopters. Providers bolster value propositions with uptime SLAs, automated patching, and seamless feature rollouts that would be cost-prohibitive in isolated data centers. As organizations conclude that operational agility outweighs perceived sovereignty risks, the signature verification market is poised for an accelerated shift toward SaaS subscriptions.
Complete Report Scope:
- By Solution Type
- Hardware
- Signature pads and sensors
- Biometric terminals / kiosks
- Software
- Static (offline) verification
- Dynamic (online) verification
- SDK / API platforms
- Hardware
- By Deployment Model
- On-premise
- Cloud / SaaS
- By Authentication Mode
- Stand-alone signature
- Multimodal (signature + doc image / ID / liveness)
- By End-user Industry
- Financial Services
- Government and Elections
- Healthcare
- Transport and Logistics
- Legal and Real-estate
- Other Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 33.40% of 2025 revenue, supported by mature regulatory regimes and venture-backed innovation ecosystems. States introduced automated ballot-signature systems to enhance electoral integrity after the 2024 cycle, driving rapid upgrades among election boards. Financial institutions also escalated adoption to blunt check-fraud schemes that escalated in sophistication and scale, leveraging AI analytics to detect subtle signature deviations at deposit time. Patent enforcement remains a double-edged sword: USAA's ongoing licensing victories generate revenue but elevate compliance costs for banks integrating remote-deposit modules. The region's focus on audit readiness under FDA Part 11 further solidifies demand for specialized platforms that document signature provenance and chain-of-custody.
Asia Pacific is forecast to deliver the highest regional CAGR of 24.60% between 2026 and 2031, anchored by India's Aadhaar-linked wallets and surging mobile-payment ecosystems. Massive transaction volumes and episodic fraud incidents encourage the Reserve Bank of India to tighten KYC norms, prompting banks to embed multimodal signature verification in onboarding workflows. Japan and South Korea advance finger-vein and behavioural-biometric research, often pairing those technologies with signature analysis for high-trust enterprise login. Local data-sovereignty mandates spur demand for regionally hosted inference clusters, which cloud hyperscale's provide through in-country availability zones, ensuring that the signature verification market meets stringent residency rules while still leveraging global threat-intelligence feeds.
Europe's growth narrative revolves around eIDAS 2.0, which formalizes qualified electronic signatures and compels cross-border interoperability throughout the bloc. Certified trust service providers play a pivotal role in issuing digital certificates embedded within signature payloads, raising technical requirements for algorithmic verification. Brexit complicates UK-EU workflows, forcing vendors to maintain dual compliance stacks while promising seamless user experiences. GDPR expectations of privacy-by-design push providers to adopt federated-learning techniques, training models without exporting signature artefacts beyond jurisdictional boundaries. As a result, European buyers weigh algorithmic precision alongside demonstrable privacy safeguards, favouring vendors that deliver both.
- Mitek Systems Inc.
- Parascript LLC
- IBM Corp.
- Adobe Inc.
- DocuSign Inc.
- Ascertia Ltd
- Jumio Corp.
- Ekata Inc.
- Acuant Inc.
- SutiSoft Inc.
- CERTIFY Global Inc.
- Scriptel Corp.
- iSign Solutions Inc.
- Veriff
- Hitachi Ltd. (Biometric systems)
- HID Global (Assa Abloy)
- Signicat AS
- Topaz Systems Inc.
- Aratek Biometrics
- Biometric Signature ID
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Compliance mandates under eIDAS 2.0 and U.S. CFR Part 11
- 4.2.2 Surge in mail in ballot signature checks post-2024 elections
- 4.2.3 Fin-crime losses driving AI-based check-fraud analytics
- 4.2.4 Cloud-native APIs embedded in e-signature suites
- 4.2.5 GenAI forged-signature detection algorithms
- 4.2.6 Indias Aadhaar linked digital signature wallets (UPI 3.0)
- 4.3 Market Restraints
- 4.3.1 Variability across capture devices and legacy silo integration
- 4.3.2 High FRR in multicultural voter rolls sparks litigation
- 4.3.3 Data-sovereignty limits on cross-border model training
- 4.3.4 Patent litigation risk (e.g., MITK vs USAA)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (AI, edge, GenAI)
- 4.7 Porters Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution Type
- 5.1.1 Hardware
- 5.1.1.1 Signature pads and sensors
- 5.1.1.2 Biometric terminals / kiosks
- 5.1.2 Software
- 5.1.2.1 Static (offline) verification
- 5.1.2.2 Dynamic (online) verification
- 5.1.2.3 SDK / API platforms
- 5.1.1 Hardware
- 5.2 By Deployment Model
- 5.2.1 On-premise
- 5.2.2 Cloud / SaaS
- 5.3 By Authentication Mode
- 5.3.1 Stand-alone signature
- 5.3.2 Multimodal (signature + doc image / ID / liveness)
- 5.4 By End-user Industry
- 5.4.1 Financial Services
- 5.4.2 Government and Elections
- 5.4.3 Healthcare
- 5.4.4 Transport and Logistics
- 5.4.5 Legal and Real-estate
- 5.4.6 Other Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 Middle East
- 5.5.4.1 Israel
- 5.5.4.2 Saudi Arabia
- 5.5.4.3 United Arab Emirates
- 5.5.4.4 Turkey
- 5.5.4.5 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Egypt
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Recent Devs.)
- 6.4.1 Mitek Systems Inc.
- 6.4.2 Parascript LLC
- 6.4.3 IBM Corp.
- 6.4.4 Adobe Inc.
- 6.4.5 DocuSign Inc.
- 6.4.6 Ascertia Ltd
- 6.4.7 Jumio Corp.
- 6.4.8 Ekata Inc.
- 6.4.9 Acuant Inc.
- 6.4.10 SutiSoft Inc.
- 6.4.11 CERTIFY Global Inc.
- 6.4.12 Scriptel Corp.
- 6.4.13 iSign Solutions Inc.
- 6.4.14 Veriff
- 6.4.15 Hitachi Ltd. (Biometric systems)
- 6.4.16 HID Global (Assa Abloy)
- 6.4.17 Signicat AS
- 6.4.18 Topaz Systems Inc.
- 6.4.19 Aratek Biometrics
- 6.4.20 Biometric Signature ID
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment