

|
시장보고서
상품코드
2122333
매니지드 IT 인프라 서비스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Managed IT Infrastructure Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
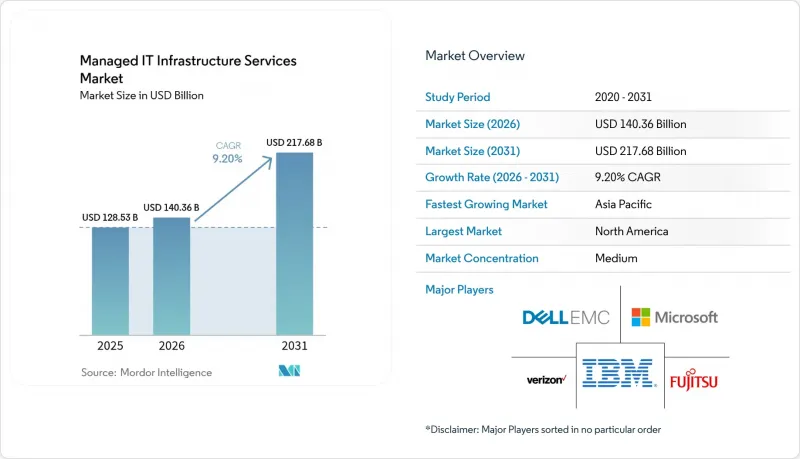
에 의하면, 매니지드 IT 인프라 서비스 시장 규모는 2025년에 1,285억 3,000만 달러로 평가되었고, 2026년 1,403억 6,000만 달러에서 2031년까지 2,176억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 9.20%를 나타낼 전망입니다.
본 보고서는 서비스 카테고리별(가상화, 네트워크, 스토리지, 서버 등), 기업 규모별(중소기업, 대기업), 도입 모델별(온프레미스, 클라우드, 하이브리드), 최종 사용자 산업별(IT 및 통신, BFSI 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 매니지드 IT 인프라 서비스 시장 동향 및 인사이트
아웃소싱을 통한 비용 최적화
기업들은 인건비 차익 거래에 기반한 계약을, 절감된 비용을 혁신 프로그램에 재투자하는 성과 기반 파트너십으로 대체하고 있습니다. 매니지드 서비스 벤더는 예측 가능한 운영 비용을 제공함으로써 CIO가 예산을 AI 시범 프로젝트나 제품 디지털화에 할당할 수 있도록 지원합니다. CFO의 거버넌스에서는 현재 청구서 내역 항목이 아닌 가동률, 복원력 및 경험 점수를 바탕으로 파트너를 평가했습니다. 이러한 동향은 매니지드 IT 인프라 서비스 시장이 단순한 비용 절감을 위한 상품이 아니라 가치 창출의 수단임을 재확인시켜 줍니다.
클라우드 및 하이브리드 퍼스트의 변혁 물결
클라우드 전환은 멀티 클라우드 환경 전반에 걸친 워크로드 배치 최적화로 성숙해졌습니다. 기업들은 지연 시간, 데이터 주권, TCO(총 소유 비용) 목표를 달성하기 위해 하이퍼스케일러, 코로케이션, 엣지 환경을 조합하고 있습니다. 24개의 추가 리전으로 제공 범위가 확대된 ‘Oracle Database&Azure’ 프로그램은 공동 서비스 카탈로그가 락인을 완화하고 정책 준수를 실현하는 방법을 여실히 보여주고 있습니다. 이러한 상호 연계된 인프라를 설계하고 운영할 수 있는 제공업체는 더 대규모의 장기 계약을 확보하며, 매니지드 IT 인프라 서비스 시장을 주도하고 있습니다.
보안 및 개인정보 보호에 대한 우려
금융 서비스 및 의료 분야의 이사회는 위협 노출 및 규정 준수 체계의 관점에서 관리형 계약을 면밀히 검토하고 있습니다. HIPAA에서는 워크로드가 병원 부지 밖으로 나가기 전에 견고한 비즈니스 제휴 계약, 다층 암호화 및 감사 추적이 요구됩니다. 실사 기간이 길어지면 판매 주기가 연장되고 수익 창출이 지연될 수 있어, 매니지드 IT 인프라 서비스 시장의 단기 성장을 저해하는 요인이 됩니다.
부문 분석
2025년에는 매니지드 네트워크 서비스가 총 수익의 33.72%를 차지했으며, 연결성 최적화가 전반적인 수요의 가장 큰 요인이 되었습니다. 기업들은 하이브리드 근무 및 지연에 민감한 SaaS를 지원하기 위해 SD-WAN 및 제로 트러스트 아키텍처의 현대화를 지속하고 있습니다. 연평균 성장률(CAGR) 11.33%로 병행 성장하고 있는 엣지 오케스트레이션은 공장 전반에 걸친 센서 밀도 증가와 실시간 분석의 확대를 반영하고 있습니다. 매니지드 IT 인프라 서비스 시장에서는 캠퍼스, 지사, 클라우드, 엣지의 모니터링을 단일 가시성 스택으로 통합하는 벤더가 높은 평가를 받고 있습니다.
네트워크 현대화는 부가가치가 높은 교차 판매의 기반이 되고 있습니다. 회선이나 라우터가 MSP(관리형 서비스 제공업체)에 의한 원격 관리 대상이 되면, SASE 게이트웨이, 서비스형 방화벽(Firewall-as-a-Service), AI 기반 트래픽 최적화와 같은 관련 서비스가 뒤따릅니다. 레거시 하드웨어의 합리화가 진행되는 가운데, 가상화, 스토리지, 서버 관리에 대한 수요는 견조한 추세를 보이고 있지만, 상품화로 인해 이익률은 하락 추세를 보이고 있습니다. 대조적으로, 멀티 클라우드 FinOps, 보안 태세 관리, AI 워크로드 튜닝을 배경으로 클라우드 인프라 관리는 확대되고 있습니다. 매니지드 IT 인프라 서비스 시장이 성숙해짐에 따라, 이러한 계층을 통합된 청사진으로 패키지화하는 제공업체는 시장 점유율을 대폭 확대하게 될 것입니다.
대기업은 2025년 매출의 60.55%를 차지했으며, 이는 연중무휴 24시간 모니터링이 필요한 복잡한 멀티 리전 환경을 반영한 것입니다. 반면, 중소기업은 데이터센터 구축이 필요 없는 구독형 가격 책정의 혜택을 받아 2031년까지 연평균 성장률(CAGR) 9.28%로 성장을 지속하고 있습니다. 클라우드 마켓플레이스와 셀프 서비스 포털을 통해 직원 500명 규모의 소매 기업도 관리형 방화벽, 백업, 가시성을 몇 시간 이내에 구축할 수 있게 되었습니다.
그 결과 발생하는 이용의 민주화가 매니지드 IT 인프라 서비스 시장에서 신규 고객 확보의 성장을 뒷받침하고 있습니다. MSP에게 중소기업(SME) 확보는 업무 효율 향상으로 이어지지만, ARPU(고객 1인당 평균 수익)는 세계 기업 대상보다 낮은 수준을 유지하고 있습니다. 따라서 규모의 경제는 SLA 준수를 유지하면서 수동 티켓 처리를 최소화하는 자동화 및 AI 챗봇에 달려 있습니다. 소비 모델이 진화하는 가운데, 유연한 계약 기간과 모듈식 번들 플랜은 중소기업과의 계약 확보에 있어 계속해서 결정적인 요소가 될 것입니다.
지역별 분석
북미는 2025년에 34.12%의 매출 점유율을 유지했습니다. 이는 워크로드 아웃소싱 분야의 선도 기업으로서 성숙한 수준과, 성과 기반 계약을 뒷받침하는 엄격한 SLA를 반영한 결과입니다. 미국의 다국적 기업들은 클라우드 전환, AI 공동 개발, 제로 트러스트 구현을 포괄하는 다년 계약을 갱신하고 있습니다. 캐나다 기업들은 데이터 상주성을 확보하기 위해 하이브리드 플랫폼을 우선시하고 있으며, 멕시코의 제조업체들은 Automotive-4.0 생산 라인에 맞춘 관리형 캠퍼스 네트워크를 도입하고 있습니다. 이 지역에서는 벤더 간 경쟁이 치열하여 중규모 MSP 및 통신 사업자 산하 기업들 간의 통합이 진행되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 10.12%를 나타낼 것으로 예측되며, 이는 매니지드 IT 인프라 서비스 시장에서 지역별 가장 빠른 성장 속도입니다. 중국에서는 정부 주도의 디지털화로 인해 스마트 팩토리 플랫폼에 대한 관리형 서비스 지출이 집중되고 있습니다. 일본 기업들은 제품 혁신 주기를 가속화하기 위해 프라이빗 클라우드 기반의 AI 클러스터를 시범적으로 도입하고 있는 반면, 인도의 국내 스타트업 기업들은 클라우드에서 직접 종량제 방식의 매니지드 쿠버네티스 클러스터를 채택하고 있습니다. 호주, 한국 및 아세안 5개국에서는 기업들이 레거시 데이터센터를 건너뛰고 SaaS 및 관리형 엣지 노드로 직접 전환함에 따라 비약적인 확산이 나타나고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the managed IT infrastructure services market size was valued at USD 128.53 billion in 2025 and estimated to grow from USD 140.36 billion in 2026 to reach USD 217.68 billion by 2031, at a CAGR of 9.20% during the forecast period (2026-2031).
This report is Segmented by Service Category (Virtualization, Networking, Storage, Servers, and More), Enterprise Size (Small and Medium Enterprises, Large Enterprises), Deployment Model (On-Premises, Cloud, Hybrid), End-User Industry (IT and Telecommunication, BFSI, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Managed IT Infrastructure Services Market Trends and Insights
Cost Optimisation Through Outsourcing
Enterprises are replacing labour-arbitrage contracts with outcome-based partnerships that funnel savings into innovation programs. Managed vendors provide predictable operating expenses, freeing CIO budgets for AI pilots and product digitization. CFO stewardship now benchmarks partners on uptime, resiliency, and experience scores rather than invoice line items. These dynamics reaffirm the managed IT infrastructure services market as a lever for value creation rather than a cost-cutting commodity.
Cloud and Hybrid-First Transformation Wave
Cloud migration has matured into workload placement optimisation across multicloud estates. Enterprises mix hyperscaler, colocation, and edge footprints to satisfy latency, sovereignty, and TCO goals. The expanded Oracle Database@Azure program-now in 24 additional regions-underscores how joint service catalogs mitigate lock-in and achieve policy compliance. Providers able to engineer and operate these interwoven fabrics win larger, longer contracts that elevate the managed IT infrastructure services market.
Security and Privacy Concerns
Financial services and healthcare boards scrutinise managed deals for threat exposure and compliance posture. HIPAA requires robust Business Associate Agreements, layered encryption, and audit trails before workloads leave hospital campuses. Extended due diligence lengthens sales cycles and can delay revenue realisation, tempering near-term growth for the managed IT infrastructure services market.
Other drivers and restraints analyzed in the detailed report include:
- IT-Skills Shortage in Advanced Infrastructure Ops
- AI-Driven Hyper-Automation Lowers MTTR
- Vendor Lock-in and Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, managed network services accounted for 33.72% of total revenue, making connectivity optimisation the biggest contributor to overall demand. Enterprises continue to modernise SD-WAN and zero-trust architectures to support hybrid work and latency-sensitive SaaS. Parallel growth in edge orchestration at an 11.33% CAGR mirrors rising sensor density and real-time analytics across factories. The managed IT infrastructure services market rewards vendors that merge campus, branch, cloud, and edge monitoring into single observability stacks.
Network modernisation also anchors higher-value cross-selling. Once circuits and routers fall under an MSP's remote management, adjacent services such as SASE gateways, firewall-as-a-service, and AI-based traffic optimisation follow. Virtualisation, storage, and server management maintain steady demand as legacy hardware is rationalised, but margins trend lower due to commoditisation. By contrast, cloud infrastructure management is ascending on the back of multicloud finops, security posture management, and AI workload tuning. Providers that package these layers in integrated blueprints will capture outsized wallet share as the managed IT infrastructure services market matures.
Large enterprises delivered 60.55% of 2025 billings, reflecting complex multiregional estates needing 24X7 oversight. However, SMEs now post a 9.28% CAGR to 2031, benefitting from subscription pricing that obviates data-center buildouts. Cloud marketplaces and self-service portals let a 500-employee retailer spin up managed firewalls, backups, and observability within hours.
The resulting democratization fuels net-new logo growth inside the managed IT infrastructure services market. For MSPs, SME onboarding drives volume efficiency, though ARPU remains lower than with global accounts. Economies of scale thus hinge on automation and AI chatbots that minimise manual ticket handling while preserving SLA adherence. As consumption models evolve, flexible term lengths and modular bundles will remain decisive in winning SME contracts.
Complete Report Scope:
- By Service Category
- Virtualization
- Networking
- Storage
- Servers
- Cloud Infrastructure Management
- Edge Infrastructure Management
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By Deployment Model
- On-premises
- Cloud
- Hybrid
- By End-User Industry
- IT and Telecommunication
- BFSI
- Manufacturing
- Retail and E-commerce
- Transportation and Logistics
- Healthcare
- Energy and Utilities
- Geographic Analysis
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America sustained 34.12% revenue share in 2025, reflecting early-mover maturity in workload outsourcing and stringent SLAs that favour outcome-based contracts. United States multinationals execute multi-year renewals covering cloud migration, AI co-development, and zero-trust enablement. Canadian firms prioritise hybrid platforms to ensure data residency, and Mexican manufacturers deploy managed campus networks aligned with Automotive-4.0 production lines. Vendor competition here is intense, driving consolidation among midsized MSPs and telecom-carrier captives.
Asia Pacific is projected to grow at 10.12% CAGR through 2031, the fastest regional pace inside the managed IT infrastructure services market. China's state-incentivised digitisation funnels managed spend into smart-factory platforms. Japan's enterprises experiment with private-cloud AI clusters to accelerate product innovation cycles, while India's domestic startups adopt consumption-based managed Kubernetes clusters straight from the cloud. Australia, South Korea, and ASEAN-5 economies witness leapfrog uptake as businesses bypass legacy data centers and go straight to SaaS and managed edge nodes.
- Accenture plc
- Amazon Web Services, Inc.
- ATandT Inc.
- Capgemini SE
- Cisco Systems, Inc.
- Cognizant Technology Solutions Corp.
- Dell Technologies Inc.
- DXC Technology Company
- Fujitsu Limited
- Google LLC
- HCL Technologies Ltd.
- Hewlett Packard Enterprise Co.
- IBM Corporation
- Kyndryl Holdings, Inc.
- Microsoft Corporation
- NTT DATA Corporation
- Rackspace Technology, Inc.
- Tata Consultancy Services Ltd.
- Verizon Communications Inc.
- Wipro Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cost optimisation through outsourcing
- 4.2.2 Cloud and hybrid-first transformation wave
- 4.2.3 IT-skills shortage in advanced infrastructure ops
- 4.2.4 AI-driven hyper-automation lowers MTTR (under-radar)
- 4.2.5 Edge infrastructure surge in Industry 4.0 (under-radar)
- 4.2.6 Green-datacentre mandates and ESG scorecards (under-radar)
- 4.3 Market Restraints
- 4.3.1 Security and privacy concerns
- 4.3.2 Vendor lock-in and integration complexity
- 4.3.3 Escalating power-/cooling OPEX for MSPs (under-radar)
- 4.3.4 Data-sovereignty/geopolitical fragmentation (under-radar)
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Category
- 5.1.1 Virtualization
- 5.1.2 Networking
- 5.1.3 Storage
- 5.1.4 Servers
- 5.1.5 Cloud Infrastructure Management
- 5.1.6 Edge Infrastructure Management
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Deployment Model
- 5.3.1 On-premises
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By End-User Industry
- 5.4.1 IT and Telecommunication
- 5.4.2 BFSI
- 5.4.3 Manufacturing
- 5.4.4 Retail and E-commerce
- 5.4.5 Transportation and Logistics
- 5.4.6 Healthcare
- 5.4.7 Energy and Utilities
- 5.5 Geographic Analysis
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Kenya
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 Amazon Web Services, Inc.
- 6.4.3 ATandT Inc.
- 6.4.4 Capgemini SE
- 6.4.5 Cisco Systems, Inc.
- 6.4.6 Cognizant Technology Solutions Corp.
- 6.4.7 Dell Technologies Inc.
- 6.4.8 DXC Technology Company
- 6.4.9 Fujitsu Limited
- 6.4.10 Google LLC
- 6.4.11 HCL Technologies Ltd.
- 6.4.12 Hewlett Packard Enterprise Co.
- 6.4.13 IBM Corporation
- 6.4.14 Kyndryl Holdings, Inc.
- 6.4.15 Microsoft Corporation
- 6.4.16 NTT DATA Corporation
- 6.4.17 Rackspace Technology, Inc.
- 6.4.18 Tata Consultancy Services Ltd.
- 6.4.19 Verizon Communications Inc.
- 6.4.20 Wipro Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


