|
시장보고서
상품코드
2122364
UV 경화형 인쇄 잉크 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)UV Cured Printing Inks - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
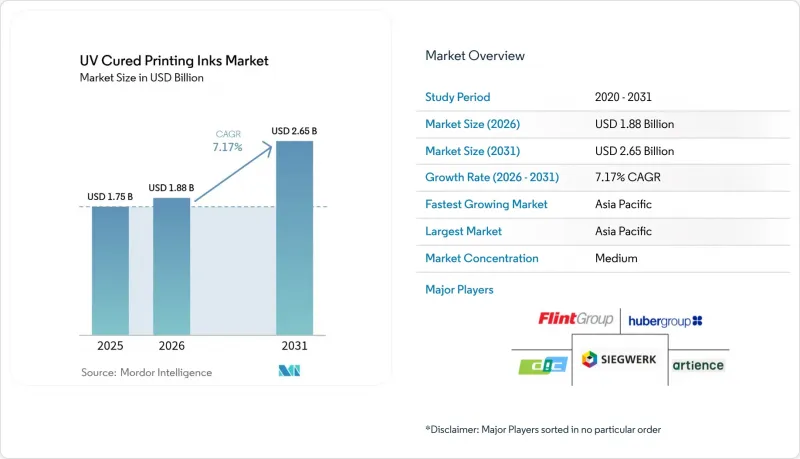
에 의하면, UV 경화형 인쇄 잉크 시장 규모는 2025년에 17억 5,000만 달러로 평가되었고, 2026년 18억 8,000만 달러에서 2031년까지 26억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.17%를 기록할 전망입니다.
본 보고서는 경화 공정별(아크 경화, LED 경화), 잉크 유형별(UV 플렉소 잉크, UV 오프셋 잉크, UV 저에너지/LED 오프셋 잉크, 기타), 용도별(포장, 상업·출판, 기타),지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 UV 경화형 인쇄 잉크 시장 동향 및 인사이트
디지털 인쇄 및 잉크젯 인쇄 수요 증가
온디맨드 인쇄의 도입으로 출판사는 창고 보관 비용을 대폭 절감하고 신속한 납기에 대한 기대에 부응할 수 있게 되었으며, UV 경화 잉크는 코팅지와 비코팅지 기판 위에서 인쇄 후 건조 대기 시간 없이 선명한 이미지를 구현합니다. 브랜드들이 디지털 캠페인에 촉각적 요소를 도입함에 따라 직접 메일 처리량이 회복되고 있으며, 우편물 취급에도 견딜 수 있는 내구성이 뛰어나고 마모에 강한 UV 인쇄물에 대한 수요가 증가하고 있습니다. 연구 개발의 모멘텀은 색상 간 번짐을 줄이고 광택의 균일성을 높이는 계면활성제 개질 잉크젯 배합에 관한 후지필름의 특허에서도 드러나며, 이러한 진보를 통해 고속 피에조 헤드와 UV 호환성이 강화되었습니다. 웹 투 프린트(Web-to-Print) 스토어프런트를 도입한 상업 인쇄 회사에서는 즉시 경화로 인해 작업 대기 시간이 단축되므로 소량 맞춤형 인쇄 프로젝트를 수주하고 있습니다. 기존 출판물의 발행 부수는 계속 줄어들고 있지만, 가변 데이터 및 특수 소재로의 가치 전환이 UV 경화형 인쇄 잉크 시장의 성장에 긍정적인 견인력을 제공합니다.
포장 및 라벨 가공 업체의 확대
인도네시아, 인도, 베트남에서는 지역 FMCG(일용소비재) 수요 증가와 세계 브랜드공급망 니어쇼어링에 따라 컨버터의 생산 능력이 증가하고 있습니다. 새로운 인쇄 라인에는 일반적으로 LED UV 또는 하이브리드 경화 방식이 채택되어, 설비 가동 시 발생하는 낭비를 줄이는 동시에 공장의 ESG 기준을 충족하고 있습니다. 미라크론(Miracron)사의 FLEXCEL NX 플랫폼으로 대표되는 플렉소 인쇄기의 업그레이드를 통해 컨버터는 그라비아 인쇄와 같은 미관을 실현하면서도, UV 잉크 배합에 적합한 더 얇은 판과 적은 잉크 도포량을 사용할 수 있게 되었습니다. 브랜드 소유자의 지속가능성 평가 기준에서 UV LED 경화에 따른 에너지 절약 효과가 점점 더 높이 평가되면서, 각 컨버터 기업들은 기술 혁신을 서두르고 있습니다. 식품 접촉 규제에 대한 대응과 총 소유 비용(TCO) 절감이라는 두 가지 요구 사항이 포장 산업에서 UV 경화형 인쇄 잉크 시장에 대한 수요를 확고히 하고 있습니다.
기존 상업 인쇄의 쇠퇴
광고주들이 예산을 디지털 플랫폼으로 전환함에 따라 신문과 잡지의 발행 부수는 계속 감소하고 있으며, 이는 기존 UV 오프셋 잉크 수요를 잠식하고 있습니다. 포장, 라벨,또는 부가가치가 높은 장식 인쇄로의 전환에 실패한 상업 인쇄업자들은 인쇄기 가동률 저하를 겪고 있으며, 이는 잉크 소비량의 직접적인 감소로 이어지고 있습니다. 높은 이익률을 자랑하는 단기 납기·소량 인쇄가 수익 감소를 완화하고는 있지만, 인쇄량 감소는 계속되고 있으며, 이러한 억제요인은 구조적인 역풍이 되고 있습니다.
부문 분석
LED 시스템은 2025년 UV 경화형 인쇄 잉크 시장 규모의 56.14%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 9.13%를 나타낼 것으로 예측됩니다. 이는 에너지 효율을 중시하는 컨버터들 사이에서 이 기술이 널리 수용되고 있음을 보여줍니다. 개조 설치 옵션을 통해 설비 투자의 장벽이 낮아져, 사업자는 기존 인쇄기 플랫폼을 유지하면서 가동 중단 시간을 대폭 줄일 수 있습니다. 스택 온도가 낮아짐에 따라 박막의 뒤틀림이 해소되고 더 높은 닙 압력이 가능해지기 때문에 1만 8,000sph를 초과하는 인쇄 속도에서도 정렬 정확도를 유지할 수 있습니다. 이러한 특징들이 결합되어 UV 경화형 인쇄 잉크 시장에서 LED의 주도적 위치를 뒷받침하고 있습니다.
아크 램프를 이용한 경화는 양이온성 광화학 반응을 유도하기 위해 광대역 스펙트럼이 필요한 특정 와이드 웹 및 스크린 인쇄 용도에서 여전히 일정한 위치를 차지하고 있습니다. 그러나 25W/cm2에 달하는 최근의 고출력 LED 다이오드로 인해 경화 깊이의 기존 방식과의 차이가 줄어들고 있으며, 하이브리드 램프 하우징을 통해 사용자는 작업 도중 모드를 전환할 수 있게 되어 전환 속도가 가속화되고 있습니다. 수은에 대한 정부 규제가 강화됨에 따라 아크 램프의 경제성은 더욱 떨어질 것이며, 이는 LED의 우위를 더욱 공고히할 것으로 보입니다.
지역별 분석
아시아태평양은 2025년 매출의 48.05%를 차지할 것으로 보이며, 2031년까지 연평균 성장률(CAGR) 9.08%를 나타낼 것으로 전망됩니다. 이는 중국의 전국적인 GB 4806.14-2023 준수 기한과 식품 포장용 잉크 내 톨루엔을 규제하는 인도의 IS 15495 시행이 주도하고 있습니다. UFlex와 같은 현지 주요 기업들은 금속화 필름에 접착되는 폴리에스테르 아크릴레이트를 도입하고 있으며, 이를 통해 컨버터는 단일 공정으로 배리어성과 이송성이라는 두 가지 목표를 모두 달성할 수 있게 되었습니다. 에너지 절약 설비 비용의 최대 30%를 환급해 주는 정부의 인센티브 덕분에 신규 그라비아 및 플렉소 인쇄 공장에서 LED UV 도입이 더욱 가속화되어, UV 경화형 인쇄 잉크 시장에서 이 지역의 주도력이 확고해지고 있습니다.
북미는 기술력이 풍부한 기반을 갖추고 있으며, 조기 도입 기업들은 이미 2016년에 LED 장비를 채택했습니다. 미국 환경보호청(EPA)의 권고와 ‘인플레이션 감축법’의 청정 제조 크레딧 덕분에 2024-2025년에 걸쳐 수많은 설비 갱신이 자금 지원을 받았습니다. 루브리졸(Lubrizol)사가 오하이오주에서 ‘솔스퍼스(Solspars)’ 초분산제의 생산량을 두 배로 늘린 사례에서 볼 수 있듯이, 수지와 첨가제의 생산 능력 확대는 국내 잉크 제조업체에 대한 공급 안정성을 높이고 있습니다.
중동 및 아프리카와 남미는 현재로서는 수량 점유율이 소폭에 그치고 있지만, 수출처 고객의 감사 기준을 준수하기 위해 포장 가공업체들이 용제 기반 라인에서 LED 플랫폼으로 전환하고 있어 잠재적인 성장 여지를 내포하고 있습니다. 하이브리드 UV-EB 플렉소 라인을 도입한 브라질의 라벨 인쇄업체 동향은 거시경제 상황이 안정되면 도입 기간을 단축할 수 있는 새로운 기술의 비약적인 발전을 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the UV cured printing inks market size was valued at USD 1.75 billion in 2025 and estimated to grow from USD 1.88 billion in 2026 to reach USD 2.65 billion by 2031, at a CAGR of 7.17% during the forecast period (2026-2031).
This report is Segmented by Curing Process (Arc Curing and LED Curing), Ink Type (UV Flexo Inks, UV Offset Inks, UV Low Energy/LED Offset Inks, and More), Application (Packaging, Commercial and Publication, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global UV Cured Printing Inks Market Trends and Insights
Growing Demand from Digital and Inkjet Printing
Print-on-demand adoption lets publishers slash warehousing expenses and meet rapid turnaround expectations, and UV-cured inks enable crisp imagery on coated and uncoated substrates without post-press drying delays. Direct mail volumes are rebounding as brands integrate tactile pieces with digital campaigns, reinforcing demand for durable, scuff-resistant UV impressions that withstand postal handling. Research and development momentum is visible in FUJIFILM's patent covering surfactant-modified inkjet formulations that reduce inter-color bleeding and heighten gloss uniformity, an advance that strengthens UV compatibility with high-speed piezo heads. Commercial shops that add web-to-print storefronts tap short-run personalized jobs where instant curing shortens job queues. Although legacy publication volumes keep shrinking, the value shift to variable-data and specialty substrates produces a net positive pull on UV-cured printing inks market growth.
Expansion of Packaging and Label Converters
Converter capacity is rising across Indonesia, India, and Vietnam as regional FMCG demand climbs and global brands nearshore supply chains; each new press line typically specifies LED UV or hybrid curing to cut make-ready waste and satisfy factory ESG benchmarks. Flexographic press upgrades, exemplified by Miraclon's FLEXCEL NX platform, let converters match gravure aesthetics while using thinner plates and lower ink laydowns that suit UV formulations. Brand-owner sustainability scorecards increasingly credit energy savings from UV LED curing, nudging converters toward technology refresh. The dual need to meet food-contact rules and lower total cost of ownership cements packaging's pull on the UV-cured printing inks market.
Decline of Conventional Commercial Printing
Newspaper and magazine pagination keeps sliding as advertisers channel budgets into digital platforms, eroding legacy UV offset ink demand. Commercial printers that fail to pivot toward packaging, labels, or value-added embellishments face press under-utilization that directly reduces ink consumption. While high-margin short runs temper revenue loss, volume attrition persists, marking this restraint as a structural headwind.
Other drivers and restraints analyzed in the detailed report include:
- Stricter VOC/Sustainability Regulations
- Rapid Shift to Energy-Efficient LED UV Systems
- Competition from Water-Based and EB-Curable Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
LED systems accounted for 56.14% of the UV-cured printing inks market size in 2025 and are forecast to post a 9.13% CAGR to 2031, underlining the technology's broad acceptance among converters focused on energy metrics. The retrofit option lowers capital hurdles, letting operators preserve existing press platforms while sharply reducing downtime. Lower stack temperatures eliminate sheet distortion on thin films and enable higher nip pressures that maintain registration accuracy at press speeds above 18,000 sph. These attributes collectively sustain LED's leadership in the UV-cured printing inks market.
Arc-lamp curing retains a toehold in certain wide-web and screen-printing applications that need broadband spectra to trigger cationic photochemistry. However, recent high-output LED diodes reaching 25 W/cm2 narrow the former gap in cure depth, and hybrid lamp housings let users toggle modes mid-shift, hastening the migration curve. As government restrictions on mercury escalate, arc-lamp economics will further erode, reinforcing LED's dominant trajectory.
Complete Report Scope:
- By Curing Process
- Arc Curing
- LED Curing
- By Ink Type
- UV Flexo Inks
- UV Offset Inks
- UV Low Energy/LED Offset Inks (Except UV Offset Inks)
- UV Screen Printing Inks
- Other UV Cured Printing Inks Type
- By Application
- Packaging
- Commercial and Publication
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 48.05% of 2025 revenue and is tracking a 9.08% CAGR to 2031, led by China's nationwide GB 4806.14-2023 compliance deadline and India's IS:15495 enforcement that restricts toluene in food packaging inks. Local leaders such as UFlex have introduced polyester acrylates that bond to metallized films, enabling converters to meet both barrier and migration goals in a single pass. Government incentives that refund up to 30% of energy-saving equipment costs further accelerate LED UV adoption across new gravure and flexo halls, cementing the region's pull on the UV-cured printing inks market.
North America holds a technology-rich base where early adopters embraced LED units as early as 2016. The U.S. EPA's endorsement and the Inflation Reduction Act's clean-manufacturing credits financed numerous retrofits during 2024-25. Resin and additive capacity expansions, exemplified by Lubrizol's doubling of Solsperse hyperdispersant output in Ohio, bolster supply assurance for domestic ink makers.
The Middle East and Africa, and South America contribute modest volume shares today, yet represent latent upside as packaging converters migrate from solvent lines to LED platforms to comply with export customer audits. Brazilian label printers installing hybrid UV-EB flexo lines attest to an emerging technology leapfrog that could compress adoption timelines once macroeconomic conditions stabilize.
- ALTANA
- APV Engineered Coatings
- artience Co. Ltd. (TOYO INK CO., LTD.)
- Avery Dennison Corporation
- DIC Corporation
- Flint Group
- FUJIFILM Corporation
- Huber Group
- Marabu GmbH & Co. KG
- MIMAKI ENGINEERING CO., LTD.
- Nazdar
- SAKATA INX CORPORATION
- Siegwerk Druckfarben AG & Co. KGaA
- T&K TOKA Corporation
- TOKYO PRINTING INK MFG. CO., LTD.
- Van Son Ink Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand from Digital and Inkjet Printing
- 4.2.2 Expansion of Packaging and Label Converters
- 4.2.3 Stricter VOC/Sustainability Regulations
- 4.2.4 Rapid Shift to Energy-Efficient LED UV Systems
- 4.2.5 Adoption of Low-Migration Inks in Food and Pharma Packs
- 4.3 Market Restraints
- 4.3.1 Decline of Conventional Commercial Printing
- 4.3.2 Competition from Water-Based and EB-Curable Systems
- 4.3.3 Photoinitiator Supply-Chain Volatility (China Clampdowns)
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Curing Process
- 5.1.1 Arc Curing
- 5.1.2 LED Curing
- 5.2 By Ink Type
- 5.2.1 UV Flexo Inks
- 5.2.2 UV Offset Inks
- 5.2.3 UV Low Energy/LED Offset Inks (Except UV Offset Inks)
- 5.2.4 UV Screen Printing Inks
- 5.2.5 Other UV Cured Printing Inks Type
- 5.3 By Application
- 5.3.1 Packaging
- 5.3.2 Commercial and Publication
- 5.3.3 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 Italy
- 5.4.3.4 France
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (Mergers and Acquisitions, JV, Partnerships)
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ALTANA
- 6.4.2 APV Engineered Coatings
- 6.4.3 artience Co. Ltd. (TOYO INK CO., LTD.)
- 6.4.4 Avery Dennison Corporation
- 6.4.5 DIC Corporation
- 6.4.6 Flint Group
- 6.4.7 FUJIFILM Corporation
- 6.4.8 Huber Group
- 6.4.9 Marabu GmbH & Co. KG
- 6.4.10 MIMAKI ENGINEERING CO., LTD.
- 6.4.11 Nazdar
- 6.4.12 SAKATA INX CORPORATION
- 6.4.13 Siegwerk Druckfarben AG & Co. KGaA
- 6.4.14 T&K TOKA Corporation
- 6.4.15 TOKYO PRINTING INK MFG. CO., LTD.
- 6.4.16 Van Son Ink Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment