

|
시장보고서
상품코드
2122377
풍력터빈용 복합재료 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Wind Turbine Composite Materials - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 풍력터빈용 복합재료 시장 규모는 142억 6,000만 달러로 추정되며, 2025년 134억 5,000만 달러에서 2031년에는 191억 1,000만 달러에 달할 것으로 예측됩니다.
2026-2031년 기간 동안의 연평균 성장률(CAGR)은 6.02%를 나타낼 전망입니다.
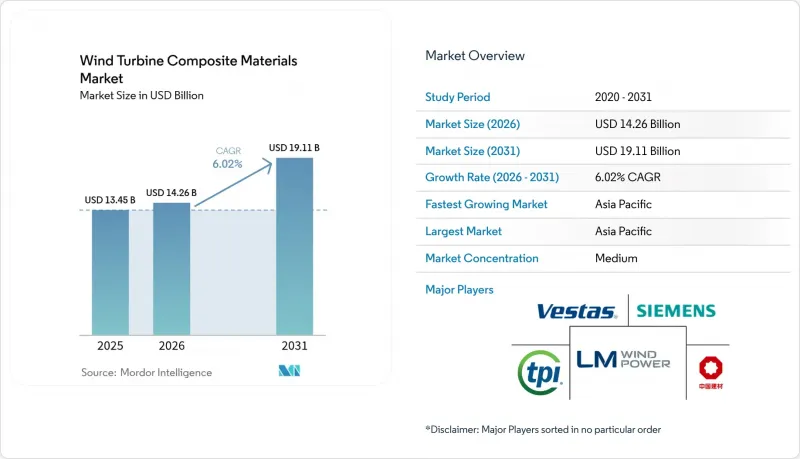
본 보고서는 섬유 유형별(유리 섬유, 탄소섬유, 천연·하이브리드 섬유), 수지 유형별(에폭시, 폴리에스터/비닐 에스테르, 폴리우레탄, 열가소성 수지), 기술별(진공 주입, 프리프레그, 기타),용도별(풍력 터빈 블레이드, 나셀·노즈콘, 기타), 지역별(아시아태평양, 북미, 유럽, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 풍력 터빈용 복합재료 시장 동향 및 인사이트
육상·해상 풍력 터빈 용량 확대에 따른 경량·장축 블레이드에 대한 수요 증가
현재 전 세계 풍력 터빈의 정격 출력은 해상에서 15MW를 일상적으로 초과하고 있으며, 이에 따라 블레이드 길이는 115m를 넘어, 고성능 복합재료만이 견딜 수 있는 구조적 하중이 두 배로 증가하고 있습니다. 베스타스(Vestas)사의 V236-15MW 플랫폼에 탑재된 전장 115.5m의 블레이드나,지멘스·가메사사의 비공개 21.5MW 프로토타입은 로터당 복합재료 사용량을 증가시키는 스케일업의 좋은 사례이며, 동시에 강성과 내피로성을 확보하기 위해 더욱 경량화된 탄소섬유 강화 스파 캡이 필수적입니다. 영국만 해도 2030년까지 해상 풍력 발전 용량을 최대 50GW까지 확대하는 것을 목표로 하고 있으며, 이 목표는 부식성이 강한 해양 환경에서 25년의 설계 수명을 실현할 수 있는 고성능 라미네이트 시스템에 대한 장기적인 수요를 확고히 하고 있습니다.
정부의 탈탄소 목표와 CFD 경매를 통한 풍력 발전 개발 가속화
영국의 해상 풍력 발전 전용 12억 달러 규모의 CfD(차액 계약) 라운드와,중국의 2024년 풍력 발전 설비 설치량이 사상 최대인 117GW에 달하는 등 지원적인 프레임워크 덕분에, 수 기가와트 규모의 입찰 프로젝트가 확실시되면서 새로운 복합재료 공장에 대한 투자 위험이 완화되고 있습니다. 저탄소 공급망을 장려하는 청정 산업 보너스 제도는 현지 블레이드 생산과 더욱 친환경적인 수지 화학 기술 개발을 촉진하고 있습니다. 유럽 그린딜이 정한 2030년 재생에너지에 관한 법적 구속력 있는 목표와, 독일이 내세운 ‘전력의 80%를 청정 에너지로 충당한다’는 목표는 풍력 터빈용 복합재료 시장 전체 수요 전망을 확고히 하고 있으며, 베스타스(Vestas),LM 윈드 파워(LM Wind Power), 중국의 주요 유리섬유 제조업체들의 생산 능력 확장을 뒷받침하고 있습니다. 탄소 가격 책정 및 재생에너지 크레딧(REC)는 프로젝트의 경제성을 더욱 높여주며, 가볍고 내구성이 뛰어나며 재활용 가능한 복합재료에 대한 지속적인 수요를 보장하고 있습니다.
탄소섬유의 가격 및 공급 변동
100미터를 초과하는 블레이드에 대한 수요가 급증함에 따라 2027년까지 탄소섬유 소비량은 3배로 증가할 것으로 예상되지만, 생산 능력 확대가 이를 따라가지 못해 가격 급등을 초래하고 있습니다. 이로 인해 비용에 민감한 풍력 터빈 분야에서 탄소섬유의 보급이 저해되고 있습니다. 2023년에 6만 9,000톤의 탄소섬유를 흡수한 중국 시장에서는 수출 규제와 지정학적 마찰이 공급망을 혼란에 빠뜨려 가격이 격렬하게 변동했습니다. 이에 따라 각 OEM 기업들은 가격 변동 위험을 헤지하기 위해 유리섬유와 탄소섬유를 결합한 하이브리드 구조나 현지 조달을 모색하고 있습니다. 2030년에 예상되는 45만 톤을 향해 추가 생산 라인이 전 세계 생산량을 끌어올릴 때까지, 풍력 터빈용 복합재료 시장은 불안정한 원자재 비용에 대처해 나가야 합니다.
부문 분석
유리섬유는 비용 면에서의 우위와 견고한 공급망에 힘입어 2025년 풍력 터빈용 복합재료 시장에서 71.10%라는 압도적인 점유율을 유지했습니다. 그러나 OEM 각사가 경량화를 추구하는 가운데, 탄소섬유는 연평균 성장률(CAGR) 6.85%로 성장하고 있습니다. 이로 인해 더 긴 로터가 과도한 부하를 주지 않으면서도 더 높은 선단 속도를 견딜 수 있게 되었습니다. LM Wind Power가 88.4m 블레이드에 채택한 탄소/유리섬유 하이브리드 소재의 스퍼 캡은 비용 급등을 초래하지 않으면서 경량화를 실현했음이 입증되었습니다.
또한, 항공우주 등급보다 40% 저렴한 섬유계 탄소섬유의 채택이 확대되고 있어, 이를 통해 중급 터빈 부문에 진입할 수 있게 되었습니다. 천연섬유의 혼합은 지속 가능한 틈새 시장을 개척하고 있으며, 야자나 아마를 활용한 하이브리드 소재는 주요 기계적 성능을 충족시키면서 제조에 소요되는 에너지를 절감하고 있습니다. 예측 기간 동안, 풍력 터빈용 복합재료 시장이 강성, 피로 수명, 합리적인 가격의 균형을 모색하는 가운데, 하이브리드화 전략은 계속해서 매우 중요한 역할을 할 것으로 보입니다.
에폭시계 수지는 그 정평이 난 성능 덕분에 2025년에 매출 점유율 34.40%를 차지했으나, 폴리에스테르/비닐 에스테르 및 폴리우레탄 혼합은 7.12%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 사이클 타임을 10-25% 단축하고 ?아웃성을 향상시킨 것이 입증됨에 따라, 폴리우레탄 인퓨전 공법은 막대한 설비 투자를 수반하지 않고 연간 생산량을 확대하기 위한 가장 유력한 선택지가 되고 있습니다.
라이프사이클 배출량을 30-40% 감축하는 바이오 화학물질에 대한 수요가 배합 연구 개발을 주도하여, 보다 친환경적인 수지를 사용하는 풍력 터빈용 복합재료 시장 규모를 확대할 것으로 보입니다. 특히, 입찰 시 이미 탄소 발자국 공개가 요구되고 있는 유럽에서는 이러한 경향이 두드러집니다. 발열 피크를 줄여주는 Baxxodur 경화제 및 첨가제 패키지는 에폭시 수지와의 경쟁을 더욱 심화시켜, 2031년까지 여러 수지 유형가 공존할 것을 확실히할 것입니다.
지역별 분석
아시아태평양은 2025년 매출의 46.10%를 차지하며 풍력 터빈용 복합재료 시장의 핵심 지역으로 자리매김하고 있으며, 6.72%라는 업계 최고 수준의 연평균 성장률(CAGR)을 기록하고 있습니다. 중국 Jushi와 CPIC에 유리한 현지 조달 규정의 뒷받침을 받아, 2024년에 중국이 사상 최대인 117GW의 신규 설치를 달성한 것은 원단에서 완성된 블레이드에 이르기까지 전 세계로 수출하는 유례없는 공급망 기반을 공고히 하고 있습니다.
이에 이어 유럽에서는 성숙한 기술의 도입과 엄격한 지속가능성 규제가 진행되고 있습니다. 2030년까지 최대 50GW의 해상 풍력 발전을 실현하겠다는 영국의 목표, 독일의 청정 에너지 80% 달성 목표, 프랑스의 순환 경제 관련 의무화로 인해 유럽 제조업체들은 재활용 가능한 열가소성 플라스틱 및 폐쇄형 성형으로의 전환을 요구받고 있습니다.
북미에서는 연방 정부의 세액 공제와 주 정부의 조달 정책을 결합하여, 그레이트 플레인스 지역의 육상 풍력 발전소 확대와 연안 풍력 발전 구역의 설비 갱신이 진행되고 있습니다. 미국 에너지부는 2027년까지 복합재료 수요가 3배 증가할 것으로 예측하고 있으며, 이에 따라 TPI Composites와 GE Vernova는 스퍼 캡 및 루트 인서트의 현지 생산을 위한 투자를 추진하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, wind turbine composite materials market size in 2026 is estimated at USD 14.26 billion, growing from 2025 value of USD 13.45 billion with 2031 projections showing USD 19.11 billion, growing at 6.02% CAGR over 2026-2031.
This report is Segmented by Fiber Type (Glass Fiber, Carbon Fiber, Natural/Hybrid Fibers), Resin Type (Epoxy, Polyester/Vinyl-Ester, Polyurethane, Thermoplastic Resins), Technology (Vacuum Infusion, Prepreg, and More), Application (Wind Blades, Nacelles and Nose Cones, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Wind Turbine Composite Materials Market Trends and Insights
Increasing Onshore and Offshore Turbine Capacities Drive Demand for Advanced Composites
Global turbine ratings now routinely exceed 15 MW offshore, pushing blade lengths past 115 m and multiplying structural loads that only advanced composites can withstand. Vestas' 115.5 m-long blades on the V236-15 MW platform and Siemens Gamesa's confidential 21.5 MW prototype exemplify the scale-up that magnifies composite volume per rotor while simultaneously mandating lighter carbon-reinforced spar caps for stiffness and fatigue resistance. The United Kingdom alone aims to raise offshore capacity to as much as 50 GW by 2030, a target that cements long-term pull for high-performance laminate systems able to deliver a 25-year design life in corrosive marine environments.
Government Decarbonization Policies Accelerate Composite Material Adoption
Supportive frameworks, such as the United Kingdom's USD 1.2 billion CfD round dedicated to offshore wind and China's record 117 GW of 2024 wind installations, lock in multi-gigawatt auction pipelines and de-risk investments in new composite plants. Clean-industry bonus mechanisms that reward low-carbon supply chains are encouraging local blade production and greener resin chemistries. The European Green Deal's binding 2030 renewables targets, along with Germany's 80% clean-power ambition, consolidate demand visibility across the wind turbine composites market and motivate capacity expansions from Vestas, LM Wind Power, and Chinese glass-fiber majors. Carbon pricing and renewable energy certificates further boost project economics, ensuring sustained pull for lightweight, durable, and recyclable composites.
Carbon Fiber Price Volatility Constrains Premium Applications
Surging demand for 100 m-plus blades is expected to triple carbon consumption by 2027, yet capacity expansions lag, creating price spikes that discourage wider uptake in cost-sensitive turbines. China's market, which absorbed 69,000 t of carbon fiber in 2023, saw sharp swings as export restrictions and geopolitical frictions disrupted supply chains. OEMs, therefore, pursue hybrid glass-carbon architectures and localized sourcing to hedge volatility. Until additional lines lift global output toward the 450,000 tons predicted for 2030, the wind turbine composites market must navigate erratic input costs.
Other drivers and restraints analyzed in the detailed report include:
- Polyurethane Infusion Resins Transform Manufacturing Economics
- Bio-based Thermoplastic Systems Enable Circular-Economy Transition
- Regulatory Emission Limits Drive Manufacturing-Process Transformation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Glass fiber retained a dominant 71.10% share of the wind turbine composites market in 2025, underpinned by favorable cost and robust supply chains. Carbon, however, is growing at 6.85% CAGR as OEMs chase mass reductions that let longer rotors survive higher tip speeds without excess loads. LM Wind Power's hybrid carbon/glass spar caps on its 88.4 m blade validated weight cuts without cost blowouts.
Incremental uptake also stems from textile-based carbon fibers that are 40% cheaper than aerospace grades, unlocking mid-tier turbine segments. Natural-fiber blends offer sustainable niches, with palm or flax hybrids matching key mechanical metrics while lowering embodied energy. Over the forecast horizon, hybridization strategies will remain pivotal as the wind turbine composites market balances stiffness, fatigue life and affordability.
Epoxy systems held 34.40% revenue share in 2025, thanks to well-characterized performance, yet polyester/vinyl-ester and polyurethane blends are tracking the fastest 7.12% CAGR. Proven 10-25% cycle-time savings and improved wet-out make polyurethane infusion the prime candidate for stretching annual output without large capex.
Demand for bio-based chemistries that curb life-cycle emissions by 30-40% will steer formulation research and development, broadening the wind turbine composites market size for greener resins, particularly in Europe, where carbon-footprint disclosures already feature in tenders. Baxxodur curing agents and additive packages that cut exotherm peaks further enhance epoxy competitiveness, ensuring multiple resin classes co-exist through 2031.
Complete Report Scope:
- By Fiber Type
- Glass Fiber
- Carbon Fiber
- Natural/Hybrid Fibers
- By Resin Type
- Epoxy
- Polyester/Vinyl-Ester
- Polyurethane
- Thermoplastic Resins
- By Technology
- Vacuum Infusion
- Prepreg
- Hand Lay-up
- Filament Winding / Pultrusion
- By Application
- Wind Blades
- Nacelles and Nose Cones
- Hubs, Covers and Ancillary Parts
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia Pacific, at 46.10% of 2025 revenue, remains the anchor region for the wind turbine composites market and posts a leading 6.72% CAGR. China's record 117 GW of 2024 additions, supported by local-content rules favoring China Jushi and CPIC, underpin an unrivaled supply-chain footprint that exports both raw fabrics and finished blades worldwide.
Europe follows with mature technology adoption and rigorous sustainability regulations. The United Kingdom's ambition to reach up to 50 GW of offshore wind by 2030, Germany's 80% clean-power target, and France's circular-economy mandates push European makers toward recyclable thermoplastics and closed molding.
North America couples federal tax credits with state procurement to expand onshore fleets in the Great Plains and repower coastal wind zones. The U.S. Department of Energy forecasts composite demand tripling by 2027, propelling investments from TPI Composites and GE Vernova that localize spar-cap and root-insert production.
- AVIC Huiteng Windpower
- BASF
- China Jushi Co., Ltd.
- Covestro AG
- Exel Composites
- Gurit Holding AG
- Hexcel Corporation
- INCA Renewtech
- Lianyungang Zhongfu Lianzhong Composite Material Group Co., Ltd
- LM WIND POWER
- Molded Fiber Glass Companies
- Owens Corning
- Reliance Industries Limited
- SGL Carbon
- Siemens AG
- Sinoma Science & Technology Co.,Ltd.
- Teijin Limited
- TORAY INDUSTRIES, INC.
- TPI Composites
- Vestas
- Zhongfu Lianzhong Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Drivers
- 4.1.1 Increasing Onshore and Offshore Turbine Capacities Drive the Need for Lighter, Longer Blades.
- 4.1.2 Government Decarbonization Goals and CFD Auctions are Speeding Up Wind Energy Development.
- 4.1.3 Cost-Saving Polyurethane Infusion Resins Shorten Cycle Time
- 4.1.4 Bio-Based/Recyclable Thermoplastic Systems Unlock ESG Finance
- 4.1.5 Composites Compatible with Smart Fabrics Facilitate Digital Twinning of Blades.
- 4.2 Market Restraints
- 4.2.1 Carbon-Fiber Price and Supply Volatility
- 4.2.2 Upcoming BPA and Styrene Emission Limits for Composites
- 4.2.3 Skilled-Labour Deficit in Advanced Infusion for Emerging Hubs
- 4.3 Value Chain Analysis
- 4.4 Porter's Five Forces
- 4.4.1 Bargaining Power of Suppliers
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Threat of New Entrants
- 4.4.4 Threat of Substitutes
- 4.4.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Fiber Type
- 5.1.1 Glass Fiber
- 5.1.2 Carbon Fiber
- 5.1.3 Natural/Hybrid Fibers
- 5.2 By Resin Type
- 5.2.1 Epoxy
- 5.2.2 Polyester/Vinyl-Ester
- 5.2.3 Polyurethane
- 5.2.4 Thermoplastic Resins
- 5.3 By Technology
- 5.3.1 Vacuum Infusion
- 5.3.2 Prepreg
- 5.3.3 Hand Lay-up
- 5.3.4 Filament Winding / Pultrusion
- 5.4 By Application
- 5.4.1 Wind Blades
- 5.4.2 Nacelles and Nose Cones
- 5.4.3 Hubs, Covers and Ancillary Parts
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Strategic Moves
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 AVIC Huiteng Windpower
- 6.3.2 BASF
- 6.3.3 China Jushi Co., Ltd.
- 6.3.4 Covestro AG
- 6.3.5 Exel Composites
- 6.3.6 Gurit Holding AG
- 6.3.7 Hexcel Corporation
- 6.3.8 INCA Renewtech
- 6.3.9 Lianyungang Zhongfu Lianzhong Composite Material Group Co., Ltd
- 6.3.10 LM WIND POWER
- 6.3.11 Molded Fiber Glass Companies
- 6.3.12 Owens Corning
- 6.3.13 Reliance Industries Limited
- 6.3.14 SGL Carbon
- 6.3.15 Siemens AG
- 6.3.16 Sinoma Science & Technology Co.,Ltd.
- 6.3.17 Teijin Limited
- 6.3.18 TORAY INDUSTRIES, INC.
- 6.3.19 TPI Composites
- 6.3.20 Vestas
- 6.3.21 Zhongfu Lianzhong Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Government net-zero targets are accelerating global wind power installations.


