

|
시장보고서
상품코드
2122404
유압 펌프 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hydraulic Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 유압 펌프 시장 규모는 2025년에 139억 달러로 평가되며, 2026년 146억 4,000만 달러에서 2031년까지 189억 9,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 5.35%에 달할 전망입니다.
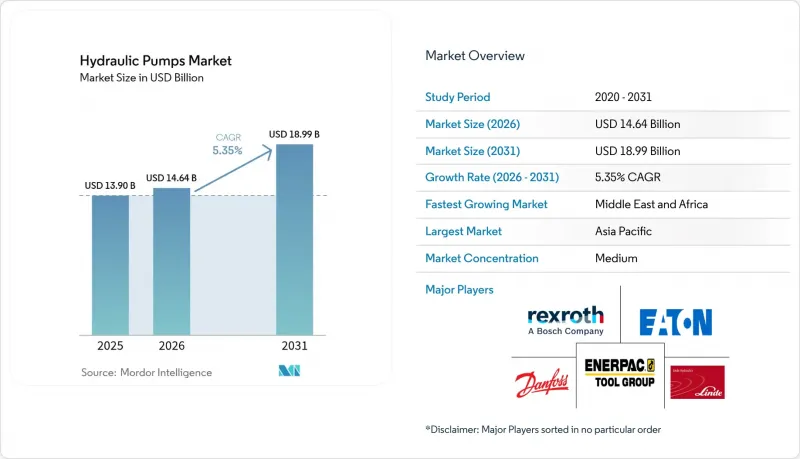
이 보고서는 펌프 유형별(기어, 베인, 기타), 작동 압력 범위별(3,000psi 미만, 3,000-5,000psi, 5,000psi 초과),용도별(이동식 유압 장비, 산업 기계, 공정·에너지), 최종사용자 산업별(건설, 석유 및 가스, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 유압 펌프 시장의 동향 및 인사이트
중국과 인도의 인프라 현대화 계획
양국에서 정부 자금을 통한 건설 프로젝트 계획에 따라 2025년까지 연간 1,350만 대 이상의 유압 펌프에 대한 수요가 유지될 전망입니다. 공공 부문 프로젝트의 현지화 규정은 합작 투자를 촉진하고 있으며, 이로 인해 약 42억 달러가 첨단 펌프 생산에 투입되어 국내 역량 구축이 가속화되고 있습니다. 중국의 장비 규격을 채택하는 지역 계약업체들은 공급망을 중동 및 아프리카로 확대하고 있으며, 아시아태평양 제조업체들의 수출 전망이 밝아지고 있습니다. 이러한 프로그램들은 특히 정격 5,000psi를 초과하는 제품에 대해 2027년까지 기준 수요를 지원할 것으로 예상됩니다.
산업 자동화(인더스트리 4.0으로의 전환)
가변 주파수 드라이브가 탑재된 스마트 파워 유닛은 유휴시 에너지 소비를 25% 절감합니다. IoT 게이트웨이는 실시간 데이터를 예측 유지보수 플랫폼으로 전송하여, 영국의 한 수도 사업자가 슐러(Sulzer)사의 컨트롤러를 사용하여 실시한 검사에서 나타난 바와 같이, 운영 비용을 45% 절감하고 예기치 못한 배출 사고를 75% 감소시킵니다. 디지털 트윈 모델을 통한 원격 최적화를 통해 30%의 에너지 절감과 총 소유 비용(TCO) 20% 감소를 실현합니다. 미국 CISA가 CVSS 점수가 최대 9.8에 달하는 펌프 컨트롤러의 취약점에 대해 권고를 발표한 이후, 사이버 보안에 대한 우려는 계속해서 높아지고 있습니다.
니켈 및 철강 가격 변동
니켈 함유 합금의 비용은 미국의 인프라 지출이 재개됨에 따라 2024년 말까지 상승한 후 일시적으로 하락했으나, 2025년 초에 다시 반등하여 펌프 제조업체의 이익률을 압박하는 동시에 재고 계획 수립을 어렵게 만들고 있습니다. 안전 기준에 따라 고품질 강재의 사용이 의무화되어 있으므로 고압(3,000psi 초과) 모델이 가장 큰 영향을 받고 있습니다. 수입된 고품질 합금에 의존하고 있는 중국 제조업체들은 환율 리스크 증가와 물류 추가 비용 부담에 직면해 있습니다.
부문별 분석
2025년, 기어 펌프는 이동식 기계의 수요에 힘입어 매출 점유율 36.45%를 유지했습니다. 피스톤 펌프는 각 OEM 업체들이 더 높은 용적 효율과 정밀한 배기량 제어로 전환함에 따라 2031년까지 연평균 성장률(CAGR) 6.45%로 성장하고 있습니다. 파커 허니핀의 PV140 피스톤 시리즈는 호주 광산용 차량에서 오버홀 주기가 1만 4,000 가동 시간에 달하여 수명 주기 비용 면에서 우위를 보이고 있습니다. 베인 펌프와 스크류 펌프는 부드러운 유량과 선박 등급의 신뢰성이 요구되는 틈새 용도에서 계속해서 사용되고 있습니다.
2세대 피스톤 펌프 설계에서는 경화 처리된 스풀 밸브와 보강된 스와시 플레이트를 채택하여 평균 고장 간격(MTBF)을 15,000시간으로 연장함으로써, 기존 기계 유형에 비해 수명을 2배로 늘렸습니다. 텔레핸들러, 굴착기, 사출성형기에 대한 채택은 에너지 최적화와 CO₂ 배출량 감축을 위한 체계적인 전환을 지원하고 있습니다. 피스톤 기술을 이용한 유압 펌프 시장 규모는 산업용 및 재생 가능 에너지 설비 모두에서 점유율을 확대할 것으로 예상됩니다.
2025년에는 3,000-5,000psi 등급이 전 세계 시장 규모의 41.35%를 차지하며, 주류 건설 기계 및 농업용 시추 장비를 아우를 것으로 보입니다. 5,000psi를 초과하는 정격 펌프는 수소 압축, 해상 풍력발전, 첨단 머시닝 센터의 수요에 힘입어 연평균 7.95%의 성장률을 기록하고 있습니다. North Ridge Pumps의 ATEX 구역 인증을 받은 다단 부스터는 1,000bar에서 연속 운전을 요구하는 전해조 개발자의 요구를 충족시키고 있습니다. 3,000psi 이하의 유닛은 성능 기준이 비교적 낮은 비용 중심의 시장에서 공급량의 안정성을 유지하고 있습니다.
상류 공정에서의 혁신은 극한 압력 하에서 누출을 억제하기 위한 실 시스템과 미세 마감 표면 처리에 초점을 맞추고 있습니다. 2상 스테인리스강 및 나노코팅 분야의 재료 과학의 비약적인 발전은 피로 내성 향상을 목표로 하고 있으며, 실시간 압력 저감 알고리즘은 치명적인 고장을 미연에 방지합니다. 이러한 발전으로 인해 에너지 전환 프로젝트 내에서 고압 전문 제조업체가 차지하는 유압 펌프 시장 점유율이 더욱 공고해지고 있습니다.
지역별 분석
아시아태평양의 주도적 지위는 타의 추종을 불허하는 생산 규모와 국내 소비에서 비롯되며, 2025년에는 중국에서만 1,350만 대가 구매될 것으로 예상됩니다. 인도의 ‘스마트 시티 미션’과 같은 정부 프로그램을 통해 고압 유압 시스템이 필요한 수자원 관리, 지하철, 저렴한 주택 프로젝트에 자본이 투입되고 있습니다. 일본의 공급업체들은 신뢰성 면에서 계속해서 업계 표준을 정립하고 있습니다. 가와사키 중공업의 K3VL 축 피스톤 시리즈는 고급 굴착기에 자주 채택되고 있습니다. 공급망 혼란과 숙련된 인력 부족으로 인해 자동화와 베트남 및 인도네시아로의 지역 다각화가 진행되고 있습니다.
중동의 급속한 성장은 석유 및 가스 산업에 대한 재투자 및 재생 가능 에너지로의 다각화 전략에 힘입고 있습니다. 사우디아라비아 공공투자기금(PIF)은 태양광발전소 및 풍력발전소 건설에 수십억을 투자하고 있으며, 이곳에서는 유압식 요·피치 구동 장치가 터빈의 가동 시간을 지원하고 있습니다. 아랍에미리트(UAE)의 송전망 업그레이드에 따라 변전소 냉각 및 해수 담수화용 고압 펌프가 수입되고 있습니다. 담맘과 아부다비에서의 합작 생산을 통해 리드타임이 단축되었으며, 현지 조달률 요건도 충족되고 있습니다.
북미와 유럽에서는 기술적으로 첨단 기계 군이 유지되고 있습니다. 미국의 ‘인프라 투자 및 고용법’에 따라 토목 공사에 대한 지출이 재개되면서, 스키드 스티어 로더나 포장기 등의 교체 수요가 활발해지고 있습니다. 순환형 경제 준수를 촉진하는 EU 규제로 인해 리매뉴팩처링을 통한 새로운 수입원이 창출되고 있으며, EN ISO 14971 인증을 획득한 에코디자인 펌프에 대한 수요가 증가하고 있습니다. 두 지역 모두 기술자의 고령화라는 과제에 직면해 있으며, 서비스 제공의 병목 현상을 완화하기 위해 원격 진단 도입이 확대되고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.07According to Mordor Intelligence, the hydraulic pumps market size was valued at USD 13.9 billion in 2025 and estimated to grow from USD 14.64 billion in 2026 to reach USD 18.99 billion by 2031, at a CAGR of 5.35% during the forecast period (2026-2031).
This report is Segmented by Pump Type (Gear, Vane, and More), Operating-Pressure Range (5, 000 Psi), Application (Mobile Hydraulics, Industrial Machinery, Process and Energy), End-User Vertical (Construction, Oil and Gas, and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Hydraulic Pumps Market Trends and Insights
Infrastructure renewal programs in China and India
Government-funded construction pipelines in both nations sustain annual demand for more than 13.5 million hydraulic pump units by 2025. Localization rules for public-sector projects incentivise joint ventures, channelling roughly USD 4.2 billion into high-tech pump production and accelerating domestic capability building. Regional contractors adopting Chinese equipment standards are extending the supply chain into the Middle East and Africa, broadening export prospects for APAC manufacturers. These programmes are expected to underpin baseline demand through 2027, particularly for units rated above 5000 psi.
Industrial automation (Industry 4.0 retrofits)
Smart power units equipped with variable-frequency drives trim idle-time energy consumption by 25%. IoT gateways stream real-time data into predictive-maintenance platforms, cutting operating costs by 45% and reducing unplanned emissions events by 75%, as shown in UK water-utility trials with Sulzer controllers. Digital twin models enable remote optimisation that delivers 30% energy savings and 20% reduction in total cost of ownership. Cyber-security remains a rising concern following US CISA advisories on pump-controller vulnerabilities carrying CVSS scores up to 9.8.
Volatile nickel-steel prices
Nickel-bearing alloy costs climbed through late-2024 on renewed US infrastructure spending before receding, then rebounded in early-2025, compressing pump-maker margins and complicating inventory planning. High-pressure (>3000 psi) models suffer the most, as safety codes mandate premium steel grades. Chinese producers, reliant on imported high-grade alloy, face added currency risk and logistics surcharges.
Other drivers and restraints analyzed in the detailed report include:
- Off-highway electrification needs electro-hydraulic pumps
- Hydrogen electrolyser build-out (>1000 bar pumps)
- Rapid penetration of all-electric actuators
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Gear pumps retained 36.45% revenue share in 2025 on the strength of mobile-machinery demand. Piston pumps are outpacing at 6.45% CAGR to 2031 as OEMs migrate toward higher volumetric efficiency and precise displacement control. Parker Hannifin's PV140 piston series recorded 14,000 operating hours between overhauls in Australian mining vehicles, illustrating lifecycle cost advantages. Vane and screw pumps continue serving niche applications requiring smooth flow or marine-grade reliability.
Second-generation piston designs use hardened spool valves and reinforced swash plates to extend mean-time-between-failure to 15,000 hours, doubling service life relative to legacy units. Their adoption in telehandlers, excavators, and injection-moulding machines underscores a systemic pivot toward energy optimisation and reduced CO2 footprints. The hydraulic pumps market size for piston technology is expected to capture an incremental share in both industrial and renewable-energy installations.
The 3000-5000 psi class represented 41.35% of global value in 2025, covering mainstream construction and agricultural rigs. Pumps rated above 5000 psi are growing 7.95% annually, propelled by hydrogen compression, offshore wind, and advanced machining centres. North Ridge Pumps' multi-stage boosters, certified for ATEX zones, meet electrolyser developers' need for continuous duty at 1000 bar. Below-3000-psi units maintain volume stability in cost-sensitive markets where performance thresholds remain modest.
Upstream innovation focuses on sealing systems and micro-finish surfaces to curb leakage at extreme pressures. Material-science breakthroughs in duplex stainless and nano-coatings aim to raise fatigue resistance, while real-time pressure-derating algorithms prevent catastrophic failures. These advances reinforce the hydraulic pumps market share held by high-pressure specialists amid energy-transition projects.
Complete Report Scope:
- By Pump Type
- Gear
- Vane
- Piston
- Screw
- By Operating-Pressure Range
- <3,000 psi
- 3,000 - 5,000 psi
- >5,000 psi
- By End-user Vertical
- Construction
- Oil and Gas
- Power Generation
- Food and Beverage
- Water and Waste-water
- Chemicals
- Others (Agriculture, Mining, Automotive)
- By Application
- Mobile Hydraulics
- Industrial Machinery
- Process and Energy (incl. wind, hydro, hydrogen)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of Latin America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
APAC's leadership derives from unmatched production scale and domestic consumption, with China alone purchasing 13.5 million units in 2025. Government programmes such as India's Smart Cities Mission funnel capital into water-management, metro-rail, and affordable-housing projects requiring high-pressure hydraulic systems. Japanese suppliers continue to set benchmarks for reliability; Kawasaki's K3VL axial piston line is frequently specified on premium excavators. Supply-chain disruptions and skilled-labour shortages encourage automation and regional diversification into Vietnam and Indonesia.
The Middle East's swift growth rests on oil-and-gas reinvestment and renewable diversification agendas. Saudi Arabia's Public Investment Fund channels billions into solar- and wind-farm construction, where hydraulic yaw and pitch drives underpin turbine uptime. UAE's transmission grid upgrades import high-pressure pumps for substation cooling and seawater desalination. Joint-venture manufacturing in Dammam and Abu Dhabi shortens lead times and meets local-content mandates.
North America and Europe maintain technologically advanced fleets. The US Infrastructure Investment and Jobs Act revived civil works outlays, fuelling replacements across skid-steer loaders and pavers. EU regulations promoting circular-economy compliance create new remanufacturing revenue and elevate demand for eco-design pumps certified under EN ISO 14971. Both regions contend with an ageing technician workforce, prompting wider deployment of remote diagnostics to ease service bottlenecks.
- Bosch Rexroth AG
- Eaton Corporation plc
- Danfoss Power Solutions A/S
- Enerpac Tool Group Corp.
- Linde Hydraulics GmbH and Co. KG
- Dynamatic Technologies Limited
- HYDAC International GmbH
- Parker Hannifin Corporation
- Kawasaki Heavy Industries Ltd.
- Daikin Industries Ltd.
- Bucher Hydraulics GmbH
- KYB Corporation
- Shimadzu Corporation
- Permco Inc.
- Casappa S.p.A.
- Ningbo Baichi Hydraulic
- HAWE Hydraulik SE
- Sun Hydraulics LLC
- Bosch Mahle Turbosystems Hydraulic (BMT)
- Bosch Rexroth India Pvt Ltd (regional)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure renewal programmes in China and India
- 4.2.2 Industrial automation (Industry 4.0 retrofits)
- 4.2.3 Off-highway electrification needs electro-hydraulic pumps
- 4.2.4 Wind-turbine yaw and pitch system demand
- 4.2.5 Hydrogen electrolyser build-out (>1 000 bar pumps)
- 4.2.6 Mandatory remanufacturing quotas (EU Circular Economy)
- 4.3 Market Restraints
- 4.3.1 Volatile nickel-steel prices
- 4.3.2 Rapid penetration of all-electric actuators
- 4.3.3 Cyber-security risks in smart pumps
- 4.3.4 Shortage of certified fluid-power technicians
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Pump Type
- 5.1.1 Gear
- 5.1.2 Vane
- 5.1.3 Piston
- 5.1.4 Screw
- 5.2 By Operating-Pressure Range
- 5.2.1 <3,000 psi
- 5.2.2 3,000 - 5,000 psi
- 5.2.3 >5,000 psi
- 5.3 By End-user Vertical
- 5.3.1 Construction
- 5.3.2 Oil and Gas
- 5.3.3 Power Generation
- 5.3.4 Food and Beverage
- 5.3.5 Water and Waste-water
- 5.3.6 Chemicals
- 5.3.7 Others (Agriculture, Mining, Automotive)
- 5.4 By Application
- 5.4.1 Mobile Hydraulics
- 5.4.2 Industrial Machinery
- 5.4.3 Process and Energy (incl. wind, hydro, hydrogen)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of Latin America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 New Zealand
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Bosch Rexroth AG
- 6.4.2 Eaton Corporation plc
- 6.4.3 Danfoss Power Solutions A/S
- 6.4.4 Enerpac Tool Group Corp.
- 6.4.5 Linde Hydraulics GmbH and Co. KG
- 6.4.6 Dynamatic Technologies Limited
- 6.4.7 HYDAC International GmbH
- 6.4.8 Parker Hannifin Corporation
- 6.4.9 Kawasaki Heavy Industries Ltd.
- 6.4.10 Daikin Industries Ltd.
- 6.4.11 Bucher Hydraulics GmbH
- 6.4.12 KYB Corporation
- 6.4.13 Shimadzu Corporation
- 6.4.14 Permco Inc.
- 6.4.15 Casappa S.p.A.
- 6.4.16 Ningbo Baichi Hydraulic
- 6.4.17 HAWE Hydraulik SE
- 6.4.18 Sun Hydraulics LLC
- 6.4.19 Bosch Mahle Turbosystems Hydraulic (BMT)
- 6.4.20 Bosch Rexroth India Pvt Ltd (regional)
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


