|
시장보고서
상품코드
2122414
핀테크용 AI : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)AI In Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
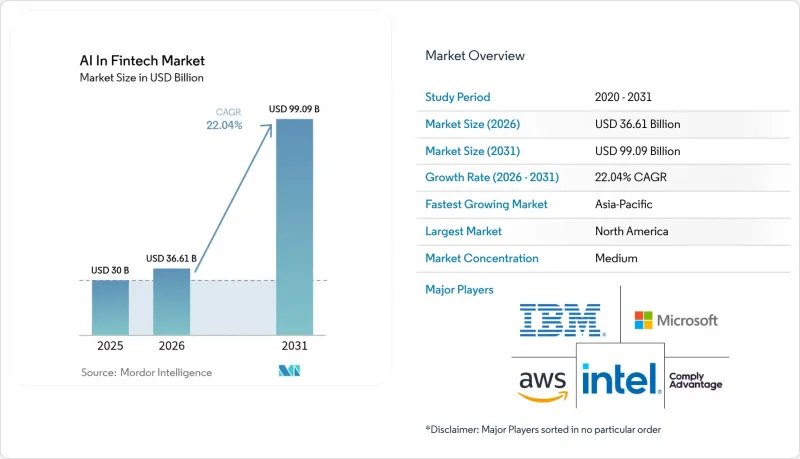
에 따르면 핀테크용 AI 시장 규모는 2025년에 300억 달러로 평가되며, 2026년 366억 1,000만 달러에서 2031년까지 990억 9,000만 달러에 달할 것으로 추정되고 있으며, 예측 기간(2026-2031년)에 CAGR은 22.04%에 달할 전망입니다.

[1] Microsoft "Azure AI가 금융 서비스의 생산성을 어떻게 재정의하고 있는가"(microsoft.com) 이러한 성장을 주도하고 있는 것은 상세한 고객 데이터의 공개를 초래하는 오픈 뱅킹 의무화, 실시간 결제 인프라의 성숙, 중견 은행의 운영 비용을 절감하는 클라우드 네이티브 AI 플랫폼입니다. [2] IBM '금융 서비스 분야의 생성형 AI - 리스크 모델 배포 가속화'(ibm.com) 생성형 AI를 활용한 코파일럿을 통해 모델 리스크 관리에 소요되는 기간이 수개월에서 수일로 단축되어, 금융 기관은 규정 준수를 충족하는 리스크 모델을 전례 없는 속도로 출시할 수 있게 되었습니다. 이 보고서는 유형별(솔루션, 서비스), 도입 형태별(클라우드, 온프레미스), 용도별(부정 리스크 관리, 챗봇·가상 비서, 기타), 조직 규모별(대기업, 중소기업·네오뱅크), 최종사용자별(소매 뱅킹, 보험, 기타), 지역별로 분류되어 있습니다.
글로벌 핀테크 AI 시장의 동향 및 인사이트
오픈 뱅킹 의무화에 따른 AI 주도 프로세스 자동화의 가속화
PSD3 등의 의무적인 데이터 공유 규정에 따라 AI 엔진은 여러 금융 기관의 기록에 대해 일관된 허가 기반의 접근 권한을 확보할 수 있게 되어, 실시간 신용 평가 및 고도로 개인화된 제안이 가능해집니다. PSD3는 2024년에 시행되며, 유럽의 은행들은 그동안 사일로화되어 있던 데이터세트를 기계학습 모델에 공급하는 ‘API 우선’ 아키텍처를 중심으로 상품 구성 워크플로우를 재설계하고 있습니다. 중견 금융기관들은 규정 준수에 대한 투자가 혁신을 촉진하는 요인으로 작용하고, 규제 준수 비용을 수익 성장의 원동력으로 전환함으로써 경쟁에서 대등한 입지를 확보하고 있습니다. 오픈 뱅킹 도입률이 금융기관의 87%를 넘는 시장에서는 이미 AI 서비스의 보급률이 현저히 높아지고 있습니다.
실시간 결제 데이터 스트림의 폭발적인 증가
VisaNet+AI는 각 승인 처리에서 98%의 안정적인 예측 정확도를 실현하고 있으며, 그 ‘Smarter Settlement Forecast’ 기능은 7일간의 현금 흐름 예측을 추가함으로써 유동성 완충 장치 축소에 기여하고 있습니다. 실시간 결제 네트워크는 배치 처리 시스템에서는 간과되기 쉬운 행동 패턴 신호를 전송하여, AI가 거래 시작 시점부터 밀리초 단위로 부정행위를 탐지할 수 있도록 합니다. 조사에 따르면 결제 전문가의 94%가 부정행위 방지에 AI가 필수적이라고 생각하며, 소비자의 77%가 금융기관의 AI 도입을 기대하고 있습니다. BNY 멜론은 백오피스 결제 지시 처리의 90%를 자동화하여 애널리스트들이 부가가치가 높은 업무에 전념할 수 있도록 했습니다. 또한 데이터를 즉시 활용할 수 있게 됨에 따라 동적인 현금 흐름 지표를 기반으로 한 실시간 신용 심사도 실현하고 있습니다.
특정 분야에 특화된 AI 인재 부족
기계학습에 능통하고 규제에 대한 깊은 지식을 겸비한 전문가에 대한 수요는 공급을 2-4배 상회하고 있으며, 고용주의 74%가 채용 어려움을 호소하고 있습니다. 유럽 은행에 따르면 정식 GenAI 교육 체계를 갖추고 있는 곳은 고작 25%에 불과하여 역량 격차가 확대되고 있습니다. 기존 금융직에 비해 40-60% 높은 급여 수준이 경쟁 구도를 대형 기술 기업이나 Tier 1 은행에 유리한 방향으로 기울게 하고 있습니다. 중견 금융기관에서는 인력 부족으로 인해 프로젝트 공수와 비용이 증가하여 도입이 정체될 위험에 직면해 있습니다.
부문 분석
솔루션 부문은 2025년에 214억 4,000만 달러의 매출을 창출하며, 이는 핀테크 AI 시장의 71.45%에 해당합니다. 기업은 사기 분석, 고객 지원, 거버넌스를 단일 제어 평면 내에서 통합하는 플랫폼을 선호하고 있습니다. 2025년 혁신상을 수상한 FICO의 블록체인 지원 거버넌스 제품군은 통합형 솔루션이 주류를 이루고 있는 이유를 여실히 보여줍니다. 서비스 부문은 현재 규모가 작지만, 은행들이 복잡한 GenAI 파이프라인 구축이나 하루 234건에 달하는 규제 통지의 급증에 대응할 수 있도록 지원해 줄 자문 파트너를 찾음에 따라 2031년까지 연평균 성장률(CAGR) 27.95%로 성장할 것으로 예측됩니다.
컨설팅 기업은 규정 준수 의무를 모델 설계에 반영하도록 지원함으로써 가치 실현까지 걸리는 시간을 단축하고 있습니다. 이러한 수요로 인해 전문 시스템 통합 업체들은 매우 바쁜 상황을 맞이하고 있으며, 서비스 수수료는 예측 가능한 수입원으로 자리 잡고 있습니다. 서비스에 대한 전문 지식이 확산됨에 따라 과거에는 사내 기술 부족을 이유로 AI 도입을 미루던 중견 기업도 시장에 진입하기 시작하면서 핀테크 시장내 AI의 고객 기반이 확대되고 있습니다.
2025년에는 방대한 거래량을 처리하는 탄력적인 컴퓨팅 능력을 바탕으로 클라우드 환경이 도입 수익의 81.35%를 차지했습니다. JP 모건 체이스의 아키텍처에서는 애플리케이션의 70%가 퍼블릭 클라우드에 있으며, 기밀성이 높은 워크로드는 20억 달러 규모의 프라이빗 시설에 배치되어 있습니다. 규제 당국이 데이터 상주 규정을 강화하고 은행들이 단일 공급업체의 장애로 인한 위험을 완화하려는 가운데, 하이브리드 도입은 연평균 성장률(CAGR) 27.4%로 확대될 것으로 예측됩니다.
하이브리드 모델은 주권 보장을 위해 훈련 파이프라인을 온프레미스에 배치하는 한편, 추론 처리는 클라우드에서 실행함으로써 양쪽의 장점을 최대한 활용합니다. 이러한 유연성 덕분에, 특히 엄격한 데이터 현지화 규정을 시행하고 있는 관할권에서 하이브리드는 지속가능한 대안으로 자리매김하고 있습니다.
지역별 분석
북미는 2025년에 매출 점유율의 37.60%를 차지하며, 성숙한 금융 스택과 명확하지만 단편적인 규제 지침에 힘입고 있습니다. JPMorgan Chase는 2,000명의 AI 전문가를 보유하고 400건 이상의 사용 사례를 전개하고 있으며, 현지에서의 높은 전문성을 입증하고 있습니다. Neo Financial과 같은 캐나다의 챌린저 뱅크들은 AI를 활용하여 서비스가 미치지 못하는 계층에 접근하고 있으며, 멕시코에서는 금융 포용을 위해 AI를 활용하고 있습니다. 민관 차원의 지속적인 투자를 통해 북미는 혁신의 실험장으로서의 위상을 유지하고 있으며, 전 세계의 베스트 프랙티스를 핀테크 AI 시장에 환원하고 있습니다.
아시아태평양은 2031년까지 33.1%라는 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예측됩니다. 중국은 2024년에 생성형 AI에 21억 달러를 투자했으며, 기업내 활용률은 83%에 달해 서구 국가의 보급률을 훨씬 웃돌고 있습니다. 인도와 일본은 AI 엔진에 의존하는 포용적 신용 및 정량 거래 데스크를 통해 그 성장세를 확대하고 있습니다. 이 지역의 핀테크 매출은 2021년 2,450억 달러에서 2030년까지 1조 5,000억 달러로 확대될 가능성이 있으며, 은행의 87%가 핀테크 기업과의 제휴를 계획하고 있습니다. 싱가포르는 모바일 결제 분야에서 선도적인 위치를 차지하고 있는 반면, 호주와 뉴질랜드는 GDP 대비 불균형적으로 큰 규모의 AI를 통한 가치 창출이 예상됩니다.
유럽에서는 규정 준수 부담으로 인해 AI 도입이 견고하지만 다소 억제되고 있습니다. EU의 AI 법은 거버넌스 비용을 증가시키지만, 윤리적인 도입을 보장하는 위험 계층 제도를 도입하고 있습니다. 영국에서는 생성형 AI 이용률이 70%에 달하며, 브렉시트 이후의 유연성을 활용하여 은행용 샌드박스를 맞춤형으로 구축하고 있습니다. 독일과 프랑스는 국내 주요 기업내 AI 우수 센터에 자금을 지원하고 있으며, 북유럽 국가들에서는 그린 파이낸스 평가 체계의 시험 운영이 진행되고 있습니다. 동유럽 시장에서는 국경을 넘는 임금 송금에 AI를 활용하는 시도가 이루어지고 있으며, 기존 서비스의 경계가 재정의되고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.07According to Mordor Intelligence, the AI in Fintech market size was valued at USD 30 billion in 2025 and estimated to grow from USD 36.61 billion in 2026 to reach USD 99.09 billion by 2031, at a CAGR of 22.04% during the forecast period (2026-2031).
[1] Microsoft, "How Azure AI is redefining financial services productivity," microsoft.com Growth is being propelled by open-banking mandates that liberate granular customer data, the maturation of real-time payment rails, and cloud-native AI platforms that trim operating costs for mid-tier banks. [2] IBM, "Generative AI in financial services: Accelerating risk model deployment," ibm.com Generative AI copilots are compressing model-risk-management timelines from months to days, letting institutions release compliant risk models at unprecedented speed. This report is Segmented by Type (Solutions and Services), Deployment (Cloud and On-Premise), Application (Fraud and Risk Management, Chatbots and Virtual Assistants, and More), Organization Size (Large Enterprises and SMEs and Neo-Banks), End-User (Retail Banking, Insurance, and More), and Geography.
Global AI In Fintech Market Trends and Insights
Open Banking Mandates Accelerating AI-Led Process Automation
Mandatory data-sharing rules such as PSD3 grant AI engines consistent, permissioned access to multi-institution bank records, enabling real-time credit scoring and hyper-personalized offers. PSD3 went live in 2024, prompting European banks to redesign product origination workflows around API-first architectures that feed machine-learning models with previously siloed datasets. Mid-tier institutions gain competitive parity because compliance investments double as innovation enablers, turning regulatory cost into revenue growth levers. Markets where open-banking adoption exceeds 87% of institutions already display elevated AI service penetration.
Explosion of Real-Time Payments Data Streams
VisaNet +AI processes each authorization with 98% stability prediction accuracy, while its Smarter Settlement Forecast adds seven-day cash-flow projections that shrink liquidity buffers. Real-time rails broadcast behavioral signals that batch systems miss, letting AI flag fraud milliseconds after initiation . Surveys show 94% of payments professionals view AI as indispensable for fraud mitigation, and 77% of consumers expect institutions to deploy it. BNY Mellon automated 90% of back-office payment instruction handling, freeing analysts for value-added tasks. Instant data availability also powers live credit decisions based on dynamic cash-flow metrics.
Shortage of Domain-Specific AI Talent
Demand for professionals who blend machine-learning mastery with regulatory fluency exceeds supply by 2-4 times, with 74% of employers reporting hiring struggles. European banks note that only 25% have formal GenAI training pipelines, widening capability gaps. Salary premiums of 40-60% over traditional finance roles tilt the playing field toward tech giants and tier-one banks. Mid-tier firms risk stalled deployments as talent scarcity inflates project timelines and costs.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-Native AI Platforms Lowering TCO for Mid-Tier Financial Institutions
- GenAI Copilots Slashing Model-Risk-Management Cycle Times
- Fragmented Regulatory Guidance on AI Model Governance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions generated USD 21.44 billion in 2025, equal to 71.45% of the AI in Fintech market. Enterprises favor platforms that unify fraud analytics, customer support, and governance within a single control plane. FICO's blockchain-enabled governance suite, which won a 2025 innovation award, illustrates why integrated offerings dominate. The services segment is smaller today but is projected to grow at 27.95% CAGR through 2031 as banks seek advisory partners to configure complex GenAI pipelines and manage the daily swell of 234 regulatory notices.
Consultancies help translate compliance obligations into model design, accelerating time to value. This demand keeps specialized system integrators busy and cements service fees as a predictable revenue stream. As service expertise proliferates, mid-tier firms that once delayed AI adoption due to limited internal skill sets now jump in, broadening the AI in Fintech market customer base.
Cloud environments delivered 81.35% of deployment revenues in 2025 on the back of elastic compute that processes massive transaction volumes. JPMorgan Chase's architecture shows 70% of applications in public cloud while sensitive workloads reside in USD 2 billion private facilities. Hybrid deployments are forecast to advance at 27.4% CAGR as regulators tighten residency rules and banks look to limit exposure to single-vendor outages.
Hybrid models place training pipelines on-premise for sovereignty yet run inference in cloud, unlocking the best of both worlds. This flexibility positions hybrid as a durable choice, particularly in jurisdictions enforcing strict data localization.
Complete Report Scope:
- By Component
- Solutions
- Services
- By Deployment Mode
- Cloud
- On-premise
- By Application
- Fraud and Risk Management
- Chatbots and Virtual Assistants
- Credit Scoring and Underwriting
- Quantitative and Asset Management
- RegTech and Compliance Analytics
- Others
- By Organization Size
- Large Enterprises
- SMEs and Neo-banks
- By End-user
- Retail Banking
- Insurance
- Investment and Wealth Management
- Payments and Remittances Providers
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Singapore
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 37.60% revenue share in 2025, supported by a mature financial stack and clear though fragmented regulatory guidance. JPMorgan Chase fields 2,000 AI specialists and over 400 live use cases, underscoring local skill depth. Canada's challenger banks such as Neo Financial scale AI to underserved segments, and Mexico leverages AI for financial inclusion. Continued public-private investment sustains North America as an innovation laboratory, feeding global best practices back into the AI in Fintech market.
Asia-Pacific is projected to register the fastest 33.1% CAGR through 2031. China poured USD 2.1 billion into generative AI in 2024 and records 83% enterprise usage, dwarfing western penetration rates. India and Japan extend momentum through inclusive credit and quantitative trading desks that rely on AI engines. The region's fintech revenue could move from USD 245 billion in 2021 to USD 1.5 trillion by 2030, with 87% of banks planning fintech partnerships. Singapore leads in mobile payments, while Australia and New Zealand expect disproportionate AI value capture relative to GDP.
Europe demonstrates strong adoption tempered by compliance overhead. The EU AI Act imposes a risk-tier system that elevates governance costs but assures ethical deployment. The UK reports 70% GenAI usage, leveraging post-Brexit agility to tailor banking sandboxes. Germany and France fund AI centers of excellence inside national champions, and the Nordics pilot green-finance scoring frameworks. Eastern markets experiment with AI for cross-border wage remittances, redrawing traditional service boundaries.
- Amazon Web Services, Inc.
- Microsoft Corporation
- International Business Machines Corporation
- Google LLC (Alphabet Inc.)
- Fair Isaac Corporation
- SAS Institute Inc.
- Intel Corporation
- NVIDIA Corporation
- Salesforce, Inc.
- Stripe, Inc.
- Plaid Inc.
- ComplyAdvantage Ltd.
- Onfido Ltd.
- Ripple Labs Inc.
- DataRobot, Inc.
- Upstart Holdings, Inc.
- ZestFinance, Inc.
- Darktrace Limited
- Truera, Inc.
- Active Intelligence Pte Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Open banking mandates accelerating AI-led process automation
- 4.2.2 Explosion of real-time payments data streams
- 4.2.3 Cloud-native AI platforms lowering TCO for mid-tier FIs
- 4.2.4 GenAI copilots slashing model-risk-management cycle-times
- 4.2.5 AI-powered ESG scoring unlocking green-finance incentives
- 4.3 Market Restraints
- 4.3.1 Shortage of domain-specific AI talent
- 4.3.2 Fragmented regulatory guidance on AI model governance
- 4.3.3 Rising GPU supply-chain volatility inflating inference costs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-premise
- 5.3 By Application
- 5.3.1 Fraud and Risk Management
- 5.3.2 Chatbots and Virtual Assistants
- 5.3.3 Credit Scoring and Underwriting
- 5.3.4 Quantitative and Asset Management
- 5.3.5 RegTech and Compliance Analytics
- 5.3.6 Others
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 SMEs and Neo-banks
- 5.5 By End-user
- 5.5.1 Retail Banking
- 5.5.2 Insurance
- 5.5.3 Investment and Wealth Management
- 5.5.4 Payments and Remittances Providers
- 5.5.5 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Malaysia
- 5.6.4.6 Singapore
- 5.6.4.7 Australia
- 5.6.4.8 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 International Business Machines Corporation
- 6.4.4 Google LLC (Alphabet Inc.)
- 6.4.5 Fair Isaac Corporation
- 6.4.6 SAS Institute Inc.
- 6.4.7 Intel Corporation
- 6.4.8 NVIDIA Corporation
- 6.4.9 Salesforce, Inc.
- 6.4.10 Stripe, Inc.
- 6.4.11 Plaid Inc.
- 6.4.12 ComplyAdvantage Ltd.
- 6.4.13 Onfido Ltd.
- 6.4.14 Ripple Labs Inc.
- 6.4.15 DataRobot, Inc.
- 6.4.16 Upstart Holdings, Inc.
- 6.4.17 ZestFinance, Inc.
- 6.4.18 Darktrace Limited
- 6.4.19 Truera, Inc.
- 6.4.20 Active Intelligence Pte Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment