

|
시장보고서
상품코드
2122435
반사 방지 코팅 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Anti-Reflective Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
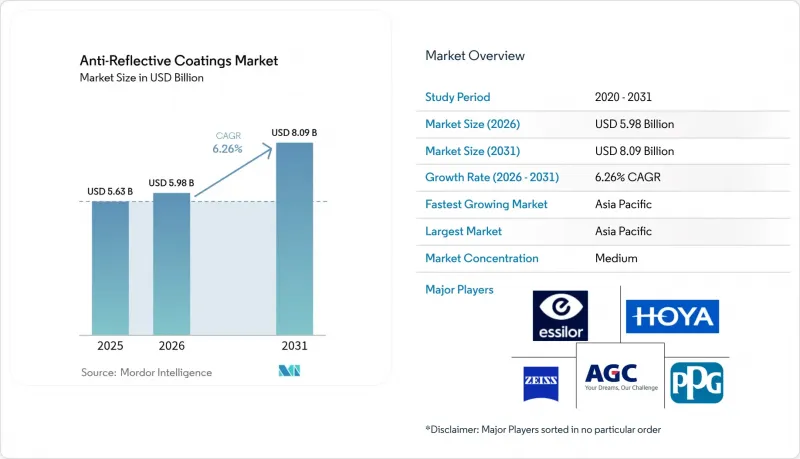
에 의하면, 반사 방지 코팅 시장 규모는 2025년에 56억 3,000만 달러로 평가되었고, 2026년59억 8,000만 달러에서 2031년까지 80억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 6.26%를 기록할 전망입니다.
본 보고서는 성막 방법(화학 기상 증착법, 전자빔 성막법, 스퍼터링, 기타 성막 방법), 용도(반도체, 전자기기, 안경, 태양전지 패널 등), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러) 단위로 표시되어 있습니다.
세계 반사 방지 코팅 시장 동향 및 인사이트
AR/VR 및 스마트 글래스의 보급이 정밀 광학 기기 수요를 견인
2024년에는 헤드셋 출하 대수가 960만 대에 달할 것으로 예상되며, 교육 및 원격 협업과 같은 기업용 이용 사례로 인해 대상 고객 기반이 확대되고 있습니다. 현재 광학 스택에는 색 재현성과 내스크래치성을 유지하면서 가시광선 스펙트럼 전체에서 평균 반사율을 1% 미만으로 억제하는 것이 요구되고 있습니다. 저장대학교 연구진은 반사율이 1% 미만이고 경도가 15GPa를 초과하는 다층 졸-겔 스택을 보고하며, 소비자용 웨어러블 기기에 적합한 내구성을 입증했습니다. 파도 결합기나 팬케이크 렌즈의 경우, 각도에 따른 고스트 현상을 억제해야 하므로, 서브나노미터 단위로 층 두께를 조정할 수 있는 코팅 제조업체들이 고부가가치 수주를 확보하고 있습니다. 컨텐츠 제공업체들이 공간 컴퓨팅에 최적화를 추진하는 가운데, 헤드셋 OEM 제조업체들은 땀, 온도 변화, 잦은 세척을 견딜 수 있는 광대역이며 산란이 적은 코팅을 지정하고 있어, 이에 따라 고성능 반사 방지 코팅제에 대한 지속적인 수요가 발생하고 있습니다.
자율주행차의 지각을 가능하게 하는 LiDAR 광학 시스템
905 nm 및 940 nm에서 작동하는 자동차용 LiDAR 모듈은 저반사율 송수신 광학계를 채택함으로써 감지 범위를 200 m 이상으로 확대되고 있습니다. 『Nature Communications』지의 연구에 따르면, 6,000시간의 고온 시험을 견뎌낸 6접합 반사 방지 스택을 갖춘 수직 공진기 레이저가 400 W의 피크 출력을 달성할 수 있음이 입증되었습니다. 시스템 가격이 100달러라는 목표를 향해 하락하는 가운데, Tier 1 공급업체들은 IATF 16949 감사를 통과하면서도 신호 대 잡음비(SNR)를 향상시키는 코팅을 요구하고 있습니다. 인증 여부는 -40°C-+105°C의 온도 범위에서 성능을 유지할 수 있는지, 그리고 도로용 소금에 의한 부식을 견딜 수 있는지에 달려 있습니다. 굴절률 및 두께 균일성 측면에서 로트 간 편차가 적음을 입증할 수 있는 공급업체는 2026년부터 2027년까지 예정된 플랫폼 구축 과정에서 우선 공급업체로서의 지위를 확보하게 될 것입니다.
높은 생산 비용과 설비 비용이 진입 장벽으로 작용
전자빔 증착 장비, 마그네트론 스퍼터링 챔버, 플라즈마 리액터는 각각 100만 달러 이상의 비용이 소요되며, 클래스 100 청정실 시설이 필요합니다. 소규모 코팅 제조업체들은 설비 투자 상각에 어려움을 겪고 있으며, 그 결과 중국, 한국, 미국의 메가팹을 중심으로 한 업계 재편이 진행되고 있습니다. 정기 유지보수로 인해 생산량이 중단될 뿐만 아니라, 숙련된 기술자에게는 고액의 임금이 지급되기 때문에 고정비가 더욱 치솟고 있습니다. 이러한 경제적 요인으로 인해 OEM 제조업체가 동남아시아나 라틴아메리카에서의 현지 조달을 원하더라도 지리적 분산은 저해되고, 기존 거점의 우위성이 더욱 강화되고 있습니다.
부문 분석
스퍼터링은 2026-2031년 연평균 성장률(CAGR) 6.47%를 기록하며, 반사 방지 코팅 시장 전체를 상회하는 성장률을 보였습니다. 마그네트론 방식은 Gen 8.7 유리 상에서 분당 10nm를 초과하는 고밀도 박막을 증착할 수 있어, 디스플레이 및 태양광 발전용 팹의 턱트 타임을 단축하고 있습니다. 화학 기상 증착(CVD)을 이용한 반사 방지 코팅 시장 점유율은 2025년에도 29.10%를 유지했습니다. 이는 뛰어난 컨포멀리티가 광섬유 프리폼 및 MEMS 캐비티에 필수적이기 때문입니다. 현재 하이브리드 생산 라인에서는 3차원 형상의 코팅에는 플라즈마 강화 화학 기상 증착(PECVD)을, 평면 패널에는 스퍼터링 소스를 조합함으로써 장비의 가동률을 극대화하고 있습니다. 이온 빔 스퍼터링은 속도는 느리지만, 193 nm 리소그래피에 사용되는 레티클 블랭크에 필수적인 원자 수준의 평탄도를 실현합니다. 이 공정에서는 정재파 결함을 방지하기 위해 잔류 반사율이 0.2% 미만이어야 합니다. 공정 선정은 기판의 열 예산이나 플라즈마 노출 허용 여부에 점점 더 좌우되고 있으며, 각 팹 업체들은 위험을 분산하기 위해 여러 제조 레시피를 병행하고 있습니다.
스퍼터링의 확대는 경질 유리가 아닌 폭 300mm의 폴리머 필름 롤을 지정하는 플렉서블 디스플레이 프로젝트에 의해서도 추진되고 있습니다. 롤 투 롤 스퍼터링 라인의 회전식 타겟을 통해 가동 중에 조성을 전환할 수 있게 되어, 광대역 성능과 기계적 내구성의 균형을 맞추는 굴절률 구배 스택을 구현할 수 있습니다. 한편, 열에 민감한 폴리머로 성형되는 자동차용 LiDAR 렌즈 분야에서는 플라즈마 조사로 인해 광학 형상이 왜곡될 우려가 있어, 화학 기상 증착(CVD)의 점유율이 확대되고 있습니다. 각 벤더사는 스퍼터링용 음극의 업그레이드를 통해 출력 밀도가 15% 향상될 것으로 전망하며, 그 결과 타겟 끝부분의 데드존이 얇아지고 재료 이용률이 향상됨에 따라 1제곱미터당 코팅 비용이 더욱 절감될 것으로 예상하고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 34.10%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 7.62%로 성장이 가속화될 것으로 전망되는데, 이는 반사 방지 코팅 시장의 평균 성장률을 상회하는 속도입니다. 중국 광둥성과 장쑤성에 위치한 10.5세대 LCD 및 OLED 제조 공장은 대면적 스퍼터링 타겟 수요를 집중시키고 있는 반면, 한국의 프리미엄 스마트폰 패널 제조업체들은 극히 낮은 불량률을 요구하고 있습니다. 일본의 광학 유리 제조 전통은 카메라 모듈 및 안경용 코팅 수요를 뒷받침하고 있으며, 인도의 태양전지 조립 붐은 양면 코팅 유리 수요를 끌어올리고 있습니다. 현지 조달률에 관한 규제로 인해 다국적 공급업체들은 베트남이나 말레이시아 인근에 스퍼터링 생산 라인을 설치하도록 장려받고 있지만, 높은 자본 집약도가 여전히 장벽으로 작용하고 있습니다.
북미는 생산량은 적지만, 항공우주 및 방위 프로그램에서 저산란·광대역 적층막과 치밀한 추적성이 요구되기 때문에 평균 판매 가격이 높습니다. 실리콘 밸리의 AR 헤드셋 개발 기업들은 포토마스크를 사용하여 패턴별로 특정 코팅을 적용해야 하는 단기 생산 로트를 위탁하고 있으며, 이 분야에서는 기동성이 뛰어난 미국의 코팅 제조업체들이 우위를 유지하고 있습니다. 멕시코는 자동차 조립 공장과 가까운 지리적 이점을 활용하고 있지만, 확립된 생산 규모로 인해 대면적 코팅의 대부분은 여전히 아시아에서 출하되고 있습니다. 캐나다 수요는 광업 및 임업 자동화를 위한 LiDAR 센서에 집중되어 있지만, 절대적인 수량은 여전히 소규모에 그치고 있습니다.
유럽 시장은 REACH 규제의 영향을 받고 있으며, 이 규제로 인해 코팅 배합 업체들은 다른 지역보다 앞서 PFAS가 포함되지 않은 대체재의 인증을 획득해야만 합니다. 독일의 고급차 제조업체들은 편광 제어 기능이 통합된 헤드업 디스플레이용 반사 방지 유리를 지정하며 성능 기준을 높이고 있습니다. 스페인과 그리스의 대규모 태양광 발전 시설에서는 양면 수광형 모듈이 점차 채택되고 있지만, 코팅 유리의 상당 부분은 여전히 아시아에서 조달되고 있어 EU는 2027년까지 공급의 현지화를 도모하기 위한 노력을 추진하고 있습니다. 동유럽의 폴란드와 체코 공화국에 위치한 광학 산업 클러스터는 방위용 렌즈를 전문으로 하며, 규모는 작지만 안정적인 수요 기반을 제공합니다.
중동 및 아프리카은 여전히 발전 단계에 있습니다. 사우디아라비아의 기가와트급 태양광 발전 입찰과 남아프리카공화국의 광산용 헬멧 바이저 업그레이드가 주요 촉진요인이지만, 클린룸 인프라가 제한적이어서 일반적으로 수입에 의존하고 있습니다. 라틴아메리카에서는 성장세가 가속화되고 있습니다. 브라질과 칠레는 태양광 발전 용량을 확대하고 있으며, 일사량이 많은 지역에서의 발전 효율을 높이기 위해 반사 방지 유리를 지정하고 있지만, 코팅 가공은 여전히 해외에서 이루어지고 있어 안정적인 수주 파이프라인이 구축된다면 지역 내 투자 여지가 남아 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, the anti-reflective coatings market size was valued at USD 5.63 billion in 2025 and estimated to grow from USD 5.98 billion in 2026 to reach USD 8.09 billion by 2031, at a CAGR of 6.26% during the forecast period (2026-2031).
This report is Segmented by Deposition Method (Chemical Vapour Deposition, Electronic Beam Deposition, Sputtering, and Other Deposition Methods), Application (Semiconductors, Electronic Devices, Eyewear, Solar Panels, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Anti-Reflective Coatings Market Trends and Insights
AR/VR and Smart-Glass Adoption Driving Precision Optics Demand
Headset shipments reached 9.6 million units in 2024, and enterprise use cases, including training and remote collaboration, are broadening the addressable customer base. Optical stacks must now deliver average reflectance below 1% across the visible spectrum while maintaining color fidelity and scratch resistance. Zhejiang University researchers reported multilayer sol-gel stacks with a reflectance of less than 1% and a hardness exceeding 15 GPa, demonstrating durability suitable for consumer wearables. Coating houses capable of tuning layer thickness in sub-nanometer steps are winning premium contracts, because waveguide combiners and pancake lenses require angle-specific suppression of ghost images. As content providers optimize for spatial computing, headset OEMs specify broadband, low-scatter coatings that withstand perspiration, temperature cycling, and frequent cleaning, creating a sustained demand for high-performance anti-reflective formulations.
LiDAR Optics Enabling Autonomous-Vehicle Perception
Automotive LiDAR modules operating at 905 nm and 940 nm utilize low-reflectance transmit and receive optics to extend their detection ranges beyond 200 m. A Nature Communications study demonstrated that vertical-cavity lasers can reach a peak output of 400 W with six-junction anti-reflective stacks that have survived 6,000 hours of high-temperature testing. As system prices drop toward the USD 100 target, Tier 1 suppliers demand coatings that boost signal-to-noise while passing IATF 16949 audits. Qualification hinges on sustaining performance between -40 °C and +105 °C, as well as withstanding road-salt corrosion. Vendors that can document low lot-to-lot variation in refractive index and thickness uniformity gain preferred-supplier status during platform rollouts scheduled for 2026-2027.
High Production and Equipment Cost Constraining Entry
Electron-beam evaporators, magnetron sputtering chambers, and plasma reactors each cost upwards of USD 1 million and require Class 100 cleanroom facilities. Smaller coaters struggle to amortize capital outlays, driving consolidation around mega-fabs in China, South Korea, and the United States. Scheduled maintenance interrupts throughput, and skilled technicians command premium wages, further elevating fixed costs. The economics deter geographic diversification even when OEMs request local supply in Southeast Asia or Latin America, reinforcing the dominance of incumbent hubs.
Other drivers and restraints analyzed in the detailed report include:
- Solar PV Installations Amplifying Efficiency Gains
- Surge in High-Resolution Consumer Displays
- REACH and Fluorochemicals Regulation Forcing Reformulation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sputtering posted a 6.47% CAGR between 2026 and 2031, faster than the overall anti-reflective coatings market. Magnetron architectures deposit dense films at >10 nm per minute across Gen 8.7 glass, cutting takt time for display and photovoltaic fabs. The anti-reflective coatings market share for chemical vapor deposition remained 29.10% in 2025 because its superior conformality is indispensable for fiber-optic preforms and MEMS cavities. Hybrid production lines now combine plasma-enhanced chemical-vapor deposition for coverage on 3-D geometries with sputter sources for planar panels, maximizing equipment utilization. Ion-beam sputtering, though slower, enables atomic-scale smoothness essential for reticle blanks used in 193-nm lithography, where <0.2% residual reflectance prevents standing-wave defects. Process selection increasingly hinges on substrate thermal budget and whether plasma exposure is acceptable, prompting fabs to dual-source recipes to hedge risk.
Sputtering's expansion is also driven by flexible-display programs that specify 300 mm-wide rolls of polymer film rather than rigid glass. Rotatable targets in roll-to-roll sputtering lines enable the switch in composition mid-run, allowing for graded-index stacks that balance broadband performance with mechanical resilience. Conversely, chemical vapor deposition gains share in automotive lidar lenses molded from heat-sensitive polymers, where plasma bombardment would warp the optical figure. Capital-equipment vendors forecast sputter cathode upgrades that increase power density by 15%, resulting in thinner dead zones at target ends and improved material utilization, which further reduces per-square-meter coating cost.
Complete Report Scope:
- By Deposition Method
- Chemical Vapour Deposition
- Electronic Beam Deposition
- Sputtering
- Other Deposition Methods
- By Application
- Semiconductors
- Electronic Devices
- Eyewear
- Solar Panels
- Automotive Displays
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
The Asia-Pacific region generated 34.10% of global revenue in 2025 and is projected to accelerate at a 7.62% CAGR through 2031, outpacing the average growth rate of the anti-reflective coatings market. China's Gen 10.5 LCD and OLED fabs in Guangdong and Jiangsu concentrate demand for large-area sputtering targets, while South Korea's premium smartphone-panel makers dictate ultralow-defect requirements. Japan's optical-glass heritage supports demand for camera-module and eyewear coatings, and India's solar assembly boom adds dual-sided coated glass volumes. Local content rules are nudging multinational vendors to site sputter lines near Vietnam and Malaysia, even though capital intensity remains a barrier.
North America captures a smaller volume but commands higher average selling prices because aerospace and defense programs specify low-scatter, broadband stacks and meticulous traceability. Silicon Valley's AR headset developers contract for brief production runs that require pattern-specific coatings applied with photomasks, an area where nimble U.S. coaters maintain an edge. Mexico benefits from its proximity to automotive assembly, but most large-area coatings still ship from Asia due to the established scale. Canada's demand centers on lidar sensors for mining and forestry automation, though absolute volumes remain modest.
Europe's market is shaped by REACH regulation, which is forcing coating formulators to qualify PFAS-free alternatives ahead of other regions. Germany's premium vehicle makers specify anti-reflective glass for head-up displays that integrate polarization control, raising the performance bar. Utility-scale solar in Spain and Greece is adopting bifacial modules, yet much of the coated glass still arrives from Asia, prompting EU initiatives to localize supply by 2027. Eastern Europe's optics clusters in Poland and the Czech Republic specialize in defense lenses, providing a small but stable demand base.
Middle East and Africa remain nascent: Saudi Arabia's gigawatt solar tenders and South Africa's mining-helmet visor upgrades are the primary drivers, usually served through imports given the limited cleanroom infrastructure. Latin America is gathering momentum-Brazil and Chile are expanding solar capacity and specifying anti-reflective glass to lift yield in high-irradiance zones-yet coating application still occurs offshore, leaving room for regional investments should consistent order pipelines materialize.
- AccuCoat Inc.
- AGC Inc.
- COCO LENI
- DuPont
- Edmund Optics Inc.
- EKSMA Optics USB
- EssilorLuxottica
- Evaporated Coatings Inc.
- Honeywell International Inc.
- HOYA VISION CARE COMPANY (HOYA Corporation)
- Majestic Optical Coatings
- Optical Coatings Japan
- Optics Balzers AG
- Optimum RX Group
- PPG Industries
- Quantum Coating
- Spectrum Direct Ltd
- Torr Scientific Ltd
- Viavi Solutions
- Zeiss International
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Augmented Reality(AR)/Virtual Rality(VR) and smart-glass adoption
- 4.2.2 LiDAR optics in autonomous vehicles
- 4.2.3 Rising demand from solar PV installations
- 4.2.4 Growth in ophthalmic eyewear prescriptions
- 4.2.5 Surge in high-resolution consumer displays
- 4.3 Market Restraints
- 4.3.1 High production and equipment cost
- 4.3.2 Stringent REACH and fluorochemicals regulation
- 4.3.3 Durability issues on flexible polymer substrates
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Deposition Method
- 5.1.1 Chemical Vapour Deposition
- 5.1.2 Electronic Beam Deposition
- 5.1.3 Sputtering
- 5.1.4 Other Deposition Methods
- 5.2 By Application
- 5.2.1 Semiconductors
- 5.2.2 Electronic Devices
- 5.2.3 Eyewear
- 5.2.4 Solar Panels
- 5.2.5 Automotive Displays
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 NORDIC Countries
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AccuCoat Inc.
- 6.4.2 AGC Inc.
- 6.4.3 COCO LENI
- 6.4.4 DuPont
- 6.4.5 Edmund Optics Inc.
- 6.4.6 EKSMA Optics USB
- 6.4.7 EssilorLuxottica
- 6.4.8 Evaporated Coatings Inc.
- 6.4.9 Honeywell International Inc.
- 6.4.10 HOYA VISION CARE COMPANY (HOYA Corporation)
- 6.4.11 Majestic Optical Coatings
- 6.4.12 Optical Coatings Japan
- 6.4.13 Optics Balzers AG
- 6.4.14 Optimum RX Group
- 6.4.15 PPG Industries
- 6.4.16 Quantum Coating
- 6.4.17 Spectrum Direct Ltd
- 6.4.18 Torr Scientific Ltd
- 6.4.19 Viavi Solutions
- 6.4.20 Zeiss International
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


