|
시장보고서
상품코드
2122447
군용 광섬유 케이블 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Military Fiber Optic Cables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
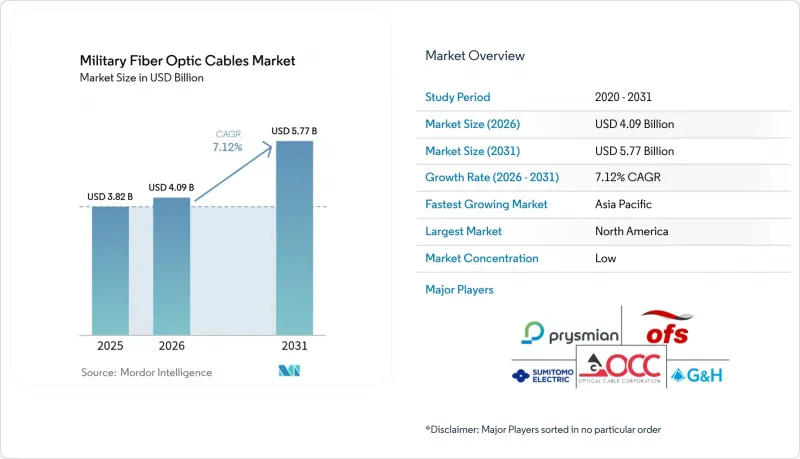
에 의하면, 2026년 군용 광섬유 케이블 시장 규모는 40억 9,000만 달러로 추정되며, 2025년 38억 2,000만 달러에서 2031년에는 57억 7,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 7.12%를 기록할 전망입니다.
본 보고서는 케이블 유형(싱글모드 및 멀티모드), 재질(유리 광섬유 등), 구축 플랫폼(지상 시스템 등), 설치 환경(전술적 야외 구축형 등), 용도(레이더 및 전자전 등), 지역(북미, 유럽 등)별로 세분화되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 군용 광섬유 케이블 시장 동향 및 인사이트
손실이 없고 전자기 간섭(EMI)의 영향을 받지 않는 데이터 링크에 대한 전장 수요
전자전이 현대 전장에 확산됨에 따라, 재밍 상황에서도 신호가 손상되지 않도록 광섬유 회선이 구리선을 대체하고 있습니다. 우크라이나군은 간섭의 영향을 받지 않고 고해상도 영상을 스트리밍하면서 41km 거리를 비행하는 광섬유 연결 FPV 드론을 운용하고 있습니다. 나토(NATO) 계획 담당자들은 이러한 성과를 주시하고 있으며, 미 육군은 능력 격차를 해소하기 위해 유사한 시스템 1,100대를 도입할 계획입니다. 이러한 실전에서 입증된 기술의 보급으로 인해 분대 및 지휘소를 위한 견고한 마이크로 광섬유 릴과 신속 전개형 커넥터의 조달이 가속화되고 있습니다. 각 드론에는 MIL 규격의 인장 강도 및 굽힘 한계를 충족해야 하는 수 킬로미터 규모의 스풀과 교체 키트가 사용되기 때문에 군용 광섬유 케이블 시장은 직접적인 수혜를 입고 있습니다. 전자 공격으로부터 전방 기지를 견고하게 방어하려는 각국의 정책으로 인해 수요는 더욱 촉진되고 있습니다.
5G 전술 네트워크의 군사화
미국, 스페인, 독일, 노르웨이의 각 기지에서 민간 5G를 구축하는 데는 엄격한 지연 및 보안 목표를 충족하면서 멀티 기가비트급 트래픽을 처리할 수 있는 고밀도 광섬유 백홀에 의존하고 있습니다. 2024년부터 2027년에 걸쳐 국방용 5G 인프라에 대한 총 지출액은 15억 달러에 달할 것으로 예상되며, 그 중 약 3분의 1이 광케이블 및 종단 장비에 할당될 전망입니다. 각 프로그램에서는 Open RAN 인터페이스가 채택되고 있으므로, 공급업체는 다양한 무선 장치 및 엣지 클라우드를 지원하는 광섬유 인증을 취득해야 합니다. 그 결과, 군용 광섬유 케이블 시장에서는 단일 모드 간선, 현장 배치 가능한 실내·실외용 패치 코드, 그리고 연료 유출이나 차량 하중을 견딜 수 있는 견고한 MPO 커넥터에 대한 지속적인 수주가 예상됩니다.
현장 수리의 복잡성
외딴 전투 지역에서 광섬유 연결 작업은 많은 노력과 도구가 필요하기 때문에 회선이 끊어지면 중요한 센서가 작동을 멈출 우려가 있습니다. 군 당국의 시험에서는 3분 이내에 설치 가능한 ‘크림프 앤 클리브(crimp & cleave)’ 방식의 커넥터가 채택되어, 0.5dB의 추가 손실을 허용하는 대신 신속한 복구를 실현하고 있습니다. 훈련 지연이 여전히 지속되고 있으며, 인증 기술자 부족으로 인해 대규모 배치가 지연되고 있습니다. 이에 대응해 각 공급업체는 인적 오류를 줄이기 위해 사전 종단 처리가 완료된 릴과 색상으로 구분된 부츠를 제공합니다. 이러한 발전으로 문제는 완화되고 있지만, 군용 광섬유 케이블 시장에서는 각 군이 충분한 유지보수 팀을 배치할 때까지 계약 지연이 여전히 우려되고 있습니다.
부문 분석
싱글 모드 회선은 2025년 군용 광섬유 케이블 시장에서 최대 점유율(약 54.02%)을 차지할 것으로 보이며, 2031년까지 한 자릿수 중반의 연평균 성장률(CAGR)을 유지할 것으로 예측됩니다. 가느다란 코어 덕분에 구축함, 공중 조기 경보기 및 전방 작전 기지를 상호 연결하는 지하 광섬유 간선에서 초장거리 연결이 가능해집니다. 유익한 부수적 효과로, 각 단일 모드 회선에는 예비 다크 파이버가 설치되어 있는 경우가 많으며, 이를 통해 미래를 내다본 투자가 가능한 잠재적 용량이 생겨납니다.
둘째, 멀티모드는 현재 시장 점유율은 작지만, 연평균 성장률(CAGR) 8.43%로 시장 전체의 성장률을 상회할 것으로 예측됩니다. 비용 효율이 뛰어난 트랜시버, 광범위한 발사 조건에 대한 내성, 그리고 내방사선성 멀티모드 광섬유의 최근 기술적 진보로 인해 장갑차 및 항공기 내에서의 도입 확대가 예상됩니다. 이러한 증가 추세는 두 가지 코어 유형을 결합한 하이브리드 케이블 번들을 제공하는 공급업체가 통합업체의 물류를 간소화함으로써 상업적 우위를 확보할 수 있음을 시사합니다.
유리 광섬유는 타의 추종을 불허하는 대역폭과 견고성으로 인해 군용 광섬유 케이블 시장의 약 90.10%를 차지하고 있습니다. 조선 엔지니어들은 열 범위가 해양 충격 기준을 충족하기 때문에 갑판 위 및 갑판 아래 배선에 유리 광섬유를 선호합니다. 공급업체에게 있어 장점은 공급량의 안정성입니다. 함대의 개조 주기로 인해 신조선 건조 일정에 좌우되지 않고 지속적인 수요가 보장됩니다.
플라스틱 광섬유(POF) 시장 점유율은 10분의 1 미만에 그치지만, 유연성과 현장에서의 신속한 종단 처리가 가능하다는 점 덕분에 연평균 성장률(CAGR)은 약 10.02%로 증가하고 있습니다. 베어링이나 해치 씰에 내장된 마모 센서는 틈새 시장이지만 지속적인 수주를 확보하는 좋은 사례입니다. POF의 발전은 자재 포트폴리오를 다각화함으로써, 계약업체가 유리 특유의 지정학적 공급 위험에 대한 헤지를 도모할 수 있음을 시사합니다.
지역별 분석
북미는 지속적인 국방 예산과 기술적 리더십 덕분에 2025년 매출의 34.10%를 차지했습니다. 1,100대 규모의 광섬유 드론 도입과 같은 프로그램은 성능이 입증될 경우 조달 규모가 얼마나 급속히 확대될 수 있는지를 여실히 보여주고 있습니다. 국립 연구소의 연구에 따르면, 코히런트 결합 레이저와 굽힘에 강하고 견고한 광섬유 개발이 진행되고 있어, 이 지역의 기술적 우위를 공고히 하고 있습니다. 북미의 군용 광섬유 케이블 시장 규모는 각 신규 플랫폼에서 광 백본이 표준화됨에 따라 더욱 확대되고 있습니다.
아시아태평양에서는 인도, 일본, 한국, 호주가 현대화를 가속화하고 있어, 2031년까지 9.05%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다. 인도의 ‘Network For Spectrum’ 계약(총액 2억 700만 달러)은 57,015km에 달하는 광섬유 부설을 포함하고 있습니다. 이 지역의 통신 사업자들은 한 쌍당 18 Tbps의 전송 용량을 가진 ‘ALPHA’ 케이블을 통해 제휴를 맺고 있으며, 해군에 내결함성이 높은 통신 경로를 제공합니다. 각국의 국방부는 고밀도 광 프론트홀이 필요한 5G 지원 훈련장에 투자하고 있습니다. 이러한 노력으로 인해 지역 전체의 군용 광섬유 케이블 시장에 대한 관심이 높아지고 있습니다.
유럽에서는 해저 인프라와 국경을 넘는 육상 경로를 보호하는 NATO 프로젝트를 필두로 견조한 수요가 유지되고 있습니다. ‘발틱 센트리(Baltic Sentinel)’ 작전에서는 해군용 드론을 이용해 파이프라인과 케이블 순찰이 이루어지고 있으며, 이로 인해 내충격성 광섬유 번들의 수주가 촉진되고 있습니다. 스웨덴과 핀란드는 3 Pbps의 전송 용량을 갖춘 7,500만 스웨덴 크로나(780만 달러) 규모의 케이블 3개로 구성된 육상 회랑을 개통하여 지역의 회복탄력성을 강화했습니다. EU군이 공통 아키텍처로의 통합을 추진하는 가운데, 범유럽 인증을 획득한 공급업체들이 군용 광섬유 케이블 시장에서의 점유율을 확대되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, military fiber optic cables market size in 2026 is estimated at USD 4.09 billion, growing from 2025 value of USD 3.82 billion with 2031 projections showing USD 5.77 billion, growing at 7.12% CAGR over 2026-2031.
This report is Segmented by Cable Type (Single-Mode and Multi-Mode), Material Type (Glass Optical Fiber, and More), Deployment Platform (Land Systems, and More), Installation Environment (Tactical Field-Deployable, and More), Application (Radar and Electronic Warfare, and More) and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Military Fiber Optic Cables Market Trends and Insights
Battlefield demand for loss-less, EMI-immune data links
Electronic warfare has saturated modern battlefields, so fiber-optic lines now replace copper to keep signals intact under jamming. Ukrainian forces operate fiber-tethered FPV drones that penetrate 41 km while streaming high-resolution video unaffected by interference. NATO planners observed these results, and the US Army plans 1,100 similar systems to close capability gaps. These combat-proven accelerators accelerate the procurement of rugged micro-fiber reels and quick-deploy connectors for squads and command posts. The military fiber optic cables market benefits directly as each drone uses multi-kilometre spools and replacement kits that must meet MIL-spec pull and bend limits. Demand is reinforced by national mandates to harden forward bases against electronic attack.
Militarisation of 5G tactical networks
Private 5G roll-outs at bases in the United States, Spain, Germany, and Norway depend on dense fiber backhaul that handles multi-gigabit traffic while meeting strict latency and security targets. Spending on defence 5G infrastructure will total USD 1.5 billion during 2024-2027, with roughly one-third flowing to optical cabling and terminations. Programs adopt Open RAN interfaces, so suppliers must certify fibers for diverse radio units and edge clouds. The military fiber optic cables market thus gains sustained orders for single-mode trunk lines, field-deployable indoor/outdoor patch cords, and hardened MPO connectors able to survive fuel spills and vehicle loads.
Field-level repair complexity
Splicing fibers in remote combat zones is labour-intensive and tool-heavy, so cut lines can idle critical sensors. Military trials "crimp & cleave" connectors that install in under three minutes, trading 0.5 dB extra loss for rapid restoration. Training backlogs persist, and shortages of certified technicians slow large-scale roll-outs. Vendors answer with pre-terminated reels and colour-coded boots that reduce human error. While these advances ease the issue, the military fiber optic cables market still faces delayed contracts until armies field enough maintenance teams.
Other drivers and restraints analyzed in the detailed report include:
- Surge in ISR sensor density
- Directed-energy weapons integration
- Supply chain security vulnerabilities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Single-mode lines command the largest military fiber optic cables market share at roughly 54.02% in 2025 and are forecast to maintain a mid-single-digit CAGR through 2031. Their narrow core enables ultra-long links on destroyers, airborne early warning aircraft, and underground fiber trunks interconnecting forward operating bases. A useful consequence is that each single-mode run often carries spare dark fibers, creating latent capacity that future-proofs the investment.
Second, multi-mode occupies a smaller slice today, yet is predicted to outpace overall market growth with an 8.43% CAGR. Cost-effective transceivers, tolerance of wider launch conditions, and recent breakthroughs in radiation-hard multimode fiber suggest wider deployment inside armored vehicles and aircraft cabins. This uptick implies that vendors offering hybrid cable bundles-combining both core types-gain a commercial edge by simplifying logistics for integrators.
Glass commands about 90.10% of the military fiber optic cables market, thanks to its unmatched bandwidth and robustness. Naval architects favour glass for topside and below-decks runs because its thermal window aligns with maritime shock standards. The inferred benefit for suppliers is volume stability: fleet refit cycles assure ongoing demand independent of new-build schedules.
Plastic optical fiber (POF) may hold less than a tenth of the market value, but it is advancing at roughly 10.02% CAGR owing to flexibility and quick field termination. Embedded wear sensors in bearings and hatch seals illustrate niche yet recurring orders. POF's progress suggests that a diversified materials portfolio gives contractors a hedge against glass-specific geopolitical supply risks.
Complete Report Scope:
- By Cable Type
- Single-mode
- Multi-mode
- By Material Type
- Glass Optical Fiber
- Plastic Optical Fiber
- Deployment Platform
- Land Systems
- Airborne Systems
- Naval and Sub-sea Systems
- By Installation Environment
- Tactical Field-Deployable
- Harsh-Environment Armored
- Under-water / Submarine
- By Application
- C3ISR and Tactical Communications
- Radar and Electronic Warfare
- Guided and Directed-Energy Weapons
- On-board Data Networks / Avionics
- Others (Power-over-Fiber, Sensors)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Singapore
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Israel
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 34.10% revenue in 2025 due to sustained defense budgets and technology leadership. Programs such as the 1,100-unit fiber drone rollout highlight how procurement scales quickly once performance is proven. Research at national laboratories advances coherently combined lasers and bend-insensitive, rugged fibers, securing the region's technical edge. The military fiber optic cables market size in North America further widens as each new platform standardises on optical backbones.
Asia-Pacific records the fastest 9.05% CAGR to 2031 as India, Japan, South Korea, and Australia step up modernisation. India's Network For Spectrum contracts worth USD 207 million cover 57,015 km of fiber builds. Regional carriers partner on the ALPHA cable that offers 18 Tbps per pair, giving navies resilient routes. Defense ministries invest in 5G-backed training ranges that depend on dense optical fronthaul. These initiatives raise the military fiber optic cables market profile across the region.
Europe maintains solid demand, led by NATO projects that secure undersea infrastructure and cross-border land routes. The Baltic Sentry mission uses naval drones to patrol pipelines and cables, triggering orders for impact-proof fiber bundles. Sweden and Finland opened a SEK 75 million (USD 7.8 million) three-cable land corridor able to carry 3 Pbps, reinforcing regional resilience. As EU forces converge on common architectures, suppliers with pan-European approvals gain share in the military fiber optic cables market.
- Prysmian S.p.A.
- OFS Fitel, LLC
- Lynxeo SAS
- Sumitomo Electric Industries, Ltd.
- Optical Cable Corporation
- Corning Incorporated
- Gooch & Housego PLC
- Timbercon, Inc.
- W. L. Gore & Associates, Inc.
- Infinite Electronics, Inc.
- Sterlite Technologies Limited
- TE Connectivity plc
- L3Harris Technologies, Inc.
- Amphenol Corporation
- Radiall LLC
- Rosenberger Hochfrequenztechnik GmbH & Co KG
- Cinch Connectivity Solutions, Inc.
- Fujikura Ltd.
- Leoni AG
- Yangtze Optical Fibre and Cable Joint Stock Limited Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Battlefield demand for loss-less, EMI-immune data links
- 4.2.2 Militarisation of 5G tactical networks
- 4.2.3 Surge in ISR sensor density
- 4.2.4 Directed-energy weapons integration
- 4.2.5 Miniaturised rugged fiber terminations
- 4.2.6 NATO STANAG shift towards fiber-centric avionics architectures
- 4.3 Market Restraints
- 4.3.1 Field-level repair complexity
- 4.3.2 Supply chain security vulnerabilities
- 4.3.3 High lifecycle cost vs copper
- 4.3.4 Vulnerability to bend-loss under dynamic vibration in armored vehicles
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cable Type
- 5.1.1 Single-mode
- 5.1.2 Multi-mode
- 5.2 By Material Type
- 5.2.1 Glass Optical Fiber
- 5.2.2 Plastic Optical Fiber
- 5.3 Deployment Platform
- 5.3.1 Land Systems
- 5.3.2 Airborne Systems
- 5.3.3 Naval and Sub-sea Systems
- 5.4 By Installation Environment
- 5.4.1 Tactical Field-Deployable
- 5.4.2 Harsh-Environment Armored
- 5.4.3 Under-water / Submarine
- 5.5 By Application
- 5.5.1 C3ISR and Tactical Communications
- 5.5.2 Radar and Electronic Warfare
- 5.5.3 Guided and Directed-Energy Weapons
- 5.5.4 On-board Data Networks / Avionics
- 5.5.5 Others (Power-over-Fiber, Sensors)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Russia
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 Singapore
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Israel
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Prysmian S.p.A.
- 6.4.2 OFS Fitel, LLC
- 6.4.3 Lynxeo SAS
- 6.4.4 Sumitomo Electric Industries, Ltd.
- 6.4.5 Optical Cable Corporation
- 6.4.6 Corning Incorporated
- 6.4.7 Gooch & Housego PLC
- 6.4.8 Timbercon, Inc.
- 6.4.9 W. L. Gore & Associates, Inc.
- 6.4.10 Infinite Electronics, Inc.
- 6.4.11 Sterlite Technologies Limited
- 6.4.12 TE Connectivity plc
- 6.4.13 L3Harris Technologies, Inc.
- 6.4.14 Amphenol Corporation
- 6.4.15 Radiall LLC
- 6.4.16 Rosenberger Hochfrequenztechnik GmbH & Co KG
- 6.4.17 Cinch Connectivity Solutions, Inc.
- 6.4.18 Fujikura Ltd.
- 6.4.19 Leoni AG
- 6.4.20 Yangtze Optical Fibre and Cable Joint Stock Limited Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment