

|
시장보고서
상품코드
2122457
세라믹 폼 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Ceramic Foam - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
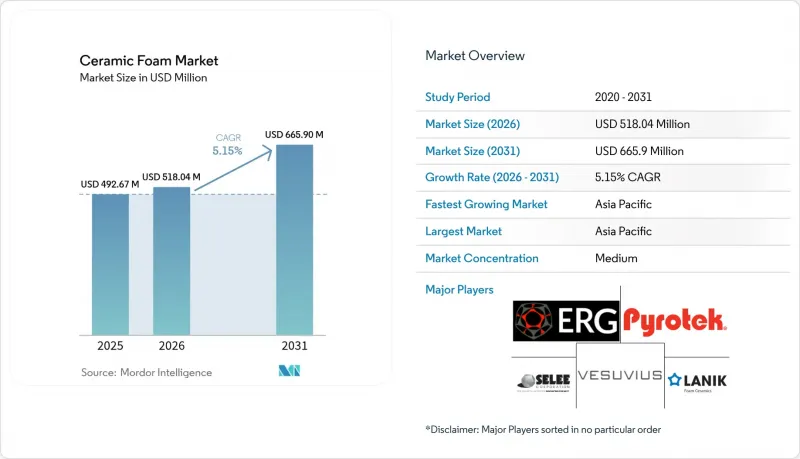
에 의하면, 2026년 세라믹 폼 시장 규모는 5억 1,804만 달러로 추정되며, 2025년 4억 9,267만 달러에서 2031년에는 6억 6,590만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR)은 5.15%를 기록할 것으로 전망됩니다.
본 보고서는 유형(알루미늄 산화물, 실리콘 카바이드 등), 제조 공정(레플리카/폴리머 스폰지법, 직접 발포법 등), 용도(용융 금속 여과, 자동차 배기 필터 등),최종 사용자 산업(주조, 자동차 등), 지역(아시아태평양, 북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 세라믹 폼 시장 동향 및 인사이트
EV 주조 거점에서의 저배출형 용융 금속 여과에 대한 수요 급증
전기차(EV) 플랫폼에서는 전도성 및 피로 강도 목표를 달성하기 위해 극도로 깨끗한 용융 금속이 필요한 대형 알루미늄 구조 주조품이 사용되고 있습니다. 현재 세라믹 폼 필터를 통해 배터리 하우징 및 모터 케이싱 내의 불순물 수준을 10ppm 미만으로 억제할 수 있게 되었습니다. 베스비우스(Vesuvius)사의 보고서에 따르면, EV 전용 파운드리에서 SEDEX사의 실리콘 카바이드 필터 채택률은 기존 자동차 생산 라인에 비해 40% 더 높은 것으로 나타났습니다. 테슬라의 상하이 공장과 유사한 아시아 시설에서는 고압 다이캐스팅용으로 실리콘 카바이드 폼이 지정되어 있으며, 이것이 지역 수요를 견인하고 있습니다. 이러한 사양으로 인해 처리량과 재현성 기준이 높아졌으며, 개선된 레플리카 공법으로 제조된 견고한 오픈 셀 구조가 유리하게 작용하고 있습니다. 아시아태평양공급망 현지화 노력은 세라믹 폼 시장의 지역적 우위를 더욱 공고히 하고 있습니다.
고온 촉매 지지체가 필요한 수소 생산의 급속한 확대
세계 전해조 및 수증기 개질 설비의 확대에 따라, 부식성 환경에서 600-900°C의 주기적인 가동을 견딜 수 있는 내화성 지지체가 요구되고 있습니다. Ceramics UK 컨소시엄은 100% 수소를 연료로 사용하는 가마를 검증하여 차세대 에너지 시스템에서 세라믹 폼의 적합성을 확인했습니다. 생고뱅(Saint-Gobain)은 촉매 지지체 생산 확대를 위해 뉴욕에 4,000만 달러를 투자하며 북미 시장에서 그 기세를 돋보이게 하고 있습니다. 세라믹 폼으로 보강된 코디에라이트 모놀리스는 800°C에서 최적의 선택성을 발휘하여, 개질기 및 고체 산화물형 연료전지의 유지보수 주기를 연장합니다. 더 많은 지역에서 국가 수소 로드맵이 발표됨에 따라, 촉매 지지체에 대한 수주는 세라믹 폼 시장에 지속적인 성장의 길을 열어주고 있습니다.
알루미나 및 지르코니아 가격 변동이 이익률을 압박
고순도 알루미나 및 지르코니아는 세라믹 폼 생산에서 변동비의 상당 부분을 차지합니다. 가격의 급격한 변동으로 인해 분기별 계약 재협상이나 높은 프리미엄을 지불하고 현물 구매를 해야 하는 상황에 처해 있습니다. 지르코니아를 통한 보강은 압축 강도를 206% 향상시키지만, 원자재 가격이 급등하면 경제성이 떨어집니다. Morgan Advanced Materials는 수주량이 안정적이었음에도 불구하고, 비용 상승을 추가 요금 인상이 따라가지 못해 열세라믹 부문의 매출이 4.6% 감소했다고 보고했습니다. 장기 계약을 맺지 않은 아시아의 소규모 제조업체들은 이익률 압박에 직면했고, 그 결과 세라믹 폼 업계에서 공장 현대화 및 생산 능력 확대가 둔화되었습니다.
부문별 분석
실리콘 카바이드는 1,500°C 이상의 안정성, 용융 알루미늄에 대한 내성, 그리고 뛰어난 열전도율 덕분에 2025년에 세라믹 폼 시장의 44.74% 점유율을 차지했습니다. 전기자동차(EV)용 주조량 증가와 불순물 함량에 대한 엄격한 제한이 지속적인 수요를 뒷받침하고 있습니다. 마그네슘-알루미나-스피넬, 붕소 세라믹, 하이브리드 복합재료 등 기타 첨단 복합재료는 연평균 성장률(CAGR) 7.41%로 가장 빠르게 성장하는 분야를 형성하고 있으며, 항공우주, 원자력 및 초고온 분야의 요구를 충족시키고 있습니다. 알루미늄 산화물은 높은 비용 효율성으로 인해 범용 주철 용도에서 여전히 매력적이지만, 내열 온도의 상한선이 전기차 및 수소 관련 신규 분야로의 진출을 제한하고 있습니다. 지르코늄 산화물은 화학적 부식성이 강한 용융 금속 분야에서 틈새 시장 지위를 유지하고 있으며, 그 높은 가격은 수명 연장 및 내식성 향상을 통해 정당화되고 있습니다.
2세대 붕소화물 폼은 1,800°C를 넘는 내산화성을 보여주고 있으며, 초음속 항공기의 열방호 부품으로서의 입지가 확립되었습니다. 조사용 프로토타입은 1,000회의 열 사이클 후에도 질량 손실이 5% 미만으로 유지되었으며, 이 획기적인 성과가 향후 상용화를 뒷받침할 가능성이 있습니다. 재료 과학자들이 위스커 보강과 산화물 스케일을 결합한 다상 폼을 합성함에 따라, 극한 환경에서 사용되는 기존의 알루미나(alumina)는 세라믹 폼 시장에서 점차 대체될 가능성이 있습니다.
레플리카 법 또는 폴리머 스폰지 법은 수십 년에 걸친 설비 상각, 낮은 스크랩률, 그리고 확립된 품질 관리 덕분에 2025년에 출하된 전체 세라믹 폼의 66.58%를 생산했습니다. 이 방법은 10-60 ppi의 균일한 기공 직경을 가진 필터 제조에 탁월하며, 대량 생산을 하는 비철금속 파운드리에 기여하고 있습니다. 이러한 지배적 지위에도 불구하고, 세라믹 폼 시장은 연평균 성장률(CAGR) 7.55%로 가장 빠르게 성장하고 있는 공정인 적층 가공로 전환되고 있습니다. 레이저 소결을 통한 알루미나 격자나 직접 잉크 방식으로 성형된 코디에라이트 지지체를 통해, 복제법으로는 달성할 수 없는 단계적인 기공률 및 토폴로지 최적화가 가능해집니다. 촉매 지지체 및 항공우주 분야의 조기 도입 기업들은 설계의 자유도를 활용하여 유체의 균일성과 기계적 강인성을 향상시키고 있습니다.
세라믹 슬러리에 가스를 혼합하여 생성된 기포를 소결하는 ‘직접 발포’는 폴리우레탄 템플릿 및 이에 수반되는 번아웃 배출물을 제거합니다. 이 기술의 도입은 그린 빌딩 인증 획득을 목적으로 하는 단열 패널 분야에서 가장 활발히 진행되고 있습니다. 젤 캐스팅은 생체의료용 임플란트나 반도체 웨이퍼용 지지대 등 니어넷쉐이프의 정밀도가 요구되는 용도에서 여전히 자리 잡고 있지만, 사이클 타임이 비교적 긴 점이 더 광범위한 보급을 저해하고 있습니다.
지역별 분석
2025년 아시아태평양의 매출 점유율 46.25%는 원자재, 주조 시설, 하류 전기차(EV) 생산을 아우르는 통합된 공급망을 반영합니다. 중국의 지속적인 철강 생산과 일본의 첨단 세라믹 연구가 기준 생산량을 뒷받침하는 한편, 한국의 수소 경제 로드맵은 촉매용 발포체의 향후 수요를 높이고 있습니다. 예측에 따르면, 이 지역의 세라믹 발포체 시장은 예측 기간 동안 연평균 성장률(CAGR) 7.08%를 기록하며 상당한 성장이 예상됩니다. 스마트 제조 및 에너지 효율화에 대한 정부의 보조금은 주조, 자동차, 건설 부문에서의 채택을 촉진하고 있습니다.
북미는 성숙해 가고 있지만 여전히 혁신적인 시장입니다. 이 지역에는 적층 가공(애디티브 매뉴팩처링)의 선구자들이 존재하며, 연방 정부의 수소 및 배터리 공급망에 대한 자금 지원의 혜택을 받고 있습니다. 생고뱅(Saint-Gobain)사의 뉴욕 사업 확장은 국내 촉매 지지체 수요에 대한 확신을 뒷받침하고 있습니다. 미국 내 자동차 배기가스 규제 강화는 세라믹 배기 필터의 소비를 촉진하고 있습니다. 중서부 지역의 안정적인 주철 주조 사업과 전기차(EV) 부품용 알루미늄 주조의 확대가 수요의 견조함을 보장하고 있습니다.
유럽에서는 순환 경제의 의무화와 탄소 중립 철강이 우선시되고 있어, 미니밀에서 재활용 가능한 내화 폼의 채택을 촉진하고 있습니다. 독일, 프랑스, 이탈리아에서는 자동 필터 처리 시스템을 도입하여 주조 라인을 업그레이드하고 있으며, 이를 통해 더욱 견고한 폼 배합에 대한 연구가 촉진되고 있습니다. EU는 항공우주 및 방위 분야를 위해 맞춤화된 기공 구조를 제조하는 적층 가공 파일럿 라인에 보조금을 지급하고 있습니다. 엄격한 건축 에너지 지침에 따라, 리모델링 프로젝트에서 세라믹 단열 패널의 도입이 촉진되고 있습니다.
남미, 중동 및 아프리카은 규모는 작지만 성장하고 있습니다. 브라질과 아르헨티나의 자동차 제조업체들은 알루미늄 주조용 필터를 채택하고 있으며, 사우디아라비아의 ‘비전 2030’에 기반한 새로운 철강 생산 능력 확대가 내화재 수요를 뒷받침하고 있습니다. 외국 직접 투자는 현지 기술력을 높이는 첨단 소재 연구소를 뒷받침하고 있습니다. 인프라 부족과 기술적 전문 지식의 한계가 도입을 저해하고 있지만, 현지 생산을 위한 파트너십을 통해 세라믹 폼 산업의 잠재력을 이끌어낼 수 있을 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, ceramic foam market size in 2026 is estimated at USD 518.04 million, growing from 2025 value of USD 492.67 million with 2031 projections showing USD 665.9 million, growing at 5.15% CAGR over 2026-2031.
This report is Segmented by Type (Aluminum Oxide, Silicon Carbide, and More), Manufacturing Process (Replica/Polymer Sponge Method, Direct Foaming, and More), Application (Molten Metal Filtration, Automotive Exhaust Filters, and More), End-User Industry (Foundry, Automotive, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Ceramic Foam Market Trends and Insights
Surging demand for low-emission molten metal filtration in EV casting hubs
Electric-vehicle platforms use large aluminum structural castings that require exceptionally clean melts to meet conductivity and fatigue targets. Ceramic foam filters now enable sub-10 ppm inclusion levels in battery housings and motor casings. Vesuvius reports 40% higher uptake of SEDEX silicon-carbide filters in EV-dedicated foundries compared with conventional automotive lines. Tesla's Shanghai operations and similar Asian facilities specify silicon-carbide foams for high-pressure die casting, driving regional volume. These specifications raise throughput and repeatability criteria that favor robust open-cell geometries produced via improved replica methods. Supply-chain localization efforts in Asia-Pacific further cement regional dominance of the ceramic foam market.
Rapid expansion of hydrogen production requiring high-temperature catalyst supports
Global electrolyzer and steam-reform expansion demands refractory carriers that withstand cyclic 600-900 °C operation in corrosive atmospheres. The Ceramics UK consortium validated 100% hydrogen-fired kilns, confirming ceramic foam suitability for next-generation energy systems. Saint-Gobain is investing USD 40 million in New York to scale catalyst-carrier output, highlighting North American momentum. Cordierite monoliths reinforced with ceramic foam achieve optimal selectivity at 800 °C, extending service intervals for reformers and solid-oxide fuel cells. As more regions publish national hydrogen roadmaps, catalyst support orders provide a durable growth pathway for the ceramic foam market.
Volatile alumina and zirconia prices pressuring profit margins
High-purity alumina and zirconia constitute a significant portion of the variable costs in ceramic foam production. Sharp price swings have forced quarterly contract renegotiations and spot purchases at elevated premiums. Zirconia toughening boosts compressive strength by 206% yet becomes less economical when raw-material indices spike. Morgan Advanced Materials noted a 4.6% revenue dip in its Thermal Ceramics unit despite stable order intake because surcharges lagged cost inflation. Smaller Asian producers, lacking long-term contracts, experienced margin compression that slowed plant upgrades and capacity additions within the ceramic foam industry.
Other drivers and restraints analyzed in the detailed report include:
- Additive manufacturing enabling complex, cost-efficient open-cell foam geometries
- Circular-economy push for recyclable refractory linings in steel mini-mills
- Brittleness leading to handling losses in automated foundries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicon carbide commanded 44.74% share of the ceramic foam market in 2025 due to its stability above 1,500 °C, resistance to molten aluminum and superior thermal conductivity. Rising EV casting volumes and stringent inclusion limits underpin sustained demand. Other advanced compositions such as magnesium-aluminate spinel, boride ceramics and hybrid composites form the fastest-growing cluster at a 7.41% CAGR, fulfilling aerospace, nuclear and ultra-high-temperature needs. Aluminum oxide remains attractive for general-purpose iron casting thanks to cost-efficiency, though its temperature ceiling constrains penetration into new EV and hydrogen segments. Zirconium oxide retains a niche in chemically aggressive melts, where its premium price is justified by extended service life and enhanced corrosion resistance.
Second-generation boride foams demonstrate oxidation resistance above 1,800 °C, positioning them for hypersonic vehicle thermal-protection components. Research prototypes exhibit less than 5% mass loss after 1,000 thermal cycles, a milestone that could spur future commercialization. As material scientists synthesize multiphase foams combining whisker reinforcement and oxide scales, the ceramic foam market may witness incremental displacement of legacy alumina in extreme environments.
The replica or polymer-sponge process produced 66.58% of all ceramic foams shipped in 2025 owing to decades of equipment amortization, low scrap rates and familiar quality controls. It excels in producing filters with consistent pore sizes from 10 to 60 ppi, serving high-volume non-ferrous foundries. Despite its dominance, the ceramic foam market is pivoting toward additive manufacturing, the fastest-growing process at 7.55% CAGR. Laser-sintered alumina lattices and direct-ink-written cordierite carriers allow graded porosity and topology optimization unattainable with replica routes. Early adopters in catalyst support and aerospace exploit design freedom to enhance flow uniformity and mechanical resilience.
Direct foaming, which mixes gas into ceramic slurry then sinters the resulting froth, eliminates polyurethane templates and their associated burn-out emissions. Uptake is strongest in insulation panels targeting green-building credits. Gel casting endures in applications requiring near-net-shape precision, such as biomedical implants and semiconductor wafer supports, though its relatively long cycle times limit broader diffusion.
Complete Report Scope:
- By Type
- Aluminum Oxide (Al2O3)
- Silicon Carbide (SiC)
- Zirconium Oxide (ZrO2)
- Others Types (Magnesium Aluminate Spinel, etc.)
- By Manufacturing Process
- Replica/Polymer Sponge Method
- Direct Foaming
- Gel Casting
- Additive Manufacturing
- By Application
- Molten Metal Filtration
- Automotive Exhaust Filters
- Thermal and Acoustic Insulation
- Catalyst Support
- Furnace Lining
- Other Applications (Biomedical Scaffolds, etc.)
- By End-User Industry
- Foundry
- Automotive
- Construction
- Pollution Control and Chemcial Synthesis
- Other End-user Industries (Power Generation and Energy, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 46.25% revenue share in 2025 reflects its integrated supply chain encompassing raw materials, casting facilities and downstream EV production. China's continual steel output and Japan's advanced ceramics research sustain baseline volumes, while South Korea's hydrogen-economy roadmap raises future demand for catalyst foams. Forecasts indicate the region's ceramic foam market is projected to witness significant growth, supported by a robust 7.08% CAGR during the forecast period. Government grants for smart manufacturing and energy efficiency amplify adoption across foundry, automotive, and construction sectors.
North America represents a mature yet innovative arena. The region fields additive-manufacturing pioneers and benefits from federal hydrogen and battery-supply-chain funding. Saint-Gobain's New York expansion confirms confidence in domestic catalyst-support demand. Tightening US vehicle emissions rules stimulate ceramic exhaust filter consumption. Stable iron foundry operations in the Midwest and growing aluminum casting for EV parts ensure demand resilience.
Europe prioritizes circular economy mandates and carbon-neutral steel, driving uptake of recyclable refractory foams in mini-mills. Germany, France and Italy upgrade casting lines with automated filter-handling systems, spurring research into tougher foam formulations. EU grants back additive-manufacturing pilot lines that fabricate customized pore architectures for aerospace and defense. Stringent building energy directives stimulate ceramic insulation panel deployment in renovation projects.
South America and Middle East & Africa are smaller but rising. Brazilian and Argentinian automakers adopt aluminum casting filters, while new steel capacity in Saudi Arabia's Vision 2030 bolsters refractory demand. Foreign direct investment underpins advanced-materials institutes that enhance local competence. Infrastructure gaps and limited technical expertise slow adoption, yet localized production partnerships could unlock latent potential for the ceramic foam industry.
- Altech Alloys India Pvt. Ltd.
- ASK Chemicals
- Carpenter Brothers, Inc.
- Drache Umwelttechnik GmbH
- ERG Aerospace Corporation
- Ferro-Term Sp. z o.o.
- FILTEC PRECISION CERAMICS CO., LTD.
- Galaxy Enterprise
- Jiangxi Jintai Special Material LLC.
- LANIK s.r.o.
- Porvair Filtration Group
- Pyrotek
- SELEE Corp.
- Ultramet
- Vertix Co.
- Vesuvius
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for low-emission molten metal filtration in EV casting hubs
- 4.2.2 Rapid expansion of hydrogen production requiring high-temperature catalyst supports
- 4.2.3 Additive manufacturing enabling complex, cost-efficient open-cell foam geometries
- 4.2.4 Circular-economy push for recyclable refractory linings in steel mini-mills
- 4.2.5 Government incentives for zero-energy buildings boosting ceramic-foam insulation panels
- 4.3 Market Restraints
- 4.3.1 Volatile alumina and zirconia prices pressuring profit margins
- 4.3.2 Brittleness leading to handling losses in automated foundries
- 4.3.3 Emerging polymer-derived foams offering cheaper insulation alternatives
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Aluminum Oxide (Al2O3)
- 5.1.2 Silicon Carbide (SiC)
- 5.1.3 Zirconium Oxide (ZrO2)
- 5.1.4 Others Types (Magnesium Aluminate Spinel, etc.)
- 5.2 By Manufacturing Process
- 5.2.1 Replica/Polymer Sponge Method
- 5.2.2 Direct Foaming
- 5.2.3 Gel Casting
- 5.2.4 Additive Manufacturing
- 5.3 By Application
- 5.3.1 Molten Metal Filtration
- 5.3.2 Automotive Exhaust Filters
- 5.3.3 Thermal and Acoustic Insulation
- 5.3.4 Catalyst Support
- 5.3.5 Furnace Lining
- 5.3.6 Other Applications (Biomedical Scaffolds, etc.)
- 5.4 By End-User Industry
- 5.4.1 Foundry
- 5.4.2 Automotive
- 5.4.3 Construction
- 5.4.4 Pollution Control and Chemcial Synthesis
- 5.4.5 Other End-user Industries (Power Generation and Energy, etc.)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 NORDIC Countries
- 5.5.3.8 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Altech Alloys India Pvt. Ltd.
- 6.4.2 ASK Chemicals
- 6.4.3 Carpenter Brothers, Inc.
- 6.4.4 Drache Umwelttechnik GmbH
- 6.4.5 ERG Aerospace Corporation
- 6.4.6 Ferro-Term Sp. z o.o.
- 6.4.7 FILTEC PRECISION CERAMICS CO., LTD.
- 6.4.8 Galaxy Enterprise
- 6.4.9 Jiangxi Jintai Special Material LLC.
- 6.4.10 LANIK s.r.o.
- 6.4.11 Porvair Filtration Group
- 6.4.12 Pyrotek
- 6.4.13 SELEE Corp.
- 6.4.14 Ultramet
- 6.4.15 Vertix Co.
- 6.4.16 Vesuvius
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Technological Advancements in Production Techniques


