|
시장보고서
상품코드
2122467
프리필드 시린지 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Prefilled Syringes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
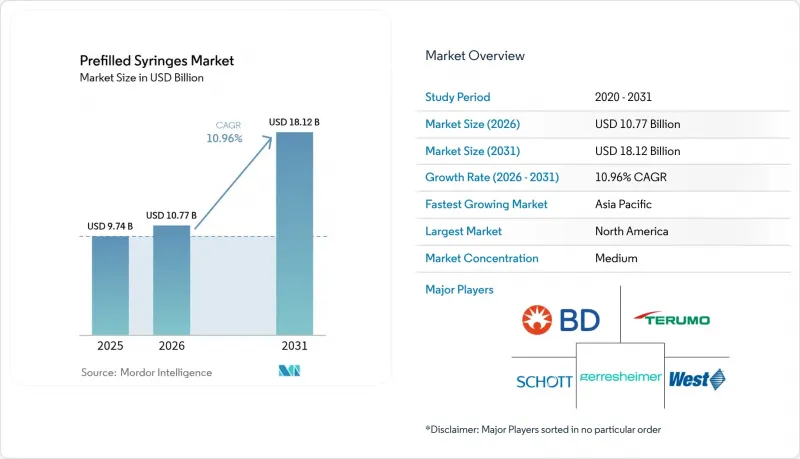
에 의하면, 프리필드 시린지 시장 규모는 2025년 97억 4,000만 달러로 평가되었습니다. 2026년에는 107억 7,000만 달러로 확대되어 2031년까지 181억 2,000만 달러에 이를 것으로 예측되며, 2026-2031년에 걸쳐 CAGR 10.96%로 성장할 전망입니다.

본 보고서는 소재별(유리, 폴리머), 용도별(당뇨병, 류마티스 관절염, 백신,항응고제, 기타 용도), 최종 사용자별(병원 및 클리닉, 외래수술센터(ASC), 재택치료, 기타 최종 사용자), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 프리필드 시린지 시장 동향 및 인사이트
만성 질환 유병률 증가
1990년부터 2022년에 걸쳐 당뇨병 유병률은 2배로 증가하여 전 세계 성인 인구의 14.0%에 달했습니다. 이에 따라 주 1회 GLP-1 요법이 주류로 자리 잡았습니다. 프리필드 시린지는 조제 실수를 방지하고 교육 시간을 단축하기 때문에 주사 센터에서의 투여와 비교했을 때 류마티스 관절염 환자 1인당 연간 치료비를 8,000-1만 2,000달러 절감합니다. 미국 및 독일의 보험사와의 계약에서는 이미 블루투스 지원 자동 주사기에서 얻은 복약 순응도 지표를 바탕으로 환급액이 결정되고 있어, 제조업체 입장에서는 스마트 제형을 공급함으로써 수익을 확보할 수 있는 인센티브가 되고 있습니다. 따라서 만성 질환 증가는 프리필드 시린지 시장, 특히 정확한 투여량이 필요한 장기 작용형 생물학적 제제 시장에 구조적인 호재를 가져오고 있습니다. 피하 투여용 항체 개발 파이프라인의 동향을 보면, 2031년 이후에도 지속적인 수요 기반이 형성될 것으로 예측됩니다.
자가 관리 및 재택치료 모델로의 전환
2024년에는 재택에서 생물학적 제제 주사를 지원하기 위해 메디케어 파트 B의 적용 범위가 확대되어, 2028년까지 전문 주사제의 투여량 중 약 25-30%가 병원 외래 진료 부문에서 재택으로 전환될 것으로 예측됩니다. 블루투스 지원 자동 주사기와 연동된 원격의료 플랫폼은 미국 내 시범 사업에서 복약 순응도 미준수로 인한 재입원을 최대 22% 감소시켰습니다. 유럽에서는 재택 간호 인프라 구축을 위해 50억 유로 상당의 구조기금이 배정되어 있으며, 이 정책의 EU 내 도입이 가속화되고 있습니다. 사전 충전 제제는 최종 재구성이라는 장벽을 제거하고, 필요한 기술 요건을 낮추며, 소비자에게 직접 유통할 수 있는 채널을 가능하게 합니다. 이러한 요인들이 결합되어 사전 충전 주사기의 잠재 시장은 병원의 범위를 넘어 확대되고 있습니다.
복합 추출물·용출물에 대한 규제 대응으로 인한 CMC 비용 상승
ISO 10993-18(2020년판)에서는 최악의 경우를 상정한 온도와 시간 조건 하에서 철저한 화학적 특성 평가가 의무화되어 있어, CMC 일정에 6-9개월의 지연이 발생하는 경우가 많아지고 있습니다. FDA 지침에서는 0.15µg/일이라는 분석 임계값이 설정되어 있으며, 이를 초과하는 경우 독성학적 근거를 제시해야 합니다. 지역별 기준이 중복되어 있어 미국, EU, 아시아에 신청할 때 중복된 검사를 피할 수 없게 되어, 중규모 바이오시밀러 개발 예산의 최대 12%를 소모하고 있습니다. 고리형 올레핀계 폴리머의 경우, 유리와 같은 과거의 안전성 데이터베이스가 없기 때문에 스폰서는 더욱 엄격한 심사에 직면하고 있으며, 심사 기간이 장기화되고 있습니다. 이러한 지연은 프리필드 시린지 시장의 단기적인 성장을 둔화시키고 있으며, 특히 자금 조달에 제약이 있는 신생 바이오테크 기업들에게는 큰 영향을 미치고 있습니다.
부문별 분석
2025년 매출에서 유리가 차지한 비중은 68.63%로, 이는 규제 당국의 확고한 수용과 성숙한 추출 데이터의 존재를 반영합니다. 그럼에도 불구하고, 폴리머의 연평균 성장률(CAGR) 11.06%는 신규 생산 능력 확충과 향후 제품 출시에서 결정적인 변화를 시사하며, 특히 오토인젝터 작동 시 파손 위험이 있는 고점도 단일클론 항체에서 두드러집니다. 또한, 폴리머는 유리 입자로 인한 리콜이나 붕규산 유리 공급 부족으로부터 후원사를 보호하기 위해, 추출물 검사에 따른 초기 부담이 있음에도 불구하고 병행된 검증 프로그램의 실시를 촉진하고 있습니다. SCHOTT와 Gerresheimer는 유리 부문에서 리더십을 유지하면서 폴리머 생산 라인을 증설함으로써 위험을 분산시키고 있으며, 이러한 이중 전략을 뒷받침하고 있습니다. 이러한 움직임으로 인해, 장기 보관이 요구되는 산소에 민감한 백신의 경우 유리가 여전히 필수적인 반면, 프리필드 시린지 시장은 공급업체의 다양성과 생산 능력의 회복력을 유지하게 될 것입니다.
지역별 분석
북미는 뉴저지주, 노스캐롤라이나주, 캘리포니아주에 집중된 바이오의약품 클러스터와 OSHA(미국 산업안전보건청)의 안전 규제에 힘입어 2025년 매출의 38.41%를 차지했습니다. 메디케어의 재택 간호 보험 적용으로 인해 2028년까지 전문 주사제 취급량의 최대 30%가 재택 간호로 전환될 것으로 예측되어, 환자 중심의 의료기기에 대한 수요가 확고해지고 있습니다. 캐나다의 규제 상호 인정 및 멕시코 내 CDMO의 확대는 지역 공급망을 확장시켜, 프리필드 시린지 시장의 꾸준한 성장을 뒷받침하고 있습니다.
유럽의 규제적 촉진요인으로는 EU 지침 2010/32/EU 및 바이오시밀러의 적극적인 도입을 들 수 있으며, 이 지역은 유리에서 폴리머로의 혁신을 주도하는 거점으로 계속 자리매김하고 있습니다. 2027년까지의 재택 간호 프로그램을 위한 50억 유로 규모의 구조 기금에 힘입어, 의료 서비스가 부족한 동부 지역에서 분산형 투여가 확대될 전망이지만, 날카로운 의료기기에 대한 규제 준수 현황이 제각각인 점이 여전히 보급을 저해하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 12.27%로 시장 성장을 주도하고 있습니다. 인도의 ‘생산 연계형 인센티브 제도’, 중국의 바이오시밀러 승인 기간 단축, 일본의 커넥티드 기기에 대한 보험 환급 우대 조치가 맞물려 현지에서의 제조와 소비를 확대시키고 있습니다. 엄격한 규제 체계를 갖춘 호주와 한국은 스마트 기기의 실증 실험을 위한 발판 역할을 하고 있으며, 그 성과는 향후 아세안 전역으로 확대될 전망입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the prefilled syringes market size is expected to increase from USD 9.74 billion in 2025 to USD 10.77 billion in 2026 and reach USD 18.12 billion by 2031, growing at a CAGR of 10.96% over 2026-2031.
This report is Segmented by Material (Glass, Polymer), Application (Diabetes, Rheumatoid Arthritis, Vaccines, Anticoagulants, Other Applications), End-User (Hospitals & Clinics, Ambulatory Surgical Centers, Home Healthcare Settings, Other End Users), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Prefilled Syringes Market Trends and Insights
Rising Prevalence of Chronic Diseases
Diabetes prevalence doubled between 1990 and 2022, climbing to 14.0% of the global adult population and pushing weekly GLP-1 therapies into mainstream use. Prefilled syringes eliminate reconstitution errors and shorten training time, thereby lowering annual treatment costs by USD 8,000-12,000 per rheumatoid arthritis patient compared with infusion-center administration. Payer contracts in the United States and Germany already link reimbursement to adherence metrics pulled from Bluetooth-enabled autoinjectors, giving manufacturers a revenue-protection incentive to supply smart formats. Chronic-disease growth, therefore, delivers a structural lift to the prefilled syringes market, especially for long-acting biologics that require precise dosing. Forward pipelines of subcutaneous antibodies suggest a durable demand floor extending past 2031.
Shift Toward Self-Administration & Home-Healthcare Models
Medicare Part B coverage expanded in 2024 to support home-injected biologics, shifting an estimated 25-30% of specialty injectable volume out of hospital outpatient departments by 2028. Telehealth platforms paired with Bluetooth autoinjectors reduced readmissions due to non-compliance by up to 22% in U.S. pilots. European structural funds worth EUR 5 billion are earmarked for home-care infrastructure, accelerating the policy's export to the EU. Prefilled formats remove the final reconstitution barrier, lowering skill requirements and enabling direct-to-consumer channels. Combined, these factors expand the addressable market for prefilled syringes beyond hospital walls.
Complex Extractables / Leachables Compliance Elevating CMC Costs
ISO 10993-18:2020 compels exhaustive chemical characterization under worst-case temperature and time scenarios, often adding 6-9 months to CMC timelines. FDA guidance sets an analytical threshold of 0.15 µg/day above which toxicology justifications are mandatory. Redundant regional standards force duplicate testing for U.S., EU, and Asian submissions, consuming up to 12% of mid-tier biosimilar development budgets. Cyclic-olefin polymers lack the historical safety database of glass, so sponsors face even more scrutiny, extending review cycles. These delays temper near-term growth for the prefilled syringes market, especially for cash-constrained biotech entrants.
Other drivers and restraints analyzed in the detailed report include:
- Acceleration of Biologics / Biosimilars Pipeline Requiring Ready-To-Fill Containers
- Regulatory Emphasis on Needlestick-Injury Prevention
- Supply-Chain Constraints for Medical-Grade Borosilicate Glass
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Glass accounted for 68.63% of 2025 revenue, reflecting entrenched regulatory acceptance and mature extractables data. Nonetheless, polymer's 11.06% CAGR signals a decisive tilt in new capacity adds and future launches, particularly for high-viscosity monoclonal antibodies at fracture risk during autoinjector actuation. Polymer also shields sponsors from glass-particle recalls and borosilicate shortages, prompting parallel validation programs despite the upfront burden of extractables testing. SCHOTT and Gerresheimer are hedging by adding polymer lines while maintaining glass leadership, confirming a dual-track strategy. These moves ensure the prefilled syringes market retains supplier diversity and capacity resilience, even as glass remains indispensable for oxygen-sensitive vaccines requiring long shelf lives.
Complete Report Scope:
- By Material
- Glass Prefilled Syringes
- Polymer Prefilled Syringes
- By Application
- Diabetes
- Rheumatoid Arthritis
- Vaccines
- Anticoagulants
- Other Applications
- By End-user
- Hospitals & Clinics
- Ambulatory Surgical Centers
- Home Healthcare Settings
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 38.41% of 2025 revenue, buoyed by dense biologics clusters in New Jersey, North Carolina, and California, as well as OSHA safety mandates. Medicare home care coverage is projected to divert up to 30% of specialty injectable volume by 2028, cementing demand for patient-centric devices. Canada's regulatory reciprocity and Mexico's CDMO expansions extend the regional supply chain, supporting steady growth in the prefilled syringes market.
Europe's regulatory drivers include EU Directive 2010/32/EU and aggressive biosimilar adoption, keeping the region a stronghold for glass-to-polymer innovation. Structural funds of EUR 5 billion for home-care programs through 2027 will expand decentralized administration in underserved Eastern regions, though uneven compliance with sharps mandates continues to restrain uptake.
Asia-Pacific is the growth engine at a 12.27% CAGR. India's Production Linked Incentive scheme, China's shortened biosimilar approval windows, and Japan's reimbursement premium for connected devices combine to amplify local manufacturing and consumption. Australia and South Korea, with tight regulatory regimes, serve as beachheads for smart-device pilots that later scale across ASEAN.
- Abbvie
- Amgen
- AptarGroup Inc.
- Baxter
- Beckton Dickinson
- Catalent
- Fresenius
- Gerresheimer
- Johnson & Johnson
- Medtronic
- Nipro
- Novartis
- Pfizer
- Roche
- Sanofi
- SCHOTT
- Smiths Group
- Terumo
- Vetter Pharma International GmbH
- West Pharmaceutical Services
- Ypsomed
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Chronic Diseases
- 4.2.2 Shift Toward Self-Administration & Home-Healthcare Models
- 4.2.3 Acceleration of Biologics/Biosimilars Pipeline Requiring Ready-To-Fill Containers
- 4.2.4 Regulatory Emphasis on Needlestick-Injury Prevention
- 4.2.5 Emergence of Connected "Smart" Syringes Enabling Dose-Tracking
- 4.2.6 Capacity Investments In Polymer PFS Lines to Mitigate Glass Shortages
- 4.3 Market Restraints
- 4.3.1 Complex Extractables/Leachables Compliance Elevating CMC Costs
- 4.3.2 Supply-Chain Constraints for Medical-Grade Borosilicate Glass
- 4.3.3 Tightening PFAS & Silicone-Oil Regulations Impacting Legacy Lubricants
- 4.3.4 Growing Environmental Scrutiny on Single-Use Plastics Disposal
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Material
- 5.1.1 Glass Prefilled Syringes
- 5.1.2 Polymer Prefilled Syringes
- 5.2 By Application
- 5.2.1 Diabetes
- 5.2.2 Rheumatoid Arthritis
- 5.2.3 Vaccines
- 5.2.4 Anticoagulants
- 5.2.5 Other Applications
- 5.3 By End-user
- 5.3.1 Hospitals & Clinics
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Home Healthcare Settings
- 5.3.4 Other End Users
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 Amgen Inc.
- 6.3.3 AptarGroup Inc.
- 6.3.4 Baxter International Inc.
- 6.3.5 Becton Dickinson & Company
- 6.3.6 Catalent Inc.
- 6.3.7 Fresenius Kabi AG
- 6.3.8 Gerresheimer AG
- 6.3.9 Johnson & Johnson
- 6.3.10 Medtronic
- 6.3.11 Nipro Corporation
- 6.3.12 Novartis AG
- 6.3.13 Pfizer Inc.
- 6.3.14 Roche Holding AG
- 6.3.15 Sanofi S.A.
- 6.3.16 SCHOTT AG
- 6.3.17 Smith & Nephew plc
- 6.3.18 Terumo Corporation
- 6.3.19 Vetter Pharma International GmbH
- 6.3.20 West Pharmaceutical Services Inc.
- 6.3.21 Ypsomed AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment