

|
시장보고서
상품코드
2122468
분만 중 모니터링 장치 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Intrapartum Monitoring Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 분만 중 모니터링 장치 시장 규모는 2025년에 24억 5,000만 달러로 평가되었습니다. 2026년 26억 1,000만 달러에서 2031년까지 35억 5,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 6.38%를 나타낼 전망입니다.

본 보고서는 제품 유형별(전극, 모니터), 모니터링 방법별(침습적, 비침습적), 휴대성별(고정식, 휴대식), 최종 사용자별(병원, 전문 클리닉, 기타), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 분만 중 모니터링 장치 시장 동향 및 인사이트
비침습적 태아 심전도 기술의 급속한 보급
비침습적 태아 심전도는 벨트나 두피 전극을 사용하지 않고도 심박동마다 심박수를 분석할 수 있게 하며, 특히 BMI가 높은 환자의 경우 도플러법과 동등하거나 그 이상의 정확도를 발휘합니다. 이러한 움직임의 자유도는 임산부의 만족도를 높여주며, 이 지표는 현재 병원에 대한 보험 지급액에도 반영되고 있습니다. 팬데믹 기간에 실시된 원격 모니터링 시범 사업에서는 지속적인 데이터를 임상의에게 전송하는 재택용 심전도 패치의 유효성이 입증되어, 모니터링을 유지하면서도 감염 위험을 줄일 수 있게 되었습니다. 이에 따라 의료 시스템 조달 위원회는 기동성, 편안함, 신호의 안정성을 주요 기준으로 삼아 공급업체들에게 무선 패치 플랫폼에 심전도 채널을 통합할 것을 촉구하고 있습니다. AI 분석에 주력하는 스타트업 기업들은 연속적인 파형을 몇 초 이내에 구체적인 조치가 필요한 경보로 변환함으로써, 더 큰 부가가치를 제공합니다.
조산 및 신생아 중환자실(NICU) 입원 증가
2020년에는 전 세계적으로 1,340만 명의 아기가 조산으로 태어났으며, 이는 출생 수의 9.9%에 해당합니다. 미국에서는 신생아 중환자실(NICU) 입원율이 2016년 8.7%에서 2023년 9.8%로 상승했습니다. 신생아 중환자실(NICU)의 1일당 비용이 3,000-5,000달러에 달하기 때문에 분만 중 조기 발견은 보험사에게 경제적으로 매력적인 선택지가 되고 있습니다. 태아 심박수 감속이나 자궁 빈수축을 몇 분 더 빨리 감지하는 고도 모니터링을 통해 응급 제왕절개나 신경발달장애의 발생률을 낮출 수 있습니다. 이러한 추세는 분만을 늦추는 여성이 늘어나면서 더욱 강화되고 있습니다. 35세 이상 산모의 임신은 위험이 높기 때문에 간헐적인 청진 대신 지속적인 전자 모니터링이 이루어지는 사례가 늘고 있습니다.
고도 중앙 모니터링 스테이션 도입에 필요한 막대한 설비 투자
다병상 대응 태아 원격 모니터링 플랫폼에 투자하는 병원은 전자건강기록(EHR)과의 통합, 사이버 보안 대책 강화, 직원 재교육 등을 포함하면 종종 7자리 수의 예산에 직면합니다. Prisma Health가 1,500개 병상에 걸쳐 4,100만 달러를 투자하여 스마트 침대를 도입한 사례는 이러한 설비 투자의 규모를 여실히 보여줍니다. BARTS Health NHS Trust의 시설 전체 생체 신호 모니터링과 같은 조달 입찰에서는 오픈 API 및 ISO 27001 준수가 요구되어 IT 관련 부담이 증가하고 있습니다. 자금 부족에 시달리는 지역 병원들은 업그레이드를 미룰 수밖에 없으며, 그 결과 농촌 지역의 임산부는 연속 CTG 대신 촉진이나 간헐적인 도플러 검사를 받는 등 기술 격차가 발생하는 상황이 초래되고 있습니다.
부문별 분석
2025년에는 전극이 매출의 64.88%를 차지하며, 모든 모달리티에서 신호 획득에 필수적인 역할을 하고 있음이 부각되었습니다. 반면, 모니터는 6.89%라는 더 높은 연평균 성장률(CAGR)을 기록하고 있으며, 이는 태아, 산모, 자궁 각 채널을 하나의 하우징에 통합한 다중 매개변수 및 AI 지원 플랫폼에 대한 수요를 반영합니다. GE의 ‘Novii’ 무선 패치는 벨트가 필요 없는 쉘 내에 ECG 및 EMG 기능을 통합하여 환자의 편의성을 높이는 동시에 기록에 관한 규제 요건도 충족하고 있습니다. 삼성이 9,240만 달러에 ‘Sonio’를 인수한 것은 CTG 워크플로우를 강화하는 초음파 연동 분석 기능에 대한 관심이 높음을 여실히 보여줍니다. 이러한 통합을 통해 분만 중 모니터링 장치 시장에서 하드웨어의 업데이트 주기를 초월한 종합적인 가치 제안을 실현할 수 있게 됩니다. 각 모니터에는 여전히 일회용 또는 재사용형 트랜스듀서가 필요하기 때문에 전극 유닛의 판매 대수는 꾸준히 증가하고 있으며, 소모품을 통한 큰 수익원이 유지되고 있습니다.
2세대 모니터는 클라우드 연결 기능과 의사 결정 지원 기능을 통합하고 있어, 구매 기준이 하드웨어 사양에서 소프트웨어 로드맵으로 전환되고 있습니다. EDAN의 F3 태아 모니터는 내장된 CTG 분석 기능을 갖추고 있어, 경험이 부족한 직원의 해석 부담을 덜어줍니다. 구독 기반 알고리즘 업데이트를 검토하고 있는 벤더는 수익을 안정화할 수 있는 반면, 병원 측은 설비 투자를 하지 않고도 지속적으로 개선되는 분류 기능을 이용할 수 있게 됩니다. 이러한 융합을 통해 모니터는 소모품인 전극에 의해 뒷받침되는 소프트웨어 플랫폼으로 자리매김하며, 분만 중 모니터링 장치 시장에서 지속적인 견인력을 확보하게 될 것입니다.
비침습형 시스템은 2025년 매출의 69.22%를 차지했으며, 연평균 성장률(CAGR) 6.96%를 나타낼 것으로 전망되어 시장 규모 및 성장률 양면에서 선두 자리를 유지하고 있습니다. 외부 도플러 초음파 장치와 자궁 수축계는 자궁경부 확장 및 감염 위험을 피할 수 있어 일상적인 산과 진료에서 주류를 이루고 있습니다. 새로운 패치가 블루투스를 통해 신호를 중계함으로써, 임산부는 스트랩을 재조정할 필요 없이 자유롭게 걷거나 분만용 공을 사용할 수 있게 되어, 분만 모니터링 장치 시장 규모는 더욱 확대되고 있습니다. 비만, 태위 이상 또는 신호 노이즈로 인해 외부 측정이 방해받는 경우, 두개내 전극과 자궁내압 카테터는 여전히 정확도 면에서 골드 스탠다드로 남아 있습니다. 최근 임상 연구에 따르면, 내부 CTG는 외부 모니터링에 비해 제왕절개율을 높이지 않으며 신생아의 예후도 악화시키지 않는 것으로 나타나, 임상 적용 범위가 확대될 가능성이 있습니다. 다만, 양막 파열의 필요성으로 인해 그 사용은 제한되고 있습니다.
하이브리드형 원격 측정은 고충실도 신호와 기동성이라는 두 가지 이점을 제공합니다. 헬싱키 대학의 모체 맥박 동시 기록에 관한 연구 결과, 아티팩트 필터링이 신생아 뇌병증을 예방한다는 사실이 확인되었으며, 이에 따라 다중 매개변수 솔루션의 도입이 가속화되고 있습니다. 따라서 외부 모니터링 플랫폼은 크로스 토크를 자동으로 보정하는 산모 심전도(ECG) 채널을 통합하는 방향으로 진화하고 있으며, 이는 분만 모니터링 장치 시장에서 비침습적 기술의 우위를 더욱 공고히 하고 있습니다.
지역별 분석
북미가 41.85%의 점유율을 차지하는 배경에는 엄격한 기준과 높은 1인당 의료비 지출이 있습니다. 향후 시행될 CMS(미국 의료보험서비스센터) 규정에 따라 태아 모니터링에 대한 보편적인 접근이 의무화될 뿐만 아니라, NICU(신생아 집중치료실) 입원 비율이 출생아의 10%에 육박함에 따라 모니터링의 고도화가 진행되고 있습니다. 그러나 2024년에는 지방의 산과 병동이 잇달아 폐쇄되고 의료 과실 보험료도 상승함에 따라, 의료 기관은 현장에 전문의가 없어도 모니터링 범위를 확대할 수 있는 텔레 CTG 허브의 검사 운영을 어쩔 수 없이 도입하고 있습니다. Philips가 조지아주의 의료 보험 플랜과 제휴하여 원격 임산부 관리 프로그램을 전개하고 있는 것과 같은 벤더간의 제휴는 분만 중 모니터링 장치 시장이 인력 부족에 어떻게 적응하고 있는지를 보여줍니다.
아시아태평양은 산모 사망률 감소를 위한 노력과 도시 지역의 병원 건설 붐에 힘입어 연평균 성장률(CAGR) 7.18%라는 가장 빠른 성장률을 기록하고 있습니다. 각국 정부는 지방 산부인과 병동에 3차 의료기관의 클라우드 대시보드와 연동되는 블루투스 CTG를 도입하는 디지털 헬스 실증 사업에 보조금을 지원하고 있습니다. 일본과 한국에서는 AI를 활용한 파형 분석 시범 사업이 의사결정을 신속화하는 한편, 신흥 경제국에서는 조산사 교육과 병행하여 기본적인 장비 도입을 우선시하고 있습니다. 아시아개발은행(ADB)의 통합 케어 보조금은 산과와 비전염성 질환(NCD)을 통합한 하이브리드형 원격 모니터링 네트워크에 자금을 지원하여 수요를 더욱 확대되고 있습니다.
유럽은 규제 측면에서 유리한 조건을 갖추고 있습니다. EU 의료기기 규정(MDR)의 조화로 국경을 넘는 인증 절차가 간소화되었으며, 확립된 보험 급여 제도가 첨단 CTG의 사용을 지원하고 있습니다. 조산아의 조기 퇴원을 위해 Masimo SafetyNet을 도입한 프랑스 병원들은 비용 대비 효과가 맞다면 원격 모니터링에 투자하는 데 긍정적인 태도를 보이고 있습니다. 중동 및 아프리카, 남미 지역은 아직 발전 단계에 있지만, 미래 전망은 밝습니다. 사하라 이남 아프리카의 디지털 헬스 관점에서 볼 때, 고정형 인프라가 갖춰지지 않은 지역에서 모바일 CTG는 ‘도약적 기술’로 자리매김하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the intrapartum monitoring devices market size was valued at USD 2.45 billion in 2025 and estimated to grow from USD 2.61 billion in 2026 to reach USD 3.55 billion by 2031, at a CAGR of 6.38% during the forecast period (2026-2031).
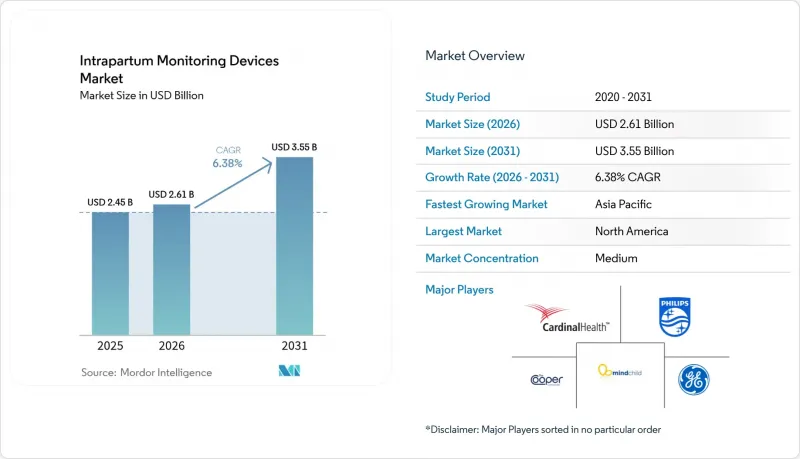
This report is Segmented by Product Type (Electrodes, Monitors), Monitoring Method (Invasive, Non-Invasive), Portability (Fixed, Portable), End-User (Hospitals, Specialty Clinics, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Intrapartum Monitoring Devices Market Trends and Insights
Rapid Adoption of Non-Invasive Fetal ECG Technology
Non-invasive fetal electrocardiography offers beat-to-beat heart-rate analysis without belts or scalp electrodes, matching or surpassing Doppler accuracy, particularly in high-BMI patients. Its freedom of movement boosts maternal satisfaction scores, a metric now tied to hospital reimbursement. Pandemic-era remote-monitoring pilots validated home-based ECG patches that transmit continuous data to clinicians, lowering exposure risk while sustaining oversight. Health-system purchasing committees thus rank mobility, comfort, and signal robustness as core criteria, pushing suppliers to embed ECG channels into wireless patch platforms. Start-ups focused on AI interpretation layer additional value by converting continuous waveforms into actionable alerts within seconds.
Rising Pre-Term Births & NICU Admissions
Worldwide, 13.4 million babies were born preterm in 2020, equivalent to 9.9% of live births . In the United States, NICU admissions rose from 8.7% in 2016 to 9.8% in 2023. Each NICU day costs USD 3,000-5,000, making early intrapartum detection financially attractive to payers . Advanced monitoring that flags decelerations or uterine tachysystole minutes earlier can reduce emergency cesareans and neurodevelopmental morbidity. The trend is amplified by women delaying childbirth; pregnancies in mothers > 35 years carry higher risks and more often trigger continuous electronic surveillance rather than intermittent auscultation.
High Capital Outlay for Advanced Central Surveillance Stations
Hospitals investing in multi-bed fetal telemetry platforms often face seven-figure budgets when integration with EHR, cybersecurity hardening, and staff re-training are included. Prisma Health's USD 41 million smart-bed deployment across 1,500 units illustrates the scale of capital commitments. Procurement tenders such as BARTS Health NHS Trust's site-wide vital-signs monitoring call for open APIs and ISO 27001 compliance, adding IT overhead. Under-funded community hospitals postpone upgrades, creating a tiered technology landscape where rural mothers receive palpation or intermittent doppler checks instead of continuous CTG.
Other drivers and restraints analyzed in the detailed report include:
- Government Mandates on Intrapartum Monitoring Standards
- Growth of High-Risk Pregnancies in Women More Than 35 Years
- Stringent FDA & EU-MDR Clinical Evidence Demands
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electrodes retained 64.88% revenue in 2025, underscoring their indispensable role in signal capture across all modalities. Yet monitors post a faster 6.89% CAGR, reflecting demand for multi-parameter, AI-ready platforms that house fetal, maternal, and uterine channels in one chassis. GE's Novii wireless patch incorporates ECG and EMG within a belt-free shell that elevates patient comfort while satisfying documentation mandates. Samsung's USD 92.4 million Sonio purchase highlights the premium on ultrasound-linked analytics that augment CTG workflows. Such integrations deliver holistic intrapartum monitoring devices market value propositions that transcend hardware replacement cycles. Electrode unit sales nonetheless rise steadily because each monitor still needs disposable or reusable transducers, preserving a large consumables revenue stream.
Second-generation monitors bundle cloud connectivity and decision support, shifting purchasing criteria from hardware specifications toward software roadmaps. EDAN's F3 fetal monitor offers on-board CTG analytics, easing interpretation load for junior staff. Vendors exploring subscription-based algorithm updates can smooth revenue while hospitals gain access to continuously improving classifications without capital refresh. The resulting convergence repositions monitors as software platforms backed by consumable electrodes, ensuring lasting traction within the intrapartum monitoring devices market.
Non-invasive systems captured 69.22% of 2025 revenue and are forecast for a 6.96% CAGR, maintaining dual leadership in size and growth. External Doppler ultrasound and tocodynamometers dominate routine obstetric care because they avoid cervical dilation and infection risk. Intrapartum monitoring devices market size gains further as new patches relay signals via Bluetooth, freeing mothers to ambulate or use birthing balls without strap readjustments. Internal scalp electrodes and intrauterine pressure catheters remain the precision gold standard when obesity, malpresentation, or signal noise impede external readings. Recent trials show internal CTG neither raises cesarean incidence nor worsens neonatal outcomes versus external monitoring, potentially broadening clinical indications. However, the need for ruptured membranes limits usage.
Hybrid telemetry arranges dual benefits: high-fidelity signals plus mobility. University of Helsinki findings on simultaneous maternal pulse recording confirm that artifact filtering prevents neonatal encephalopathy, accelerating adoption of multiparameter solutions. External platforms therefore evolve to include maternal ECG channels that auto-subtract cross-talk, reinforcing non-invasive dominance inside the intrapartum monitoring devices market.
Complete Report Scope:
- By Product Type
- Electrodes
- Intra-uterine Pressure Catheters (IUPC)
- Fetal Scalp Electrodes
- Uterine Contraction Transducers
- Fetal Heart-Rate Transducers
- Monitors
- Electrodes
- By Monitoring Method
- Invasive
- Non-Invasive
- By Portability
- Fixed
- Portable
- By End-User
- Hospitals
- Specilaty Clinics
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's 41.85% stake stems from stringent standards and high per-capita healthcare spending. Forthcoming CMS rules compel universal fetal-monitor access, and NICU admissions edging toward 10% of births intensify monitoring sophistication. Yet 2024 saw multiple rural obstetric unit shutdowns and rising malpractice premiums, pushing health systems to pilot tele-CTG hubs that extend oversight without on-site specialists. Vendor partnerships, such as Philips' collaboration with Georgia health plans for remote maternal programs, illustrate how the intrapartum monitoring devices market adapts to workforce deficits.
Asia-Pacific claims the speed crown at 7.18% CAGR, lifted by maternal mortality reduction drives and urban hospital construction booms. Governments subsidize digital health pilots that outfit district maternity wards with Bluetooth CTG linked to cloud dashboards in tertiary centers. In Japan and South Korea, AI-interpretation pilots expedite decision making, while emerging economies prioritize basic device deployment alongside midwife training. The Asian Development Bank's integrated-care grants finance hybrid maternal-NCD telemetry networks, further scaling demand.
Europe sits in a regulatory sweet spot: EU-MDR harmonization simplifies cross-border certifications, and established reimbursement structures cover advanced CTG usage. French hospitals using Masimo SafetyNet for premature newborn early discharge evidence willingness to invest in telemonitoring when cost-benefit aligns. Middle East, Africa, and South America remain nascent but promising. Sub-Saharan Africa's digital-health lens positions mobile CTG as a leapfrog technology in regions lacking fixed infrastructure.
- GE Healthcare
- Koninklijke Philips
- Medtronic
- Natus Medical
- Cardinal Health
- Analogic Corp.
- Shenzhen Mindray Bio-Medical
- Nihon Kohden Corp.
- Dragerwerk
- Arjo-Huntleigh (Huntleigh Healthcare)
- Samsung Group
- EDAN Instruments
- Cooper Surgical (The Cooper Companies)
- Stryker
- Olympus Corp.
- Bionet Co. Ltd.
- Monica Healthcare
- Nonin Medical
- Wallach Surgical Devices
- MindChild Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid adoption of non-invasive fetal ECG technology
- 4.2.2 Rising pre-term births & NICU admissions
- 4.2.3 Government mandates on intrapartum monitoring standards
- 4.2.4 Growth of high-risk pregnancies in women more than 35 yrs
- 4.2.5 AI-powered real-time labour analytics embedded in CTG systems
- 4.2.6 Reimbursement uplifts for remote labour wards in Sub-Saharan Africa
- 4.3 Market Restraints
- 4.3.1 High capital outlay for advanced central surveillance stations
- 4.3.2 Stringent FDA & EU-MDR clinical evidence demands
- 4.3.3 Cyber-security liabilities of Wi-Fi enabled CTG monitors
- 4.3.4 Shortage of trained obstetric nurses
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Electrodes
- 5.1.1.1 Intra-uterine Pressure Catheters (IUPC)
- 5.1.1.2 Fetal Scalp Electrodes
- 5.1.1.3 Uterine Contraction Transducers
- 5.1.1.4 Fetal Heart-Rate Transducers
- 5.1.2 Monitors
- 5.1.1 Electrodes
- 5.2 By Monitoring Method
- 5.2.1 Invasive
- 5.2.2 Non-Invasive
- 5.3 By Portability
- 5.3.1 Fixed
- 5.3.2 Portable
- 5.4 By End-User
- 5.4.1 Hospitals
- 5.4.2 Specilaty Clinics
- 5.4.3 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 GE Healthcare
- 6.3.2 Koninklijke Philips N.V.
- 6.3.3 Medtronic plc
- 6.3.4 Natus Medical Inc.
- 6.3.5 Cardinal Health
- 6.3.6 Analogic Corp.
- 6.3.7 Shenzhen Mindray Bio-Medical
- 6.3.8 Nihon Kohden Corp.
- 6.3.9 Dragerwerk AG & Co. KGaA
- 6.3.10 Arjo-Huntleigh (Huntleigh Healthcare)
- 6.3.11 Samsung Medison
- 6.3.12 EDAN Instruments
- 6.3.13 Cooper Surgical (The Cooper Companies)
- 6.3.14 Stryker Corp.
- 6.3.15 Olympus Corp.
- 6.3.16 Bionet Co. Ltd.
- 6.3.17 Monica Healthcare
- 6.3.18 Nonin Medical
- 6.3.19 Wallach Surgical Devices
- 6.3.20 MindChild Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


