

|
시장보고서
상품코드
2122489
재생에너지 분야 복합재료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Composite Materials In Renewable Energy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
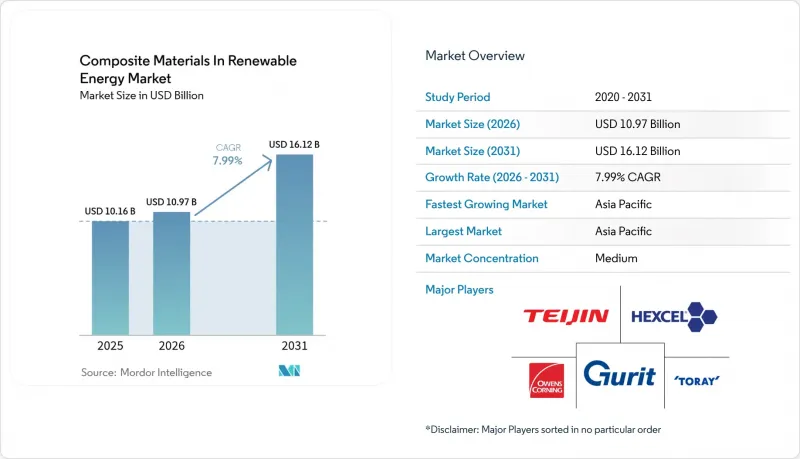
에 의하면, 재생에너지 분야 복합재료 시장 규모는 2025년에 101억 6,000만 달러로 평가되었습니다. 2026년 109억 7,000만 달러에서 2031년까지 161억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 7.99%를 나타낼 전망입니다.

본 보고서에서는 산업을 섬유 유형별(유리섬유 강화 플라스틱(GFRP), 기타), 수지 매트릭스별(에폭시, 폴리에스터, 기타), 제조 공정별(진공 주입, 프리프레그/오토클레이브, 기타),용도별(풍력 발전, 태양광 발전, 기타), 지역별(아시아태평양, 북미, 기타)로 분류하고 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 재생에너지 분야 복합재료 시장 동향 및 인사이트
금속 구조물에 비해 경량화
복합재료로의 대체를 통해 해상 풍력 발전, 수소 탱크, 조력 발전 설비의 구조물 질량이 감소하여 적재 효율이 향상되고, 운송 물류 부담이 경감되고 있습니다. 조력 발전용 블레이드의 무게를 13.76% 줄임으로써, 강철 대체품에 비해 발전 출력이 46.1% 향상되었습니다. 항공우주 부문에서는 라이너리스형 V형 탄소 복합재료 탱크의 개발이 액체 수소 추진으로의 전환을 뒷받침하고 있으며, 간접적으로 재생에너지용 등급 섬유에 대한 수요를 증가시키고 있습니다. 미쓰비시 화학의 C/SiC 세라믹 매트릭스 복합재료는 1,500°C를 견딜 수 있어, 헬리오스태트 수광기나 핵융합로 하드웨어로의 길을 열어주고 있습니다. 이러한 진전은 재생에너지 시장에서 복합재료가 왜 고온 및 부식성 환경에서 알루미늄과 강철을 계속해서 대체하고 있는지를 여실히 보여줍니다.
풍력 터빈 블레이드의 대형화에 따른 수요 증가
지멘스 에너지의 로터 직경 276m, 21MW 프로토타입은 블레이드 길이가 150m에 가까워짐에 따라, 유리 섬유만으로는 달성할 수 없는 강성 대 중량비 목표를 충족하기 위해 탄소섬유로 만든 스퍼 캡이 필요함을 보여줍니다. 고인성 에폭시 수지를 이용한 접합을 가능하게 한 부문화된 블레이드 구조는 공기역학적 탄성적 무결성을 유지하면서 운송을 용이하게 합니다. ZEBRA 컨소시엄은 Arkema사의 ‘Elium’ 수지를 사용하여 세계 최대 규모의 완전 재활용 가능한 열가소성 수지 블레이드 개발을 완료했습니다. 이는 폐쇄형 플랫폼에 대한 산업적 실용화가 준비되었음을 보여줍니다. 천연섬유와 합성 섬유를 혼합한 하이브리드 적층 구조는 내충격성을 향상시키는 동시에 탄소 배출량을 줄여줍니다. 이는 2050년까지 150GW를 달성하겠다는 EU의 해상 풍력 발전 목표와 부합하며, 이에 따라 전 세계 탄소섬유 수요가 두 배로 증가할 가능성이 있습니다.
연구개발비와 금형 제조비가 막대한 설비 투자
자동 섬유 배치 라인은 1대당 500만-1,000만 달러, 100미터를 초과하는 블레이드용 금형은 1세트당 200만 달러를 초과하기 때문에 투자 회수까지 수년 동안 자본이 묶이게 됩니다. 인증 프로그램은 대개 5-7년이 소요되어, 중견 혁신 기업들의 운전 자금 수요가 장기화됩니다. 헥셀(Hexel)사가 2025년에 실시한 3억 미달러 규모의 사채 발행은 공정 기술 리더십을 유지하는 데 필요한 자금력을 여실히 보여줍니다. 열가소성 수지의 채택은 비용을 더욱 상승시킵니다. 이는 오븐, 프레스기, 용접 장비가 열경화성 수지 생산 라인과는 다르기 때문에 병행하여 설비를 구축해야 할 필요가 생겨 중소 제조업체의 경쟁력을 저해하기 때문입니다.
부문별 분석
이 부문은 2025년에 가장 큰 매출 기여도를 보였으며, 재생에너지 시장 내 복합재료 점유율 중 GFRP가 54.70%를 차지했습니다. 탄소섬유의 연평균 성장률(CAGR) 8.39%는 로터 직경이 120m를 초과하는 사례를 반영한 것으로, 이 경우 강성과 피로 성능이 5-10배에 달하는 비용 프리미엄을 정당화합니다. SGL Carbon의 80m 이상 블레이드 공급 계약은 항공우주 부문에서 에너지 부문으로의 수직 통합 움직임을 보여줍니다. 현무암 섬유와 천연섬유를 혼합한 하이브리드 적층재는 내장된 탄소 사용량을 줄이면서도 필요한 탄성 계수를 유지하여, 중형 터빈 등급의 선택지를 확대되고 있습니다. 독일에서 진행 중인 바이오 유래 리그닌 섬유에 대한 연구는 향후 비용 절감 수단이 될 수 있지만, 상업적 규모의 생산량은 아직 제한적입니다. 재활용 탄소섬유는 기계적 재활용을 통해 원래 인장 강도의 60-70%가 유지되므로, 2차 구조재로 채택되는 사례가 꾸준히 증가하고 있습니다. 이로 인해 원료의 다양화가 진행되고, 원료 가격 변동도 완화되고 있습니다.
에폭시 수지는 성숙한 공급망과 높은 내피로성으로 인해 2025년에도 매출 점유율 45.20%를 유지했습니다. 그러나 각 OEM 업체들이 순환형 경제 요건을 충족하기 위해 경쟁하는 가운데, 바이오 수지와 재생 수지는 연평균 성장률(CAGR) 7.88%로 확대되고 있습니다. 다우(Dow)와 베스타스(Vestas)는 층간 인성을 높이는 동시에 신속한 풀트라지션 가공을 가능하게 하는 폴리우레탄제 스퍼 캡용 화학 조성에 대한 인증을 획득했습니다. 시코민(Shikomin)의 SGi 128 바이오 에폭시 겔코트는 재생 가능한 원료를 35% 함유하고 있어, 우수한 내화성을 갖춘 솔루션을 실현하고 있습니다. 엘리움(Elium) 등의 열가소성 매트릭스는 수복성 및 용융 재활용이라는 추가적인 이점을 제공하여, 재생 에너지 시장에서 복합재료를 폐쇄형 순환 경제로 전환시키고 있습니다.
지역별 분석
아시아태평양은 2025년 재생에너지 분야 복합재료 시장 규모에서 44.30%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.03%로 성장할 전망입니다. 중국은 엔드투엔드 공급망을 보유하고 있어 이 지역의 중심적인 존재로 자리 잡고 있지만, 2024년 재활용 기준으로 인해 규정 준수 비용이 증가하고 있어, 이에 따라 현지 기반의 통합형 대기업들이 유리한 입지를 점하고 있습니다. 인도의 24억 달러 규모 ‘수소 미션’과 방위 부문에서의 탄소섬유 추진은 국내 생산에 대한 인센티브를 강화하고 있습니다. 일본의 페로브스카이트 로드맵은 유연한 복합재 기판을 활용하여 2040년까지 38.3GW를 달성하는 것을 목표로 하고 있으며, 이러한 전환은 전 세계 태양광 모듈 구조를 재편할 가능성이 있습니다. 한국은 조선 노하우를 활용해 해상 풍력 발전용 복합재 시장에 진출하고 있는 반면, 호주는 내륙 저수지에서 부유식 태양광 발전 실증 실험을 진행하고 있어 지역별 활용 사례의 다양성을 보여주고 있습니다.
북미에서는 ‘인플레이션 감축법’에 따른 3,690억 달러 규모의 자금 지원 혜택을 받고 있으며, 국내 조달 비율에 따른 우대 조치가 텍사스주, 뉴욕주, 온타리오주에서의 공장 확장을 뒷받침하고 있습니다. GE Vernova의 6억 달러 규모 제조 거점 확충은 태평양을 횡단하는 물류 리스크를 줄이는 리쇼어링 움직임을 상징합니다. 캐나다의 항공우주용 복합재료 클러스터는 오토클레이브 외 성형법을 조력 터빈 외피에 적용하는 것을 지원하고 있는 반면, 멕시코에서는 비용 경쟁력이 있는 노동력을 바탕으로 태양광 랙 수출용 인발 성형 업체들이 모여들고 있습니다. 이 지역의 과제는 수입에 대한 과도한 의존을 방지하기 위해 섬유 생산을 확대하는 것이지만, 2027년까지 이 격차를 해소하는 것을 목표로 하는 몇 가지 합작 사업이 진행 중입니다.
유럽은 규제 측면에서 영향력을 발휘하며, 재활용성 및 내재 탄소량에 관한 세계 표준을 주도하고 있습니다. ZEBRA 프로젝트에서 열가소성 수지 블레이드의 성공은 유럽을 기술의 선구자로 자리매김하게 했습니다. 독일의 리그닌 섬유 시범 생산 라인은 연구 개발 분야의 리더십을 상징하는 반면, 프랑스는 항공우주 분야의 전문 지식을 활용하여 고탄성률 프리프레그의 개선을 추진하고 있습니다. 영국 국립 복합재료 센터(National Composites Centre)의 SusWIND 프로그램은 여러 재활용 채널의 유효성을 입증하여 OEM에 설계 유연성을 제공합니다. 북해와 발트해 지역의 해상 풍력 발전 확대가 섬유 수요의 지속적인 증가를 견인하고 있지만, 에너지 비용의 급등으로 인해 수익성을 유지하기 위해서는 자동화가 필수적입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the composite materials in the renewable energy market size was valued at USD 10.16 billion in 2025 and estimated to grow from USD 10.97 billion in 2026 to reach USD 16.12 billion by 2031, at a CAGR of 7.99% during the forecast period (2026-2031).
This report Segments the Industry by Fibre Type (Glass-Fibre-Reinforced Plastics (GFRP), and More), Resin Matrix (Epoxy, Polyester, and More), Manufacturing Process (Vacuum Infusion, Prepreg/Autoclave, and More), Application (Wind Power, Solar Power, and More), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Composite Materials In Renewable Energy Market Trends and Insights
Reduced Weight Versus Metallic Structures
Composite substitution cuts structural mass in offshore wind, hydrogen tanks, and tidal devices, boosting payload efficiency and easing transport logistics. Weight savings of 13.76% on tidal blades have lifted power output by 46.1% versus steel alternatives. In aerospace, the development of liner-less Type V carbon-composite tanks supports the transition to liquid-hydrogen propulsion, indirectly increasing demand for renewable-grade fibres. Mitsubishi Chemical's C/SiC ceramic matrix composite endures 1,500 °C, opening paths for heliostat receivers and fusion-reactor hardware. These advances underline why the composite materials in the renewable energy market continue to displace aluminum and steel in high-temperature, corrosive environments.
Growing Demand for Longer Wind-Turbine Blades
Siemens Energy's 21 MW prototype with a 276 m rotor diameter illustrates how blade lengths nearing 150 m require carbon-fibre spar caps for stiffness-to-weight targets unattainable with glass fibre alone. Segmented blade architectures, enabled by high-toughness epoxy joints, ease transport while maintaining aeroelastic integrity. The ZEBRA consortium completed the world's largest fully recyclable thermoplastic blade using Arkema's Elium resin, signalling industrial readiness for closed-loop platforms. Hybrid lay-ups that mix natural and synthetic fibres improve impact resistance and lower embodied carbon, aligning with EU offshore wind targets of 150 GW by 2050 that could double global carbon-fibre demand.
High Research and Development and Tooling CAPEX
Automated fibre-placement lines cost USD 5-10 million each, while molds for >100 m blades exceed USD 2 million per set, tying up capital for years before payback. Certification programs often run 5-7 years, stretching working-capital needs for mid-tier innovators. Hexcel's USD 300 million bond issue in 2025 exemplifies the financial firepower required to retain process-technology leadership. Thermoplastic adoption compounds costs, since ovens, presses, and welding equipment differ from thermoset lines, creating parallel asset footprints that hamper small manufacturers' competitiveness.
Other drivers and restraints analyzed in the detailed report include:
- Government Inclination Towards Adoption of Renewable Energy
- Commercialization of Thermoplastic Recyclable Blade Platforms
- Recycling & Landfill-Ban Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The segment generated the largest revenue contribution in 2025, when GFRP held 54.70% of composite materials in the renewable energy market share. Carbon fibre's 8.39% CAGR reflects rotor diameters that eclipse 120 m, where stiffness and fatigue performance justify its 5-10X cost premium. SGL Carbon's supply agreements for 80 m-plus blades illustrate vertical moves into energy from aerospace. Fibre-hybrid lay-ups blending basalt and natural fibre reduce embodied carbon yet maintain required modulus, expanding options for mid-range turbine classes. Bio-based lignin fibre research in Germany offers a future cost-reduction lever, although commercial volumes remain limited. Recycled carbon fibre is steadily integrating into secondary structures as mechanical recycling preserves 60-70% original tensile strength, further diversifying feedstocks and tempering raw material price swings.
Epoxy maintained a 45.20% revenue share in 2025 thanks to mature supply chains and high fatigue resistance. Yet bio-resins and recycled resins are expanding at an 7.88% CAGR as OEMs race to satisfy circular-economy mandates. Dow and Vestas have qualified polyurethane spar-cap chemistries that enable rapid pultrusion while elevating interlaminar toughness. Sicomin's SGi 128 bio-epoxy gel coat demonstrates fire-safe solutions with 35% renewable content. Thermoplastic matrices such as Elium offer the added benefit of repairability and melt recycling, pivoting the composite materials in the renewable energy market toward closed-loop economics.
Complete Report Scope:
- By Fibre Type
- Glass-Fibre-Reinforced Plastics (GFRP)
- Carbon-Fibre-Reinforced Plastics (CFRP)
- Fibre-Reinforced Polymers (FRP)
- Other Fibre Types (Hybrid and Other Fibres, etc.)
- By Resin Matrix
- Epoxy
- Polyester
- Polyurethane
- Thermoplastic
- Bio-resins and Recycled Resins
- By Manufacturing Process
- Vacuum Infusion
- Prepreg/Autoclave
- Pultrusion
- Automated Fibre Placement / 3-D Printing
- Compression Moulding (SMC, BMC)
- By Application
- Wind Power
- Solar Power
- Hydroelectricity
- Other Applications (Green-Hydrogen & Energy-Storage Vessels)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 44.30% of the composite materials in the renewable energy market size in 2025 and is on track for an 8.03% CAGR through 2031. China anchors the region with end-to-end supply chains, yet its 2024 recycling standards raise compliance costs that favor integrated local champions. India's USD 2.4 billion Hydrogen Mission and defense-sector carbon-fibre push reinforce domestic production incentives. Japan's perovskite roadmap aims for 38.3 GW by 2040 via flexible composite substrates, a pivot that may recalibrate global solar module architectures. South Korea leverages shipbuilding know-how to enter offshore wind composites, while Australia tests floating solar on inland reservoirs, showcasing regional diversity in end-use cases.
North America benefits from USD 369 billion of Inflation Reduction Act funding, with domestic-content bonuses catalyzing plant expansion in Texas, New York, and Ontario. GE Vernova's USD 600 million manufacturing buildout exemplifies reshoring moves that cut trans-Pacific logistics risk. Canada's aerospace-composite cluster supports the transfer of out-of-autoclave methods to tidal-turbine shells, while Mexico's cost-competitive labor pool draws pultruders for solar-rack exports. The region's challenge is scaling fibre production to prevent over-dependence on imports, a gap several joint ventures aim to close by 2027.
Europe wields regulatory clout, steering global norms on recyclability and embodied carbon. The ZEBRA project's thermoplastic blade success positions the continent as a technology frontrunner. Germany's lignin-fibre pilot lines symbolize R&D leadership, whereas France leverages aerospace heritage to refine high-modulus prepregs. The UK National Composites Centre's SusWIND program validates multiple recycling routes, giving OEMs design flexibility. Offshore wind buildout in the North Sea and Baltic drives sustained fibre demand, though high energy costs compel automation to defend margins.
- Changzhou Tiansheng New Materials Co. Ltd
- EPSILON Composite SAS
- EURO-COMPOSITES
- Evonik Industries AG
- Exel Composites
- GE Vernova
- Gurit Services AG
- Jiangsu Hengshen Co.,Ltd
- Hexcel Corporation
- HS HYOSUNG ADVANCED MATERIALS
- LM WIND POWER
- Mitsubishi Chemical Group Corporation
- Norco Composites & GRP
- Owens Corning
- Plastic Reinforcement Fabrics Ltd
- SGL Carbon
- Siemens Gamesa Renewable Energy, S.A.U
- Solvay
- TEIJIN LIMITED
- TORAY INDUSTRIES, INC.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Reduced weight versus metallic structures
- 4.2.2 Growing demand for longer wind-turbine blades
- 4.2.3 Government inclination towards the adoption of renwable energy
- 4.2.4 Commercialisation of thermoplastic recyclable blade platforms
- 4.2.5 Rising adoption of 3-D printed composite parts in floating solar & tidal devices
- 4.3 Market Restraints
- 4.3.1 High research and development and tooling CAPEX
- 4.3.2 Recycling & landfill-ban compliance costs
- 4.3.3 Concerns regarding the durability and fire resistance of some composite materials
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Fibre Type
- 5.1.1 Glass-Fibre-Reinforced Plastics (GFRP)
- 5.1.2 Carbon-Fibre-Reinforced Plastics (CFRP)
- 5.1.3 Fibre-Reinforced Polymers (FRP)
- 5.1.4 Other Fibre Types (Hybrid and Other Fibres, etc.)
- 5.2 By Resin Matrix
- 5.2.1 Epoxy
- 5.2.2 Polyester
- 5.2.3 Polyurethane
- 5.2.4 Thermoplastic
- 5.2.5 Bio-resins and Recycled Resins
- 5.3 By Manufacturing Process
- 5.3.1 Vacuum Infusion
- 5.3.2 Prepreg/Autoclave
- 5.3.3 Pultrusion
- 5.3.4 Automated Fibre Placement / 3-D Printing
- 5.3.5 Compression Moulding (SMC, BMC)
- 5.4 By Application
- 5.4.1 Wind Power
- 5.4.2 Solar Power
- 5.4.3 Hydroelectricity
- 5.4.4 Other Applications (Green-Hydrogen & Energy-Storage Vessels)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Changzhou Tiansheng New Materials Co. Ltd
- 6.4.2 EPSILON Composite SAS
- 6.4.3 EURO-COMPOSITES
- 6.4.4 Evonik Industries AG
- 6.4.5 Exel Composites
- 6.4.6 GE Vernova
- 6.4.7 Gurit Services AG
- 6.4.8 Jiangsu Hengshen Co.,Ltd
- 6.4.9 Hexcel Corporation
- 6.4.10 HS HYOSUNG ADVANCED MATERIALS
- 6.4.11 LM WIND POWER
- 6.4.12 Mitsubishi Chemical Group Corporation
- 6.4.13 Norco Composites & GRP
- 6.4.14 Owens Corning
- 6.4.15 Plastic Reinforcement Fabrics Ltd
- 6.4.16 SGL Carbon
- 6.4.17 Siemens Gamesa Renewable Energy, S.A.U
- 6.4.18 Solvay
- 6.4.19 TEIJIN LIMITED
- 6.4.20 TORAY INDUSTRIES, INC.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


