

|
시장보고서
상품코드
2122493
목질 패널 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Wood-based Panel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 목질 패널 시장 규모는 4억 3,436만 입방미터로 추정되고 2025년 4억 1,999만 입방미터로부터 확대해, 2031년에는 5억 1,379만 입방미터에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 3.42%가 될 것으로 전망됩니다.

본 보고서는 제품 유형별(중밀도 섬유판(MDF)/고밀도 섬유판(HDF), 배향성 스트랜드 보드(OSB), 파티클 보드, 합판, 활엽수, 기타),용도별(가구, 건설, 포장, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 수량(세제곱미터) 기준으로 제시되어 있습니다.
세계의 목질 패널 시장 동향 및 인사이트
신흥국의 건설 산업 호황기
아시아태평양 및 라틴아메리카 일부 국가의 정부는 인프라 지출을 두 배로 늘리고 있어, 합판, MDF, OSB에 대한 지속적인 수요를 창출하고 있습니다. 인도의 연방 고속도로 계획과 인도네시아의 신수도 건설 프로젝트는 수년에 걸친 조달 주기를 뒷받침하고 있는 반면, 튀르키예의 지진 복구로 인해 2024년 초 러시아산 제재목 수입량이 3배인 29만 2,200m³에 달했습니다. 단기적인 수요 둔화에도 불구하고, 각 제조업체들은 향후 공급 부족에 대비해 원목을 비축하고 있으며, 인도의 수입량이 2분기 만에 40% 급증한 것이 그 증거입니다. 스미토모 임업 등 일본의 복합 기업들은 5년 이내에 동남아시아에서 7,000세대의 주택을 건설하겠다고 약속하며, 해당 지역의 주택 건설 계획에 대한 자신감을 드러내고 있습니다. 이러한 동향으로 인해 적어도 2028년까지는 구조용 패널 전체 소비가 상승세를 보일 것으로 확실시되고 있습니다.
가구 전자상거래 붐
온라인 가구 판매 증가로 지리적 장벽이 낮아지고, 모델 교체 주기가 단축되는 동시에 소량 생산이 촉진되고 있으며, 이는 유연한 패널 공급업체에게 유리한 상황입니다. 2024년 4월 미국의 주택용 가구 수주량은 전년 동월 대비 22% 증가했으나, 국내 목재 가구 출하량은 2000년 수준보다 48% 낮습니다. 수입 지향적인 밸류체인은 여전히 파티클보드, MDF, 합판 등의 기판에 크게 의존하고 있어 패널에 대한 대량 수요를 뒷받침하고 있습니다. 말레이시아는 전자상거래 물류를 활용하여 2021년 목재 수출액을 227억 링깃까지 끌어올렸으며, 그중 합판이 최대 품목이 되었습니다. 저스트-인-타임(JIT) 라미네이트 가공 및 디지털 프린트 장식을 납품할 수 있는 기동성이 높은 공장은 이처럼 급변하는 유통 채널에서 계속해서 시장 점유율을 확대되고 있습니다.
포름알데히드 배출 규제 강화
EU는 2026년 8월부터 실내 공기 중 포름알데히드 농도를 0.062mg/m³로 제한할 방침이며, 이에 따라 제재소는 비용이 15-25% 더 높은 무첨가 포름알데히드 수지로 전환할 수밖에 없게 됩니다. 독일이 EU 규제를 따르기로 함에 따라 국내 예외 조치는 폐지되었습니다. 한편, 미국 환경보호청(EPA)의 규제치는 유사한 수준에 머물러 있어 규제를 회피할 여지는 거의 없습니다. 연속 프레스 라인이나 대체 접착제 시스템에 대한 설비 투자는 특히 이미 낮은 마진으로 운영되고 있는 중소 파티클보드 공장에서 현금 흐름을 압박하고 있습니다.
부문별 분석
세계 MDF/HDF 출하량은 연평균 성장률(CAGR) 4.12%로 확대될 것으로 예측되며, 이는 목질 패널 시장 전체의 성장률을 상회할 것으로 보입니다. 중국은 여전히 전 세계 MDF 공급량의 약 60%를 차지하고 있지만, 베트남과 동유럽의 신규 공장들이 저비용 섬유, 자동 샌딩 라인, 디지털 프린팅을 통한 장식 등을 활용하여 그 격차를 좁혀가고 있습니다. 메콩 우드(Mekong Wood)가 캄케에 설치한 60만 m3 규모의 프레스 설비는 2024년 7월에 가동을 시작했으며, CARB 기준을 준수하는 보드를 찾는 일본 수입업체를 즉시 주요 고객으로 삼았습니다. 성숙한 경제권에서는 지속가능성 인증을 통해 굽힘 강도를 저하시키지 않으면서 최대 24%의 재활용 섬유를 배합한 MDF에 대한 수요가 증가하고 있습니다.
합판은 외벽 하부 마감재나 캐비닛 골조 등 폭넓은 용도로 사용되기 때문에 여전히 27.85%라는 압도적인 점유율을 유지하고 있습니다. 한편, OSB의 출하량은 SIP(구조용 단열 패널) 및 건축 기준을 준수하는 전단 패널에 대한 수요를 배경으로 더욱 빠르게 증가하고 있습니다. 또한, 파티클보드는 합리적인 가격대의 가구 시장에서 여전히 중요한 위치를 차지하고 있습니다. 활엽수 합판은 EUDR(EU 목재 규정)에 따른 공급 부족에도 불구하고, 이국적인 단판을 활용하여 고급 주방 및 RV(레크리에이션 차량) 내장 시장을 휩쓸고 있습니다. 생산자들은 원료의 다각화를 추진하고 있으며, 인도에서는 플랜테이션산 티크 목재의 잔재물을, 말레이시아에서는 고무나무를 사용함으로써 원목 비용 절감과 수명 주기 평가 향상을 도모하고 있습니다.
지역별 분석
아시아태평양은 2025년 출하량의 52.12%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 3.85%로 성장할 전망입니다. 중국의 합판 수출은 아세안(ASEAN) 및 중동으로의 관세 우대 조치에 힘입어 2024년에는 1,327만 m3, 52억 7,000만 달러에 달했습니다. 유럽의 패널 제조업체들은 호불호가 엇갈리는 상황에 직면해 있습니다. 제재소는 포름알데히드 무함유 수지로 설비를 교체하고 EUDR 추적성 시스템을 도입해야 하는 압박을 받고 있어, 이로 인해 비용 곡선이 상승하고 있습니다. 그러나 독일과 프랑스에서 팬데믹 이후 발생한 리모델링 붐에 더해, 패널 잔재물에 대한 바이오매스 보조금이 수요를 뒷받침하고 있습니다. 크로노스팬(Chronospan)사의 리브네에 위치한 70만 m³ 규모의 OSB 생산 라인 등 동유럽의 공장들은 침엽수림 및 EU 최종 소비자와 인접해 있어 공급 격차를 메우기에 유리한 위치에 있습니다.
북미에서는 양극화된 추세가 나타나고 있습니다. 2023년 구조용 패널 생산량은 OSB의 경우 4.6%, 합판의 경우 1.0% 감소했습니다. 미국 남부의 제재소는 낮은 원목 가격과 개선된 연속 프레스 기계를 활용하여 잉여 OSB를 유럽으로 수출하고 있습니다. 브리티시컬럼비아주에서는 원목 가격의 급등과 산불로 인한 가동 중단을 배경으로 생산 능력 합리화가 진행되고 있습니다. 브라질을 필두로 한 라틴아메리카는 신흥 공급 거점으로 부상하고 있습니다. 풍부한 소나무 조림지와 환율상의 우위를 바탕으로 가격 경쟁력 있는 수출이 가능한 한편, 조립식 사회주택 계획의 진전에 따라 국내 소비도 확대되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the wood-based panel market size in 2026 is estimated at 434.36 million cubic meters, growing from 2025 value of 419.99 million cubic meters with 2031 projections showing 513.79 million cubic meters, growing at 3.42% CAGR over 2026-2031.
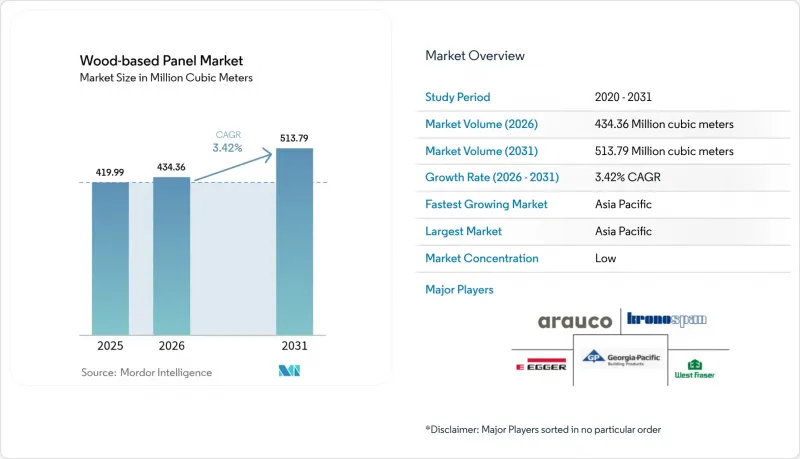
This report is Segmented by Product Type (Medium Density Fiberboard (MDF)/High-Density Fiberboard (HDF), Oriented Strand Board (OSB), Particleboard, Plywood, Hardwood, and Other Types), Application (Furniture, Construction, Packaging, and Other), and Geography (Asia Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Million Cubic Meters).
Global Wood-based Panel Market Trends and Insights
Construction Up-cycle in Emerging Economies
Governments across Asia-Pacific and parts of Latin America are doubling infrastructure outlays, triggering sustained demand for plywood, MDF, and oriented strand board. India's federal highway program and Indonesia's new capital project underpin multi-year procurement cycles, while Turkey's earthquake reconstruction tripled imports of Russian sawn timber to 292,200 m3 in early 2024. Manufacturers are stockpiling logs despite near-term demand softness to hedge against future supply squeezes, as evidenced by India's 40% import surge over two quarters. Japanese conglomerates such as Sumitomo Forestry are committing to building 7,000 Southeast-Asian homes within five years, signaling confidence in regional housing pipelines. These developments cement an upward consumption trajectory across structural panels through at least 2028.
Furniture E-commerce Boom
Rising online furniture sales reduce geographic barriers, prompting quicker model turnover and small-lot production that favors flexible panel suppliers. U.S. residential furniture orders rose 22% year-on-year in April 2024, even as domestic wood-furniture shipments are 48% below 2000 levels. Import-oriented value chains still depend heavily on particleboard, MDF, and plywood substrates, sustaining bulk panel volumes. Malaysia leveraged e-commerce logistics to lift wood exports to RM 22.7 billion in 2021, with plywood the top item. Agile mills capable of just-in-time lamination and digital-print decor delivery continue capturing share within this fast-moving channel.
Formaldehyde-Emission Regulations Tightening
The EU will cap indoor-air formaldehyde at 0.062 mg/m3 from August 2026, compelling mills to switch to no-added-formaldehyde resins that cost 15-25% more. Germany's harmonization with the EU rule eliminates domestic carve-outs, while U.S. EPA limits remain at similar thresholds, leaving little room for avoidance. Capital upgrades to continuous-press lines and alternative adhesive systems squeeze cash flows, especially at smaller particleboard facilities that already operate on slim spreads.
Other drivers and restraints analyzed in the detailed report include:
- Circular-Economy Mandates Favoring Engineered Wood
- Rapid Uptake of OSB-based SIPs in Modular Housing
- EU Deforestation Regulation Compliance Burden
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Global MDF/HDF shipments are projected to expand at a 4.12% CAGR, outpacing overall wood-based panel market growth. China continues to supply roughly 60% of the world's MDF, yet new mills in Vietnam and Eastern Europe are closing distance through lower-cost fiber, automated sanding lines, and digital-print decors. Mekong Wood's 600,000 m3 press in Cam Khe entered service in July 2024, immediately targeting Japanese importers seeking CARB-compliant board. In mature economies, sustainability labeling steers demand toward MDF blended with up to 24% recycled fiber without compromising bending strength.
Plywood retains a commanding 27.85% share thanks to universality in sheathing and cabinet carcasses. Yet OSB volumes are rising faster on the back of SIPs and code-compliant shear panels, while particleboard holds relevance in value-priced furniture. Hardwood plywood captures premium kitchen and RV interiors, leveraging exotic veneers despite supply tightness linked to the EUDR. Producers are diversifying feedstocks, using plantation teak offcuts in India and rubberwood in Malaysia to cut log costs and improve lifecycle scores.
Complete Report Scope:
- By Product Type
- Medium Density Fiberboard (MDF)/High-Density Fiberboard (HDF)
- Oriented Strand Board (OSB)
- Particleboard
- Plywood
- Hardwood
- Other Types
- By Application
- Furniture
- Residential
- Commercial
- Construction
- Floor and Roof
- Wall
- Door
- Other Construction (Decor, Frames, Accessories)
- Packaging
- Other (Artistry, Industrial Prototyping, Toys)
- Furniture
- By Geography
- Asia Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Nordic Countries
- Turkey
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- Egypt
- South Africa
- Nigeria
- Rest of Middle-East and Africa
- Asia Pacific
Geography Analysis
Asia-Pacific generated 52.12% of 2025 shipments and is set to expand at a 3.85% CAGR through 2031. China's plywood exports reached 13.27 million m3 valued at USD 5.27 billion in 2024, bolstered by tariff concessions into ASEAN and the Middle East. Europe's panel makers confront mixed conditions. Mills must retrofit formaldehyde-free resins and implement EUDR tracing, elevating cost curves. Yet post-pandemic renovation booms in Germany and France, plus biomass subsidies for panel offcuts, cushion demand. Eastern European plants, such as Kronospan's 700,000 m3 OSB line in Rivne, enjoy proximity to conifer stands and EU end-users, positioning them to backfill supply gaps.
North America exhibits bifurcated trends. Structural panel output fell 4.6% for OSB and 1.0% for plywood in 2023. Mills in the U.S. South leverage low stumpage and upgraded continuous presses to export surplus OSB to Europe. British Columbia capacity rationalization continues due to stumpage hikes and wildfire disruptions. Latin America, led by Brazil, is the emergent supply base; abundant Pinus plantations and currency advantages permit price-competitive exports, while domestic consumption grows alongside prefabricated social housing schemes.
- Arauco
- Boise Cascade
- CenturyPly
- Dexco
- Dongwha Group
- Egger
- Georgia-Pacific
- Greenpanel Industries Limited
- Kastamonu Entegre
- Kronoplus Limited
- Langboard Inc.
- Louisiana-Pacific Corporation
- Pfleiderer
- Roseburg Forest Products
- Swiss Krono Group
- West Fraser
- Weyerhaeuser Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Construction Up-Cycle in Emerging Economies
- 4.2.2 Furniture E-Commerce Boom
- 4.2.3 Circular-Economy Mandates Favouring Engineered Wood
- 4.2.4 Transparent-Wood Facades and Automotive Glazing Adoption
- 4.2.5 Rapid Uptake of OSB-Based SIPs in Modular Housing
- 4.3 Market Restraints
- 4.3.1 Formaldehyde-Emission Regulations Tightening
- 4.3.2 Volatile Log and Fibre Costs
- 4.3.3 EU Deforestation Regulation (EUDR) Compliance Burden
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Medium Density Fiberboard (MDF)/High-Density Fiberboard (HDF)
- 5.1.2 Oriented Strand Board (OSB)
- 5.1.3 Particleboard
- 5.1.4 Plywood
- 5.1.5 Hardwood
- 5.1.6 Other Types
- 5.2 By Application
- 5.2.1 Furniture
- 5.2.1.1 Residential
- 5.2.1.2 Commercial
- 5.2.2 Construction
- 5.2.2.1 Floor and Roof
- 5.2.2.2 Wall
- 5.2.2.3 Door
- 5.2.2.4 Other Construction (Decor, Frames, Accessories)
- 5.2.3 Packaging
- 5.2.4 Other (Artistry, Industrial Prototyping, Toys)
- 5.2.1 Furniture
- 5.3 By Geography
- 5.3.1 Asia Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Malaysia
- 5.3.1.6 Thailand
- 5.3.1.7 Indonesia
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Spain
- 5.3.3.6 Nordic Countries
- 5.3.3.7 Turkey
- 5.3.3.8 Russia
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Qatar
- 5.3.5.4 Egypt
- 5.3.5.5 South Africa
- 5.3.5.6 Nigeria
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Arauco
- 6.4.2 Boise Cascade
- 6.4.3 CenturyPly
- 6.4.4 Dexco
- 6.4.5 Dongwha Group
- 6.4.6 Egger
- 6.4.7 Georgia-Pacific
- 6.4.8 Greenpanel Industries Limited
- 6.4.9 Kastamonu Entegre
- 6.4.10 Kronoplus Limited
- 6.4.11 Langboard Inc.
- 6.4.12 Louisiana-Pacific Corporation
- 6.4.13 Pfleiderer
- 6.4.14 Roseburg Forest Products
- 6.4.15 Swiss Krono Group
- 6.4.16 West Fraser
- 6.4.17 Weyerhaeuser Company
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


