|
시장보고서
상품코드
2122498
성병(STD) 진단 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)STD Diagnostics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 성병(STD) 진단 시장 규모는 2025년에 181억 8,000만 달러로 평가되었습니다. 2026년 194억 2,000만 달러에서 2031년까지 270억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 6.84%를 나타낼 전망입니다.

본 보고서는 검사 유형별(클라미디아, 임질, 매독, 기타), 기술별(면역측정법, 분자진단, 차세대 염기서열 분석, 기타), 검사 실시 장소별(중앙 검사실·병원 검사실, 기타), 최종 사용자별(병원 및 클리닉, 기타),지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 성병(STD) 진단 시장 동향 및 인사이트
전 세계 성병(STD) 유병률 상승
세계보건기구(WHO) 기록에 따르면, 2024년에는 매일 100만 건이 넘는 새로운 성매개감염(STI) 사례가 보고되었습니다. 클라미디아나 임질 감염의 약 70%는 무증상이기 때문에 감염의 연쇄를 끊기 위해서는 정기적인 검사가 필수적입니다. 15-24세의 Z세대와 젊은 밀레니얼 세대가 신규 사례의 거의 절반을 차지하고 있으며, 이에 따라 의료 시스템에서는 신속한 결과를 제공하고 재감염의 연쇄를 억제하는 현장 진단(PoC) 신속 검사의 도입이 진행되고 있습니다. 2024년에 성병 병원체로 mpox가 발견되면서 진단 수요는 더욱 높아졌습니다. 이는 임상의들이 기존 성병과 새로운 위협을 구별할 수 있는 다항목 검사 패널을 필요로 하기 때문입니다. 병원체와 약물 내성 프로파일을 동시에 검출할 수 있다는 점에서 핵산 검사 플랫폼은 확대되는 성병 진단 시장의 핵심으로 자리 잡고 있습니다.
정부 자금 지원 선별 검사 프로그램
미국 예방의료서비스작업반(USPSTF)은 2024년 선별 검사에 관한 지침을 확대하여, 25세 이하의 성적으로 활동적인 모든 사람에게 클라미디아와 임질에 대한 연 1회 검사를 권장했습니다. 캐나다에서도 유사한 움직임이 나타나, 원주민 커뮤니티와 외딴 지역 커뮤니티에서의 검사를 확대하기 위해 7,400만 캐나다 달러(5,480만 달러)가 배정되었습니다. 유럽연합(EU) 회원국들은 FDA 승인 또는 CE 마크를 획득한 분자진단법을 우선적으로 적용하는 지침을 통일했습니다. 이러한 프로그램들은 예측 가능한 조달원을 제공하고 품질 기준을 강화하는 동시에, 1차 진료, 공중보건 및 지역사회 내 성병 진단 시장 규모를 확대되고 있습니다.
사회적 편견과 낮은 인지도
조사 데이터에 따르면, 성인의 43%가 타인의 비판이나 사생활 침해를 두려워하여 성병(STI) 검사를 미루거나 거부하고 있습니다. 특정 지역의 문화적 금기 때문에 검사가 ‘부도덕한 성행위’로 간주되는 경우가 있으며, 그 결과 여성의 생식 의료 접근성이 불균형하게 제한되고 있습니다. 2024년에 시작된 공중보건 캠페인은 검사를 일상적인 건강 관리의 일환으로 재정의하고 있지만, 검진률은 여전히 지역에 따라 편차가 있습니다. 익명으로 이용할 수 있는 자가 검사 키트나 앱을 통해 예약할 수 있는 진료 시간은 일부 이용자에게 낙인을 완화시켜 주고 있지만, 일부 관할 구역의 원격 의료에 관한 법적 규제가 더 광범위한 보급을 방해하고 있습니다. 현재 진행 중인 학교 기반 성교육 시범 사업은 실시 지역에서 검사율을 25% 향상시켰으며, 이 교육 과정이 전국적으로 확대된다면 장기적인 성과가 기대됩니다.
부문별 분석
HIV 부문은 2025년 매출의 28.45%를 차지했으며, 이는 수혈 서비스, 산전 관리, 고위험군에 대한 정기적인 선별 검사를 의무화하는 확립된 정책이 배경에 있습니다. 매독은 선천성 감염 억제를 목적으로 한 산전 검사 의무화로 인해 2위 자리를 굳혔습니다. 클라미디아와 임질 검사는 합쳐서 총 수익의 약 3분의 1을 창출하고 있으며, 성적으로 활발한 청소년에 대한 연 1회 검사 권고가 이를 뒷받침하고 있습니다.
마이코플라스마 제니탈리움은 지속성 요도염에서 차지하는 역할에 대한 인식이 높아짐에 힘입어, 2031년까지의 연평균 성장률(CAGR)이 7.77%로 가장 높은 성장 전망을 보이고 있습니다. HPV 및 HSV 부문은 다중 NAAT 검사법을 통해 감별 진단이 효율화됨에 따라 꾸준한 성장을 보이고 있습니다. 트리코모나스증은 환자가 진료소를 떠나기 전에 치료 가능한 감염증을 검출할 수 있는 ‘당일 진료형’ PoC 플랫폼의 혜택을 받고 있습니다. 연성 하감은 여전히 틈새 시장이지만, 분자 검출의 정확도가 향상되어 기존에 발생하던 진단 누락이 감소하고 있습니다.
분자진단 플랫폼은 2025년에 50.78%의 점유율을 유지하며, 지침에 따른 진료를 뒷받침하는 신속하고 고감도의 결과를 제공했습니다. 면역 측정법은 자원이 제한된 환경에서 여전히 필수적이지만, 정확도의 격차가 추가적인 점유율 확대를 저해하고 있습니다.
차세대 염기서열 분석(NGS)은 병원체와 내성 프로파일링을 동시에 수행할 수 있어 연평균 성장률(CAGR) 9.13%가 예상됩니다. 이 기능은 CDC(미국 질병통제예방센터)와 같은 모니터링 기관으로부터 높은 평가를 받고 있으며, 해당 기관은 2024년에 4,500만 달러를 투자해 NGS 시스템을 대량으로 구매했습니다. 바이오센서와 마이크로플루이딕스 장치는 시료 전처리와 증폭을 하나의 칩에 통합하고 있어, 기술자의 숙련도를 거의 필요로 하지 않는 휴대형 대체 제품에 대한 벤처 자금 유입을 촉진하고 있습니다. 비용 곡선은 여전히 하락세를 보이고 있어, 이로 인해 중규모 검사 기관에서도 NGS 도입이 가능해지면서 성병(STD) 진단 시장 경쟁 구도가 재정의되고 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 41.62%를 차지했습니다. 이는 예방적 성병(STD) 서비스를 무상화하는 보험 의무화와 매독의 급증에 대응하기 위한 연방 정부의 강력한 조정 조치에 힘입은 결과입니다. 의료비에 대한 재량 지출이 높고 규제 당국의 승인이 신속하기 때문에 이 지역은 계속해서 혁신의 최전선에 서 있습니다. 지역 내 격차는 여전히 존재하며, 남부 주에서는 평균을 웃도는 감염률이 보고되고 있어, 성숙한 시장 내에서도 서비스가 충분히 제공되지 않는 지역이 있음을 시사합니다.
유럽은 국민 건강보험과 지역 간 규제 조화를 통해 안정적인 기반을 구축하고 있지만, 예산상의 압박에 직면해 있어 비용 대비 효과가 높은 현장 진단(PoC) 모델이 중시되고 있습니다. 아시아태평양은 도시화, 공중보건에 대한 투자, 동남아시아 생식 연령 여성의 성매개감염(STI) 유병률 11.6%에 힘입어 예측 연평균 성장률(CAGR) 10.76%로 가장 빠르게 성장하고 있는 지역입니다. 2024년, 중국의 의료 분야 부패 척결 조치로 인해 외국산 진단 기기 수입이 일시적으로 주춤했으나, 아세안(ASEAN)과 인도의 인프라 투자로 인해 검사에 대한 접근성은 확대되고 있습니다. 라틴아메리카와 중동 및 아프리카는 인식 제고와 모바일 헬스의 보급이 인프라 부족을 보완하며, 신흥 핵심 지역을 형성하고 있습니다. WHO가 지원하는 통합 진단 및 저비용 다항목 검사 패널에 대한 자금 지원으로 인해 기부 자본이 이들 지역으로 유입되고 있습니다. 남아프리카는 세계 최고 수준의 연령 조정 성매개감염증(STI) 발생률을 기록하고 있으며, 향후 확장 모델을 형성할 가능성이 있는 기부자 지원 시범 프로젝트의 초점이 되고 있습니다. 전반적으로, 지리적 분산화 전략이 전 세계 성병(STD) 진단 시장에서 경쟁하는 공급업체들의 수익 회복력을 좌우할 것으로 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the STD diagnostics market size was valued at USD 18.18 billion in 2025 and estimated to grow from USD 19.42 billion in 2026 to reach USD 27.04 billion by 2031, at a CAGR of 6.84% during the forecast period (2026-2031).
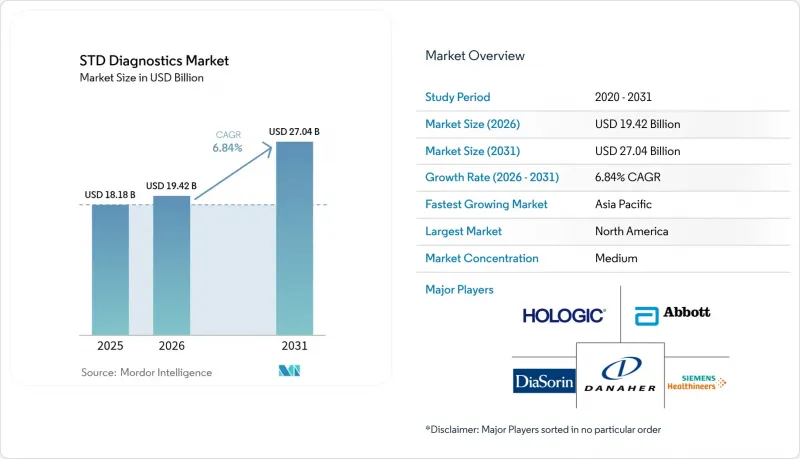
This report is Segmented by Test Type (Chlamydia, Gonorrhea, Syphilis, and More), Technology (Immunoassay-Based Methods, Molecular Diagnostics, Next-Generation Sequencing, and More), Location of Testing (Central & Hospital Laboratories, and More), End User (Hospitals & Clinics, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global STD Diagnostics Market Trends and Insights
Rising Global STD Incidence
The World Health Organization recorded more than 1 million new sexually transmitted infection cases every day during 2024. Asymptomatic presentations account for roughly 70% of chlamydia and gonorrhea infections, so routine testing is vital to interrupt transmission. Gen Z and young millennials aged 15-24 represent nearly half of new cases, prompting health systems to integrate rapid PoC assays that deliver timely results and curb reinfection chains. The discovery of mpox as a sexually transmitted pathogen in 2024 created further diagnostic demand because clinicians need multiplex panels able to distinguish legacy STIs from emerging threats. Simultaneous detection of pathogens and resistance profiles places nucleic-acid platforms at the center of the expanding STD diagnostics market.
Government-Funded Screening Programmes
The U.S. Preventive Services Task Force broadened its screening guidance in 2024 to recommend annual chlamydia and gonorrhea tests for all sexually active individuals younger than 25. Similar moves in Canada earmarked CAD 74 million (USD 54.8 million) to extend testing in Indigenous and remote communities. European Union member states synchronized guidelines that favor FDA-cleared or CE-marked molecular assays. These programs provide predictable procurement streams, reinforce quality benchmarks, and enlarge the STD diagnostics market size across primary care, public health, and community settings.
Social Stigma & Low Awareness
Survey data show 43% of adults delay or reject STI screening for fear of judgment or privacy breaches. Cultural taboos in certain regions equate testing with promiscuity, disproportionately limiting women's access to reproductive care. Public-health campaigns launched in 2024 re-frame screening as a routine wellness metric, yet uptake remains uneven. Anonymous home kits and app-scheduled clinic slots alleviate stigma for some users, but legal restrictions on telemedicine in several jurisdictions slow wider adoption. Ongoing school-based sex-education pilots have lifted testing rates by 25% where implemented, suggesting long-run gains once curricula scale nationally.
Other drivers and restraints analyzed in the detailed report include:
- Advances in NAAT & Rapid PoC Platforms
- Home Self-Testing & Digital Connectivity
- Regulatory & Reimbursement Hurdles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The HIV segment collected 28.45% of 2025 revenue, underscoring entrenched policies that require routine screening in blood services, prenatal care, and high-risk populations. Syphilis anchors the number-two position thanks to prenatal mandates that aim to curb congenital infections. Chlamydia and gonorrhea testing together generated roughly one-third of total revenue, supported by annual testing advice for sexually active youth.
Mycoplasma genitalium reported the quickest 7.77% CAGR outlook through 2031, propelled by growing recognition of its role in persistent urethritis. HPV and HSV segments post steady gains as multiplex NAAT assays streamline differential diagnosis. Trichomonas benefits from same-visit PoC platforms that catch treatable infections before patients leave the clinic. Chancroid remains niche but experiences improved molecular detection accuracy, reducing historical under-diagnosis.
Molecular platforms retained 50.78% share in 2025, delivering rapid, highly sensitive results that support guideline-driven care. Immunoassays remain vital in lower-resource settings, yet accuracy gaps limit additional share gains.
Next-generation sequencing is set for a 9.13% CAGR thanks to simultaneous pathogen and resistance profiling, capabilities prized by surveillance bodies such as the CDC, which purchased fleet NGS systems for USD 45 million in 2024. Biosensor and microfluidic devices integrate sample prep and amplification on a chip, drawing venture funding into portable alternatives that require minimal technician skill. Cost curves remain on a downward slope, opening mid-tier labs to NGS adoption and redefining the competitive stakes within the STD diagnostics market.
Complete Report Scope:
- By Test Type
- Syphilis Testing
- HPV Testing
- HSV Testing
- HIV Testing
- Trichomonas Testing
- Mycoplasma Genitalium Testing
- Chancroid Testing
- Chlamydia Testing
- Gonorrhea Testing
- By Technology
- Immunoassay-based Methods
- Molecular Diagnostics
- Next-Generation Sequencing
- Biosensor / Microfluidics & Other Emerging Platforms
- By Location of Testing
- Central & Hospital Laboratories
- Rapid Point-of-Care Platforms
- Over-the-Counter / Home Self-Testing
- By End User
- Hospitals & Clinics
- Diagnostic Laboratories
- Home Care / OTC
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America commanded 41.62% of global revenue in 2025, sustained by insurance mandates that make preventive STD services cost-free and by robust federal coordination to counter the syphilis surge. High discretionary healthcare spending and rapid regulatory approvals keep the region at the innovation vanguard. Nevertheless, intra-regional gaps prevail; Southern states report above-average infection rates, signaling under-served pockets even within a mature market.
Europe follows with a stable base built on universal health coverage and pan-regional regulatory harmonization, yet faces budgetary pressure that favors cost-effective point-of-care models. Asia-Pacific is the fastest-growing territory at a forecast 10.76% CAGR, driven by urbanization, public-health investments, and an 11.6% STI prevalence among reproductive-age women in Southeast Asia. China's anti-corruption clampdown in healthcare briefly slowed foreign diagnostic imports in 2024, but infrastructure spending across ASEAN and India is widening test access. Latin America and the Middle East & Africa together form an emerging corridor where rising awareness and mobile-health penetration offset infrastructure deficits. WHO-backed funding for integrated diagnostics and low-cost multiplex panels is steering donor capital into these regions. South Africa records the world's highest age-standardized STI rates, making it a focal point for donor-supported pilot projects that could shape future expansion models. Overall, geographic diversification strategies will define revenue resilience for vendors competing in the global STD Diagnostics market.
- Abbott Laboratories
- Roche
- Hologic
- Beckton Dickinson
- Danaher
- Siemens Healthineers
- bioMerieux
- Thermo Fisher Scientific
- QIAGEN
- Bio-Rad Laboratories
- DiaSorin
- QuidelOrtho
- Trinity Biotech plc
- Chembio Diagnostics Inc.
- Orasure Technologies
- Sekisui Diagnostics
- Genetic Signatures Ltd.
- LumiraDx Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global STD Incidence
- 4.2.2 Government-Funded Screening Programmes
- 4.2.3 Advances in NAAT & Rapid PoC Platforms
- 4.2.4 Home Self-Testing & Digital Connectivity
- 4.2.5 Multiplex AMR Panels for STI Pathogens
- 4.2.6 Corporate Pre-Employment Screening in EMs
- 4.3 Market Restraints
- 4.3.1 Social Stigma & Low Awareness
- 4.3.2 Regulatory & Reimbursement Hurdles
- 4.3.3 Skilled-Lab-Staff Shortages in LMICs
- 4.3.4 Cross-Reactivity-Driven False Positives
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Test Type
- 5.1.1 Syphilis Testing
- 5.1.2 HPV Testing
- 5.1.3 HSV Testing
- 5.1.4 HIV Testing
- 5.1.5 Trichomonas Testing
- 5.1.6 Mycoplasma Genitalium Testing
- 5.1.7 Chancroid Testing
- 5.1.8 Chlamydia Testing
- 5.1.9 Gonorrhea Testing
- 5.2 By Technology
- 5.2.1 Immunoassay-based Methods
- 5.2.2 Molecular Diagnostics
- 5.2.3 Next-Generation Sequencing
- 5.2.4 Biosensor / Microfluidics & Other Emerging Platforms
- 5.3 By Location of Testing
- 5.3.1 Central & Hospital Laboratories
- 5.3.2 Rapid Point-of-Care Platforms
- 5.3.3 Over-the-Counter / Home Self-Testing
- 5.4 By End User
- 5.4.1 Hospitals & Clinics
- 5.4.2 Diagnostic Laboratories
- 5.4.3 Home Care / OTC
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 F. Hoffmann-La Roche AG
- 6.3.3 Hologic Inc.
- 6.3.4 Becton Dickinson and Company
- 6.3.5 Danaher Corporation (Cepheid)
- 6.3.6 Siemens Healthineers AG
- 6.3.7 bioMerieux SA
- 6.3.8 Thermo Fisher Scientific Inc.
- 6.3.9 Qiagen N.V.
- 6.3.10 Bio-Rad Laboratories Inc.
- 6.3.11 DiaSorin S.p.A.
- 6.3.12 QuidelOrtho Corporation
- 6.3.13 Trinity Biotech plc
- 6.3.14 Chembio Diagnostics Inc.
- 6.3.15 OraSure Technologies Inc.
- 6.3.16 Sekisui Diagnostics LLC
- 6.3.17 Genetic Signatures Ltd.
- 6.3.18 LumiraDx Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment