

|
시장보고서
상품코드
2122508
자율 배송 로봇 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Autonomous Delivery Robots - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
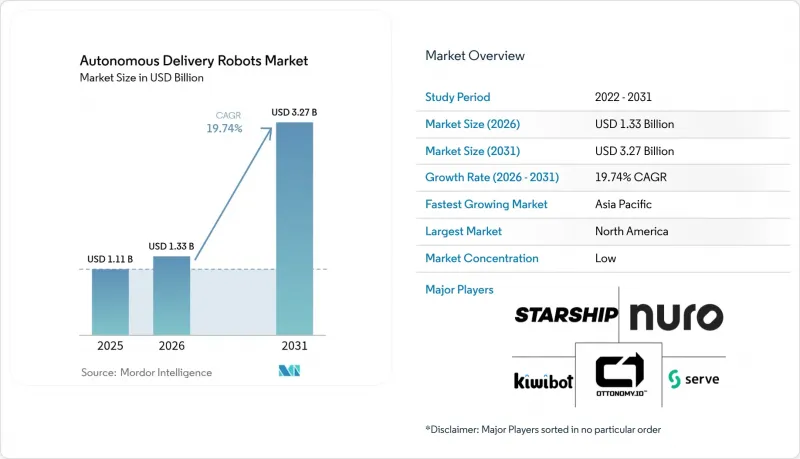
에 의하면, 자율형 배송 로봇 시장 규모는 2025년 11억 1,000만 달러에서 2026년에는 13억 3,000만 달러로 성장하고, 2026-2031년 CAGR 19.74%로 성장을 지속하여 2031년에는 32억 7,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 로봇 유형(실내용, 실외용, 하이브리드), 용도(식품, 식료품, 소포 등), 적재 용량(10kg 이하, 10-25kg, 25-80kg, 80kg 초과), 최종 사용자(의료, 호텔, 소매 등),구성 요소(하드웨어, 소프트웨어 등), 구동 방식(전기, 수소, 하이브리드), 자율성 수준, 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 자율 주행 배송 로봇 시장 동향 및 인사이트
주문형 식료품 배달의 급속한 확대
주문 밀도가 높아 기존 운전자의 인건비를 상쇄하기 때문에 온디맨드 식료품 배달 서비스는 현재 자율 주행 로봇군의 지속 가능한 단위 경제성의 기반이 되고 있습니다. 크로거(Kroger)는 주문 처리를 신속화하고 물류 비용을 절감하기 위해 댈러스 사업장에 무인 트럭을 도입했습니다. 또한 소매업체들은 매장 내 진열대 스캔 로봇을 도입하여 재고 부족으로 인한 4.5%의 매출 손실(입증됨)을 줄이고 있습니다. 이는 Simbe Robotics가 60개 매장을 운영하는 Spartan Nash에 도입한 사례에서도 분명하게 드러납니다. 이러한 움직임은 식료품 체인점들이 로봇 기술을 시범 단계에서 핵심 인프라로 전환하고 있으며, 라스트 마일 로봇이 처리할 수 있는 주문량을 확대하고 있음을 뒷받침합니다.
심화되는 인력 부족과 임금 상승
북미의 주문 처리 센터는 심각한 인력 부족에 직면해 있으며, 이는 기업들을 자동화로의 전환으로 몰아가고 있습니다. 미국 제조업에서는 2030년까지 200만 명의 노동력 부족이 예상되며, 라스트 마일 운전자의 높은 이직률도 비용 압박을 더욱 가중시키고 있습니다. 산업용 로봇 가격이 지난 10년간 50% 하락했고, EY가 추가 하락을 예측함에 따라 투자 타당성은 더욱 높아지고 있습니다. 또한, 도시 지역의 배송 밀도가 높기 때문에 사업자는 가동률 목표를 달성하고 자율형 자산에 대한 투자를 조기에 회수할 수 있습니다.
LiDAR 및 센서 스위트의 높은 초기 비용
내비게이션용 하드웨어는 배송 로봇에서 가장 큰 자본 지출 항목이 되는 경우가 많습니다. Sonair와 같은 신흥 초음파 기술은 180×180도의 감지 범위를 유지하면서도 센서 비용을 최대 80% 절감합니다. Cartken의 LiDAR가 필요 없는 비전 스택은 이미 공공 보도에서 수익성을 확보하고 있으며, 비용 효율적인 센싱으로도 신뢰성 기준을 충족할 수 있음을 입증하고 있습니다. 하지만 이러한 새로운 센서 조합이 규제 당국의 승인을 받을 때까지는 본격적인 배포를 기다려야 합니다.
부문 분석
실외용 로봇은 2025년 매출의 57.20%를 차지하며, 충분히 검증된 보도 운영을 통해 자율 배송 로봇 시장의 기반을 다지고 있습니다. 이러한 우위는 음식 배달 플랫폼 및 지역 규제 당국과의 신뢰할 수 있는 파트너십을 반영하며, 도시 지역에서의 확장 가능한 배포를 가능하게 합니다. 사업자들은 연석, 횡단보도 및 보행자와의 상호작용에 대응할 수 있도록 섀시를 지속적으로 개선하고 있으며, 이를 통해 도시 지역에서의 견고한 입지를 더욱 공고히 하고 있습니다.
하이브리드형 전지형 대응 유닛은 소매업 및 접객업 업계 고객들로부터 문턱을 넘어서는 원활한 도어 투 도어 서비스가 요구됨에 따라 연평균 성장률(CAGR) 26.65%로 급속히 확대되고 있습니다. 공급업체들은 이에 대응하여 사륜 조향, 모듈식 화물 포드, 견고한 서스펜션을 통합하고 있으며, 이러한 추세는 Avride사가 NVIDIA가 탑재된 사륜 플랫폼으로 무게중심을 옮긴 데서 뚜렷이 드러납니다. 실내 서비스 로봇은 통제된 통로에서 완전한 도로 수준의 감지 기능 없이도 높은 자율성이 허용되는 캠퍼스나 병원 등에서 틈새 역할을 유지하고 있습니다.
2025년, 음식 배달 분야는 매출 점유율 42.10%를 유지하며, 빈번한 소액 주문이 여전히 자율 주행 배송 로봇 시장의 기반임을 입증하고 있습니다. 주문 반복 빈도가 높기 때문에 자산 활용이 최적화되고 경로 학습이 간소화되어, Serve Robotics와 같은 플랫폼에서 전체 차량군의 수익성이 뒷받침되고 있습니다.
소매업체들이 1시간 이내 배송을 추구하는 가운데, 식료품 및 편의점 부문은 연평균 23.70%의 성장률을 보이고 있습니다. 로봇은 온도 조절이 가능한 토트백 및 현관 앞 인도 서비스를 지원하며, 이를 통해 장바구니 규모가 확대되고 팁 수입을 통한 수익성이 향상되고 있습니다. 소포 배송 서비스도 발전하고 있지만, 적재량 상한선으로 인해 무거운 SKU는 여전히 제한을 받고 있어 당분간은 경량 전자상거래 주문에 초점이 맞추어져 있습니다.
지역별 분석
북미는 2025년에도 31.60%의 점유율을 유지하고 있으며, 이는 높은 임금 인플레이션과 주별 규제가 복잡하게 얽혀 있음에도 불구하고 지원적인 환경을 반영하고 있습니다. 캘리포니아주와 텍사스주에서는 최대 규모의 도시 지역에서 실증 실험이 진행되고 있으며, Serve Robotics는 Uber Eats의 틀 아래 2025년 말까지 2,000대를 도입하는 것을 목표로 하고 있습니다. 대학가에서의 도입 규모도 확대되고 있으며, Grubhub와 Yandex는 250개 캠퍼스에서 서비스를 전개할 계획으로, 세계에서 가장 밀집도가 높은 로봇 네트워크를 형성할 가능성이 있습니다.
아시아태평양은 25.40%의 점유율로 그 뒤를 잇고 있으며, 일본과 한국에서는 의료 및 스마트 시티 프로그램이 가속화되고 있습니다. 한국의 보도 이용을 고려한 법규에서는 로봇의 최고 속도를 시속 15km, 중량을 500kg으로 제한하고 있어, 이를 통해 아파트 단지나 병원에서의 상용 시험이 가능해졌습니다. 도요타의 ‘포타로’ 시스템은 병원 내 이용 모델을 제시하고 있으며, 아시아태평양이 고령화에 따른 물류에 주력하고 있음을 여실히 보여주고 있습니다.
유럽은 도심 내 디젤 밴에 벌금을 부과하는 엄격한 ESG 규제의 뒷받침을 받아 견고한 수익 기반을 구축하고 있습니다. 스타쉽 테크놀로지스(Starship Technologies)는 저속 로봇이 보행자 전용 구역을 공유하는 것을 허용하는 규제상의 특례에 따라 독일과 영국에서 사업을 전개하고 있습니다. 사업자들은 여전히 복잡하고 여러 관할 구역에 걸쳐 있는 승인 절차를 거쳐야 하기 때문에 규모 확대에 걸림돌이 되고 있지만, 환경 측면의 호재 덕분에 도입은 착실한 궤도를 타고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, the autonomous delivery robots market size is expected to grow from USD 1.11 billion in 2025 to USD 1.33 billion in 2026 and is forecast to reach USD 3.27 billion by 2031 at 19.74% CAGR over 2026-2031.
This report is Segmented by Robot Type (Indoor, Outdoor, Hybrid), Application (Food, Grocery, Parcel, and More), Load Capacity (Up To 10kg, 10-25kg, 25-80kg, Above 80kg), End-User (Healthcare, Hotels, Retail, and More), Component (Hardware, Software and More), Propulsion (Electric, Hydrogen, Hybrid), Level of Autonomy, and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Autonomous Delivery Robots Market Trends and Insights
Rapid Expansion of On-Demand Grocery Delivery
On-demand grocery services now anchor sustainable unit economics for autonomous fleets because high order density offsets traditional driver costs. Kroger integrated driverless trucks into its Dallas operations to accelerate fulfillment and trim logistics spend. Retailers also embed in-store shelf-scanning robots to reduce the documented 4.5% revenue leakage linked to stock-outs, as shown by Simbe Robotics' rollout across 60 SpartanNash stores. Together these moves confirm that grocery chains are shifting robotics from pilot status to core infrastructure, widening order volumes available to last-mile robots.
Rising Labor Shortages and Wage Inflation
North American fulfillment centers face acute staffing gaps that push companies toward automated alternatives. The U.S. manufacturing sector projects a 2 million-worker shortage by 2030, and last-mile driver turnover amplifies cost pressure. Falling industrial robot prices-down 50% in the past decade-and further declines predicted by EY strengthen the investment case. High urban delivery density then allows operators to hit utilization targets that yield faster payback on autonomous assets.
High Upfront Cost of LiDAR and Sensor Suites
Navigation hardware often accounts for the largest capital item in a delivery robot. Emerging ultrasonic alternatives such as Sonair cut sensor spend by up to 80% while keeping a 180 X 180 degree detection envelope. Cartken's lidar-free vision stack already operates profitably on public sidewalks, proving that cost-efficient sensing can meet reliability thresholds. Even so, broad rollout waits on regulatory validation of these novel sensor mixes.
Other drivers and restraints analyzed in the detailed report include:
- ESG-Driven Push for Zero-Emission Last-Mile Vehicles
- Aging Population Spurring Intra-Hospital Delivery Automation
- Vandalism and Theft Incidents in South-American Metros
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Outdoor robots generated 57.20% of 2025 revenue, anchoring the autonomous delivery robots market through well-tested sidewalk operations. This dominance reflects reliable partnerships with food aggregators and local regulators that allow scalable city deployments. Operators continue to refine chassis for curbs, crosswalks, and pedestrian interaction, reinforcing their urban stronghold.
Hybrid all-terrain units expand rapidly at 26.65% CAGR because retail and hospitality customers ask for seamless door-to-door service that crosses thresholds. Suppliers respond by integrating four-wheel steering, modular cargo pods, and ruggedized suspension, a trend evident in Avride's pivot to NVIDIA-powered four-wheel platforms. Indoor service robots maintain niche roles in campuses and hospitals where controlled corridors permit higher autonomy without full street-grade sensing.
Food delivery retained 42.10% revenue share in 2025, proving that frequent small-ticket orders still underpin the autonomous delivery robots market. High repetition optimizes asset utilization and simplifies route learning, supporting fleet-level profitability for platforms such as Serve Robotics.
Grocery and convenience segments rise 23.70% annually as retailers chase sub-hour fulfillment. Robots accommodate temperature-controlled totes and door-step protocols that boost basket size and tip-influenced economics. Parcel courier services also advance, but payload ceilings still limit heavier SKUs, keeping focus on lightweight e-commerce orders for now.
Complete Report Scope:
- By Robot Type
- Indoor Service Robots
- Outdoor Autonomous Delivery Robots
- Hybrid All-Terrain Robots
- By Application
- Food Delivery
- Grocery and Convenience Deliveries
- Parcel and Courier (E-commerce)
- Healthcare Supply and Medication
- Hospitality Room-Service
- Industrial Campus Logistics
- By Load Capacity
- Up to 10 kg
- 10 - 25 kg
- 25 - 80 kg
- Above 80 kg
- By End-User Industry
- Healthcare Facilities
- Hospitality and Hotels
- Retail and E-commerce Logistics
- Corporates and Academic Campuses
- Airports and Transportation Hubs
- Smart Cities and Municipal Agencies
- By Component
- Hardware
- Software / AI Stack
- After-Sales Services and Fleet Management
- By Propulsion Type
- Electric Battery
- Hydrogen Fuel Cell
- Hybrid Energy Harvesting
- By Level of Autonomy
- Semi-Autonomous (Human-Supervised)
- Fully Autonomous (Level 4)
- Swarm/Clustered Autonomous Network (Level 5)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Africa
- South Africa
- Kenya
- Asia-Pacific
- China
- Australia
- Japan
- Singapore
- India
- South Korea
- North America
Geography Analysis
North America retained 31.60% share in 2025, reflecting high wage inflation and a supportive patchwork of state-level rules. California and Texas host the largest urban pilots, with Serve Robotics targeting 2,000 units by year-end 2025 under an Uber Eats framework. College-town deployments add scale; Grubhub and Yandex plan rollouts across 250 campuses, potentially forming the world's densest robot network.
Asia-Pacific followed with a 25.40% stake as Japan and South Korea accelerate healthcare and smart-city programs. South Korea's sidewalk-friendly legislation caps robot speed at 15 km/h and weight at 500 kg, unlocking commercial trials in apartment complexes and hospitals. Toyota's Potaro system shows the model for intra-hospital use, highlighting APAC's focus on aging-related logistics.
Europe contributes a solid revenue base, aided by stringent ESG mandates that penalize diesel vans in city centers. Starship Technologies operates in Germany and the UK under regulatory exemptions that let slow-moving robots share pedestrian zones. Operators still navigate complex, multi-jurisdiction approval processes, slowing scale, yet the environmental tailwinds keep adoption on a steady path.
- Starship Technologies
- Nuro Inc.
- Kiwibot
- Serve Robotics Inc.
- Ottonomy.IO
- Relay Robotics Inc.
- Postmates Inc. (Serve by Uber)
- Aethon Inc.
- Segway Robotics Inc.
- Neolix
- Udelv Inc.
- JD Logistics (Jian Robots)
- Alibaba Cainiao (Xiaomanlv)
- Yandex Rover
- FedEx Roxo
- Amazon Scout
- Rival Robotics Inc.
- TeleRetail (Aitonomi AG)
- Daxbot
- Locus Robotics (campus variant)
- Kiwi Campus SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid expansion of on-demand grocery delivery in urban Asia
- 4.2.2 Rising labor shortages and wage inflation in North-American fulfilment
- 4.2.3 ESG-driven push for zero-emission last-mile vehicles in the EU
- 4.2.4 Aging population spurring intra-hospital delivery automation in Japan
- 4.2.5 24/7 contact-free services demand in Middle-East luxury hotels
- 4.2.6 5G edge-compute enabling higher robot autonomy in dense city cores
- 4.3 Market Restraints
- 4.3.1 Municipal sidewalk regulation variability in US cities
- 4.3.2 Limited payload capacity restricting ROI for bulk goods
- 4.3.3 High upfront cost of LiDAR and sensor suites
- 4.3.4 Vandalism and theft incidents in S-American metros
- 4.4 Value-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Impact of Macro-Trend Analysis
- 4.7 Regulatory Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Robot Type
- 5.1.1 Indoor Service Robots
- 5.1.2 Outdoor Autonomous Delivery Robots
- 5.1.3 Hybrid All-Terrain Robots
- 5.2 By Application
- 5.2.1 Food Delivery
- 5.2.2 Grocery and Convenience Deliveries
- 5.2.3 Parcel and Courier (E-commerce)
- 5.2.4 Healthcare Supply and Medication
- 5.2.5 Hospitality Room-Service
- 5.2.6 Industrial Campus Logistics
- 5.3 By Load Capacity
- 5.3.1 Up to 10 kg
- 5.3.2 10 - 25 kg
- 5.3.3 25 - 80 kg
- 5.3.4 Above 80 kg
- 5.4 By End-User Industry
- 5.4.1 Healthcare Facilities
- 5.4.2 Hospitality and Hotels
- 5.4.3 Retail and E-commerce Logistics
- 5.4.4 Corporates and Academic Campuses
- 5.4.5 Airports and Transportation Hubs
- 5.4.6 Smart Cities and Municipal Agencies
- 5.5 By Component
- 5.5.1 Hardware
- 5.5.2 Software / AI Stack
- 5.5.3 After-Sales Services and Fleet Management
- 5.6 By Propulsion Type
- 5.6.1 Electric Battery
- 5.6.2 Hydrogen Fuel Cell
- 5.6.3 Hybrid Energy Harvesting
- 5.7 By Level of Autonomy
- 5.7.1 Semi-Autonomous (Human-Supervised)
- 5.7.2 Fully Autonomous (Level 4)
- 5.7.3 Swarm/Clustered Autonomous Network (Level 5)
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Chile
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 United Kingdom
- 5.8.3.3 France
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.4 Middle East
- 5.8.4.1 United Arab Emirates
- 5.8.4.2 Saudi Arabia
- 5.8.4.3 Turkey
- 5.8.5 Africa
- 5.8.5.1 South Africa
- 5.8.5.2 Kenya
- 5.8.6 Asia-Pacific
- 5.8.6.1 China
- 5.8.6.2 Australia
- 5.8.6.3 Japan
- 5.8.6.4 Singapore
- 5.8.6.5 India
- 5.8.6.6 South Korea
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Starship Technologies
- 6.4.2 Nuro Inc.
- 6.4.3 Kiwibot
- 6.4.4 Serve Robotics Inc.
- 6.4.5 Ottonomy.IO
- 6.4.6 Relay Robotics Inc.
- 6.4.7 Postmates Inc. (Serve by Uber)
- 6.4.8 Aethon Inc.
- 6.4.9 Segway Robotics Inc.
- 6.4.10 Neolix
- 6.4.11 Udelv Inc.
- 6.4.12 JD Logistics (Jian Robots)
- 6.4.13 Alibaba Cainiao (Xiaomanlv)
- 6.4.14 Yandex Rover
- 6.4.15 FedEx Roxo
- 6.4.16 Amazon Scout
- 6.4.17 Rival Robotics Inc.
- 6.4.18 TeleRetail (Aitonomi AG)
- 6.4.19 Daxbot
- 6.4.20 Locus Robotics (campus variant)
- 6.4.21 Kiwi Campus SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


