|
시장보고서
상품코드
2122516
데이터 준비 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Data Preparation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 데이터 준비 시장 규모는 2025년 69억 5,000만 달러에서 2026년에는 80억 5,000만 달러로 성장하고, 2026-2031년 CAGR 15.92%로 성장을 지속하여 2031년에는 168억 4,000만 달러에 달할 것으로 예측됩니다.
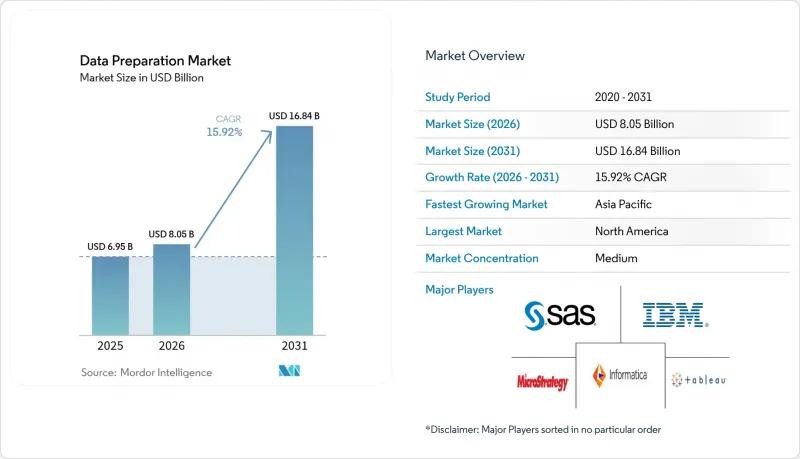
본 보고서는 도입 형태(On-Premise 및 클라우드), 기업 규모(중소기업(SME) 및 대기업), 솔루션 유형(데이터 수집, 데이터 카탈로그화 등), 최종 사용자 산업 분야(은행, 금융서비스 및 보험(BFSI), 헬스케어 및 생명과학 등), 그리고 지역별로 분류되어 있습니다.
세계 데이터 준비 시장 동향 및 인사이트
로우코드/노코드 셀프 서비스 분석 도구로의 전환 가속화
로우코드 인터페이스는 비즈니스 전문가가 스크립트가 아닌 드래그 앤 드롭 방식을 통한 설계를 통해 파이프라인을 구축할 수 있도록 함으로써 데이터 준비 시장을 재정의하고 있습니다. Google Cloud의 BigQuery 데이터 준비 기능은 이러한 동향을 여실히 보여주며, 자연어 프롬프트를 사용하여 데이터 정제, 프로파일링 및 변환을 수행하는 AI 가이드를 제공합니다. 이러한 접근 방식을 통해 부족하기 쉬운 데이터 엔지니어에 대한 의존도가 낮아지고 개발 주기가 단축될 뿐만 아니라, 분석 제공이 해당 분야의 전문 지식과 일치하게 됩니다. GenAI를 활용한 기능 확장은 빠르게 확산되고 있으며, 업계 예측에 따르면 2026년까지 거의 모든 BI 플랫폼에 GenAI가 통합될 전망입니다. 다만, 이러한 도입에는 일반 사용자가 구축하는 워크플로가 급증하는 상황에서 기업의 품질 및 보안 기준을 준수할 수 있도록 치밀한 거버넌스가 요구됩니다.
중소기업(SME) 분석 팀의 클라우드 도입 급증
중소기업은 대형 경쟁사와의 역량 격차를 해소하기 위해 클라우드 네이티브 파이프라인을 확대하고 있으며, 아시아태평양 전체에서 수요가 점차 증가하고 있습니다. 이 지역에서는 기업의 60%가 2025년까지 AI 언어 모델 도입을 계획하고 있습니다. 클라우드의 확장성과 종량제 요금제를 통해 중소기업은 자본 지출을 피하면서도 고급 데이터 준비 기능을 활용할 수 있게 됩니다. 영국의 조사에 따르면, 현재 빅데이터 분석을 활용하고 있는 중소기업은 1% 미만이며, 비용이나 복잡성 같은 장벽이 낮아짐에 따라 향후 성장 여지가 크다는 점이 부각되고 있습니다. 그러나 기술 인력 부족 문제는 여전히 지속되고 있으며, 매니지드 서비스 제공업체들이 파이프라인 구축 및 규정 준수 강화, 특히 새로운 데이터 현지화 규제에 대한 대응을 지원하고 있습니다.
복잡한 데이터 거버넌스 설정에서의 기술 격차
CIO의 3분의 1 가까이가 데이터 관리의 복잡성을 심각한 장애물로 꼽고 있으며, 거버넌스 전문가 부족으로 인해 확장 가능한 파이프라인 도입이 지연되고 있습니다. 캘리포니아주의 기후 정보 공개 규정 등, 스코프 1-3 배출량의 자동 수집을 의무화하는 법규가 있는 경우, 이 과제는 더욱 심각해집니다. 신흥 시장에서는 교육 프로그램의 구축이 뒤처져 있어 인력 부족이 더욱 심각해지고 있으며, 기업들은 외부 컨설턴트나 관리형 서비스 계약에 의존할 수밖에 없어, 그 결과 도입 예산이 불어나는 상황이 발생하고 있습니다.
부문 분석
On-Premise형 플랫폼의 데이터 준비 시장 규모는 2025년에 45억 1,000만 달러에 달하여, 전체 데이터 준비 시장의 64.88%를 차지했습니다. 이는 현지화 규제가 엄격해짐에 따라 기업이 직접적인 관리를 요구하는 수요를 반영한 것입니다. 베트남의 데이터법이나 인도의 디지털 개인 데이터 보호 규정은 기밀성이 높은 기록을 국경 내에 보관하는 On-Premise형 및 소버린 클라우드 기반 모델을 뒷받침하고 있습니다. 클라우드 서비스의 규모는 작지만, 중소기업 및 디지털 네이티브 기업들이 민첩성을 우선시함에 따라 2031년까지 연평균 17.12%의 성장률로 확대될 것으로 예측됩니다. 북미에서는 규제 대상 데이터를 위한 로컬 클러스터와 위험이 낮은 워크로드를 위한 하이퍼스케일 리포지토리를 융합한 하이브리드형 아키텍처가 주류를 이루고 있습니다. 클라우드 제공업체는 규정 준수 문제를 해소하기 위해 전용 리전 인스턴스 및 암호화 키 관리 기능을 제공하고 있으며, 중소 도시에서도 직접 커넥트 광섬유가 구축됨에 따라 기존 기술 허브 이외의 지역에서도 도입이 확대되고 있습니다.
경제적 판단은 워크로드의 변동성에 좌우됩니다. 안정적인 ETL 배치 처리나 예측 가능한 데이터 보강 작업은 라이선스 비용 상각이라는 이유로 On-Premise에 남아 있는 반면, 버스트형 AI 추론이나 시민 개발자를 위한 샌드박스는 종량제 클라우드로 이전합니다. 2029년까지 다국적 기업의 절반 이상이 소버린 클라우드 인스턴스를 운영할 것으로 예상되며, 프라이빗, 퍼블릭, 엣지 각 노드에 걸쳐 원활한 정책 적용에 대한 수요가 발생하고 있습니다. 각 벤더들은 현재 인프라 환경에 관계없이 데이터 품질 규칙과 리니지 그래프를 전파하는 통합 제어 플레인을 중시하고 있습니다.
대기업은 2025년에 47억 3,000만 달러의 매출을 창출할 것으로 예상되며, 이는 데이터 준비 시장의 68.05%에 해당합니다. 이는 전담 거버넌스 팀과 세계 사업 확장에 힘입은 결과입니다. 대기업의 지출은 카탈로그, 리니지, 가시성을 기존 데이터 패브릭에 통합하는 플랫폼 번들에 집중되어 있습니다. 한편, 중소기업(SME) 시장 규모는 22억 2,000만 달러에 그치고 있지만,연평균 성장률(CAGR) 17.62%로 다른 부문을 상회하는 성장이 예상되며, 2031년까지 중소기업용 솔루션의 데이터 준비 시장 규모는 50억 2,000만 미달러에 달할 것으로 전망됩니다. 사용량 기반 과금제 및 자동 스키마 감지 기능을 통해 자본 측면의 장벽이 낮아짐에 따라, 지역 소매업체, 핀테크 기업, SaaS 스타트업이 기존 기업과 동등한 경쟁력을 확보할 수 있게 될 것입니다.
스몰 비즈니스 인스티튜트 저널(Small Business Institute Journal)의 조사에 따르면, 미국 중소기업의 70%가 분석의 가치를 인식하고 있지만, 엔드투엔드 파이프라인을 실행할 수 있는 사내 인재를 보유한 곳은 극히 일부에 불과합니다. 로우코드 클라우드 워크벤치와 매니지드 서비스 생태계가 이러한 격차를 메우는 한편, 업계 단체들은 일반 사용자의 활용을 가속화하기 위한 모듈식 교육을 제공합니다. 새로운 AI 관련 의무에 대응하는 정책 프레임워크 수립에는 여전히 과제가 남아 있어, 규정 준수를 전문으로 하는 채널 파트너에게 비즈니스 기회가 창출되고 있습니다.
지역별 분석
2025년 북미의 25억 4,000만 달러 지출은 데이터 준비 시장 점유율의 36.62%를 차지하며, 이는 초기 AI 실험과 탄탄한 벤더 생태계의 성과입니다. 캘리포니아주의 기후 정보 공개법은 기업 매출이 10억 달러를 초과하는 기업에 대해 Scope 1-3 배출량 공시를 의무화하고 있으며, 이로 인해 북미 전역에서 거버넌스 도구에 대한 수요가 증가하고 있습니다. 다른 국가에 본사를 두고 있지만 미국에서 사업을 전개하는 다국적 기업도 보고 의무를 지게 되므로, 그 영향력은 국경을 넘어 확산되고 있습니다. 캐나다에서는 법안 C-27 ‘소비자 개인정보 보호법’을 통해 유사한 프레임워크가 추진되고 있는 반면, 멕시코의 데이터 현지화 법안은 국경을 넘는 마키라도라형 공급망을 위한 하이브리드 클라우드 청사진을 촉진하고 있습니다. 이 지역의 투자 초점은 초기 데이터 수집 기능에서 운영 부담을 경감하는 고도의 가시성 및 자동 복구 기능으로 이동하고 있습니다.
아시아태평양은 가장 빠르게 성장하고 있으며, 퍼블릭 클라우드 성장률이 다른 지역을 앞지르는 가운데 연평균 16.98%의 성장세를 보이고 있습니다. 중국의 83%에 달하는 생성형 AI 도입률은 파이프라인의 적극적인 현대화로 나타나고 있는 반면, 한국과 일본은 의료 기록의 디지털화 및 스마트 팩토리 프로그램에 국가 AI 자금을 할당하고 있습니다. 베트남의 ‘데이터법’과 인도의 ‘DPDP 규정’에 따라 다국적 기업의 시스템 스택 내에 데이터 상주 요건이 도입되면서, On-Premise 엣지 배포가 증가하는 동시에 통합형 정책 엔진에 대한 수요가 촉진되고 있습니다. 호주의 기업들은 업스트림 데이터 준비 단계에서 실시간 이상 감지를 의무화하는 새로운 중요 인프라 보안 요건에 직면해 있습니다. 한편, 싱가포르 IMDA의 보조금은 중소기업을 클라우드 서비스로 유도하여 해당 지역의 대중 시장에서 모멘텀을 강화하고 있습니다.
유럽에서는 ESG 요건이 ‘보고 대응 완료’된 파이프라인 투자를 견인하며 15%대 중반의 꾸준한 성장을 기록하고 있습니다. EU의 ‘기업 지속가능성 보고 지침’에 따라 약 5만 개 기업이 통일된 분류 체계를 사용하여 온실가스 지표를 기록해야 할 의무가 부과되면서, 데이터 카탈로그 및 품질 관리 도구가 경영진의 주요 과제로 부상하고 있습니다. 독일과 프랑스가 지출을 주도하고 있지만, 이탈리아와 스페인에서도 ‘회복·탄력성 기금(RRF)’의 보조금이 디지털 전환 프로젝트를 지원함에 따라 그 기세가 가속화되고 있습니다. EU의 AI법에서는 투명성, 편향 모니터링, 그리고 인간에 의한 감독 기록이 의무화됨에 따라, 엣지 노드와 하이퍼스케일러의 영역에 걸쳐 안전한 리니지 아카이브의 필요성이 더욱 높아지고 있습니다. 동유럽 국가들은 시민의 데이터를 국내에 보관하기 위해 로컬 클라우드 용량을 확대하고 있으며, 지역 통신 사업자와 세계 하이퍼스케일러간의 제휴가 촉진되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, the data preparation market size is expected to grow from USD 6.95 billion in 2025 to USD 8.05 billion in 2026 and is forecast to reach USD 16.84 billion by 2031 at 15.92% CAGR over 2026-2031.
This report is Segmented by Deployment (On-Premises and Cloud), Enterprise Size (Small and Medium Enterprises (SMEs) and Large Enterprises), Solution Type (Data Ingestion, Data Cataloging, and More), End-User Vertical (BFSI, Healthcare and Life Sciences, and More), and Geography.
Global Data Preparation Market Trends and Insights
Accelerated Shift to Low-/No-Code Self-Service Analytics Tools
Low-code interfaces are redefining the data preparation market by enabling business specialists to build pipelines via drag-and-drop designs rather than scripts. Google Cloud's BigQuery data preparation illustrates the trend, offering AI guidance that cleans, profiles and transforms data with natural-language prompts. The approach reduces reliance on scarce data engineers, shortens development cycles and aligns analytics delivery with domain expertise. GenAI-powered augmentation is spreading quickly; industry forecasts suggest nearly all BI platforms will embed GenAI by 2026. Adoption, however, requires diligent governance to keep proliferating citizen-built flows aligned with enterprise quality and security standards.
Surging Cloud Adoption Among SME Analytics Teams
SMEs are scaling cloud-native pipelines to close capability gaps with larger rivals, driving incremental demand across Asia-Pacific where 60% of firms plan AI language-model implementation by 2025. Cloud elasticity and consumption pricing let smaller firms avoid capital expenses while accessing advanced data-prep functions. UK research shows sub-1% of SMEs exploit big-data analytics today, underscoring runway as cost and complexity hurdles fall. Yet skills shortages persist; managed service providers are stepping in to configure pipelines and enforce compliance, particularly around emerging data-localization rules.
Skills Gap for Complex Data-Governance Configuration
Nearly one-third of CIOs cite data-management complexity as a critical obstacle, and shortages of governance specialists delay the rollout of scalable pipelines. The challenge intensifies where legislation such as California's climate-disclosure rule mandates automated capture of Scope 1-3 emissions. Emerging markets face deeper shortages as academic programs lag, pushing firms toward external consultants and managed-service contracts that inflate deployment budgets.
Other drivers and restraints analyzed in the detailed report include:
- Integration of GenAI Copilots Inside Data-Prep Workflows
- Vendor Bundling of Data-Prep Modules into Broader Data-Fabric Suites
- Steep Total Cost of Ownership for Multi-Cloud Data Pipelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The data preparation market size for on-premises platforms totaled USD 4.51 billion in 2025, translating to 64.88% data preparation market share, a reflection of enterprise demand for direct control amid tougher localization rules. Vietnam's Data Law and India's Digital Personal Data Protection Rules reinforce on-prem and sovereign-cloud models that keep sensitive records within national borders. Cloud services, though smaller, are projected to compound at 17.12% through 2031 as SMEs and digitally native units prioritize agility. In North America, hybrid blueprints predominate, fusing local clusters for regulated data with hyperscale reservoirs for lower-risk workloads. Cloud providers respond with dedicated regional instances and encrypted-key control to offset compliance fears, widening adoption beyond traditional tech hubs as smaller cities gain direct-connect fiber.
The economic calculus hinges on workload variability: steady ETL batches and predictable enrichment jobs remain on-prem due to licensing amortization, while bursty AI inference and citizen-developer sandboxes migrate to pay-as-you-go clouds. Over half of multinationals are expected to run sovereign-cloud instances by 2029, creating demand for seamless policy enforcement across private, public and edge nodes. Vendors now emphasize unified control planes that propagate data-quality rules and lineage graphs no matter the substrate.
Large corporations generated USD 4.73 billion revenue in 2025, equal to 68.05% of the data preparation market, supported by dedicated governance teams and global footprints. Their spend skew favors platform bundles that integrate catalog, lineage and observability into existing data fabrics. Conversely, SMEs contributed USD 2.22 billion yet will outgrow other cohorts at 17.62% CAGR, lifting the data preparation market size for SME solutions to a projected USD 5.02 billion by 2031. Consumption billing and automated schema-detection reduce capital obstacles, enabling regional retailers, fintechs and SaaS start-ups to achieve parity with incumbents.
A Small Business Institute Journal survey shows 70% of U.S. SMEs acknowledge analytics value, but only a minority has in-house talent to execute end-to-end pipelines. Low-code cloud workbenches and managed-service ecosystems fill gaps, while industry associations offer modular training to accelerate citizen usage. Challenges persist in developing policy frameworks that map to emerging AI-act obligations, creating openings for channel partners specializing in compliance overlays.
Complete Report Scope:
- By Deployment
- On-premises
- Cloud
- By Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Solution Type
- Data Ingestion
- Data Cataloging
- Data Quality
- Data Governance
- Data Wrangling
- Data Enrichment
- By End-user Vertical
- BFSI
- Healthcare and Life Sciences
- Retail and e-Commerce
- Manufacturing and Industrial
- IT and Telecommunications
- Government and Public Sector
- Others (Energy, Education, Media)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America's USD 2.54 billion spend in 2025 reflected 36.62% data preparation market share, an outcome of early AI experimentation and dense vendor ecosystems. California's climate-disclosure statute compels companies above USD 1 billion revenue to publish Scope 1-3 emissions, reinforcing governance-tool demand across the continent. Multinationals headquartered elsewhere yet active in the United States must still report, extending influence beyond borders. Canada advances parallel frameworks through Bill C-27's Consumer Privacy Protection Act, while Mexico's data-localization proposals are prompting hybrid-cloud blueprints for cross-border maquiladora supply chains. The region's investment focus has pivoted from initial ingestion capabilities to advanced observability and automated remediation that reduce operational toil.
Asia-Pacific is the fastest climber, expanding 16.98% annually as public-cloud growth surpasses other regions. China's 83% GenAI adoption manifests in aggressive pipeline modernization, while South Korea and Japan allocate national AI funds to health-record digitization and smart-factory programs. Vietnam's Data Law and India's DPDP Rules trigger data-residency layers within multinational stacks, increasing on-prem edge deployments and stimulating demand for integrated policy engines. Australian enterprises face new Critical Infrastructure Security obligations that require real-time anomaly detection in upstream data-prep stages. Meanwhile, Singapore's IMDA grants push SMEs to cloud services, reinforcing the region's mass-market momentum.
Europe posts steady mid-teens growth as ESG mandates drive "report-ready" pipeline investments. The EU Corporate Sustainability Reporting Directive forces roughly 50,000 firms to log greenhouse-gas metrics using consistent taxonomies, elevating data catalog and quality tooling to the executive agenda. Germany and France lead spend, though momentum accelerates in Italy and Spain as Recovery and Resilience Facility grants underwrite digital-transition projects. The EU AI Act requires transparency, bias monitoring and human-oversight logs, deepening the need for secure lineage archives that span edge nodes and hyperscaler zones. Eastern European states ramp local-cloud capacity to keep citizen data domestic, encouraging partnerships between regional telcos and global hyperscalers.
- Alteryx Inc.
- Informatica LLC
- IBM Corporation
- Microsoft Corporation
- Tableau Software LLC (Salesforce)
- SAP SE
- SAS Institute Inc.
- QlikTech International AB
- TIBCO Software Inc.
- Talend SA
- Oracle Corporation
- Trifacta Inc. (Google)
- Databricks Inc.
- Snowflake Inc.
- Dataiku SAS
- MicroStrategy Inc.
- RapidMiner Inc.
- Paxata Inc. (DataRobot)
- Unifi Software Inc.
- Denodo Technologies Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated shift to low-/no-code self-service analytics tools
- 4.2.2 Surging cloud adoption among SME analytics teams
- 4.2.3 Integration of GenAI copilots inside data-prep workflows
- 4.2.4 Vendor bundling of data-prep modules into broader data-fabric suites
- 4.2.5 Rapid rise of domain-specific 'vertical AI' data-prep pipelines
- 4.2.6 Sovereign-cloud rules fuelling on-prem / hybrid repatriation
- 4.3 Market Restraints
- 4.3.1 Skills gap for complex data-governance configuration
- 4.3.2 Steep total cost of ownership for multi-cloud data-pipelines
- 4.3.3 Escalating data-sovereignty penalties in emerging markets
- 4.3.4 Carbon-footprint quotas pushing back on compute-heavy prep jobs
- 4.4 Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Assessment of the Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment
- 5.1.1 On-premises
- 5.1.2 Cloud
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Solution Type
- 5.3.1 Data Ingestion
- 5.3.2 Data Cataloging
- 5.3.3 Data Quality
- 5.3.4 Data Governance
- 5.3.5 Data Wrangling
- 5.3.6 Data Enrichment
- 5.4 By End-user Vertical
- 5.4.1 BFSI
- 5.4.2 Healthcare and Life Sciences
- 5.4.3 Retail and e-Commerce
- 5.4.4 Manufacturing and Industrial
- 5.4.5 IT and Telecommunications
- 5.4.6 Government and Public Sector
- 5.4.7 Others (Energy, Education, Media)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia and New Zealand
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Alteryx Inc.
- 6.4.2 Informatica LLC
- 6.4.3 IBM Corporation
- 6.4.4 Microsoft Corporation
- 6.4.5 Tableau Software LLC (Salesforce)
- 6.4.6 SAP SE
- 6.4.7 SAS Institute Inc.
- 6.4.8 QlikTech International AB
- 6.4.9 TIBCO Software Inc.
- 6.4.10 Talend SA
- 6.4.11 Oracle Corporation
- 6.4.12 Trifacta Inc. (Google)
- 6.4.13 Databricks Inc.
- 6.4.14 Snowflake Inc.
- 6.4.15 Dataiku SAS
- 6.4.16 MicroStrategy Inc.
- 6.4.17 RapidMiner Inc.
- 6.4.18 Paxata Inc. (DataRobot)
- 6.4.19 Unifi Software Inc.
- 6.4.20 Denodo Technologies Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment