

|
시장보고서
상품코드
2122520
투명 일렉트로닉스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Transparent Electronics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 투명 일렉트로닉스 시장 규모는 2025년에 27억 8,000만 달러로 평가되었습니다. 2026년 33억 7,000만 달러에서 2031년까지 88억 6,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) 동안 CAGR은 21.30%를 나타낼 전망입니다.
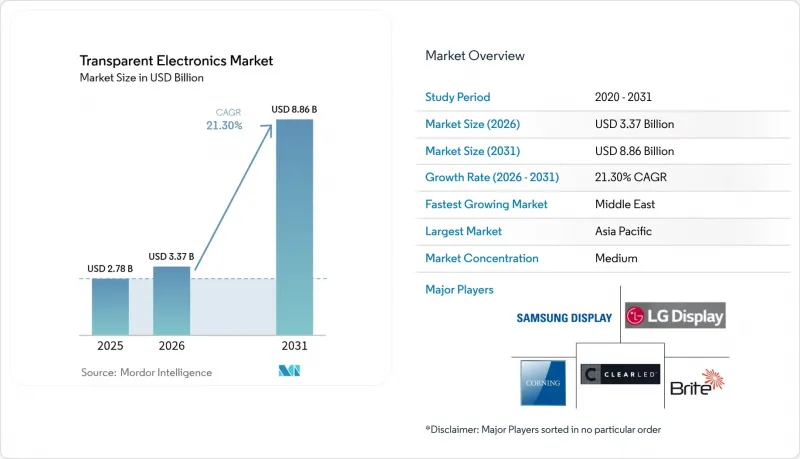
본 보고서는 제품 유형별(투명 디스플레이, 투명 태양광 패널, 스마트 제품 등), 소재 유형별(인듐주석산화물(ITO), 대체 TCO(AZO, FTO) 등), 기술별(LCD/TFT 등),최종 사용자용도별(가전제품, 자동차 및 운송, 항공우주 및 방위 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 투명 일렉트로닉스 시장 동향 및 인사이트
넷 제로 건축 기준이 스마트 윈도우 도입을 촉진
2030년까지 모든 신축 건축물에 대해 ‘거의 제로 에너지’ 성능을 의무화하는 유럽의 법규로 인해, 건축가들은 일사열 획득량을 동적으로 조절하는 일렉트로크로믹 유리의 채택을 요구받고 있습니다. 독일과 스칸디나비아 국가들의 실증 도입 사례에서는 냉방 에너지 절감률이 20% 이상의 것으로 나타났으며, 최신 액체 유동형 일렉트로크로믹 설계에서는 계절에 따라 실내 온도를 5°C 조절하는 기능도 추가되었습니다. 빌딩 자동화 시스템과의 통합이 표준화되고 있어, 패널 제조업체는 물론 센서 및 제어 기기 공급업체에게도 새로운 수익원이 열리고 있습니다. 중기적인 성장 전망은 스마트 윈도우를 포함한 건축 외피 개보수에 전용 예산을 배정하는 각국의 개보수 프로그램을 통한 자금 지원으로 인해 더욱 견고해지고 있습니다.
자율주행차가 투명 디스플레이의 보급을 가속화
각 자동차 제조업체들은 내비게이션, 운전 지원, 인포테인먼트 데이터를 앞유리에 직접 투사하는 대형 투명 헤드업 디스플레이(HUD) 도입을 추진하고 있습니다. 최근의 마이크로 LED 프로토타입은 1,000니트의 휘도를 유지하면서 85%의 투명도를 달성하여, 햇빛의 변화에 따른 기존의 눈부심 문제를 극복하고 있습니다. 이러한 성능은 미국, 일본, EU의 엄격한 운전자 주의 산만 방지 및 안전 기준을 충족하며, 2026년 출시 예정인 중형 전기차(EV)에 채택되는 계기가 되고 있습니다. 단기적인 수요는 레벨 3 자율주행 기능으로의 전환에 따라 더욱 확대되고 있습니다. 이 기능에서는 시스템 상태 정보를 표시하기 위해 더 넓은 시야가 필요하기 때문입니다.
생산 안정성을 위협하는 인듐 공급의 취약성
ITO는 여전히 주력 투명 전도체이지만, 정제 인듐의 절반 이상이 단일 국가에서 공급되고 있어 패널 제조업체들은 연간 30% 이상의 급격한 현물 가격 변동에 노출되어 있습니다. 이러한 가격 급등은 디스플레이 제조업체의 이익률을 압박하고, 생산 능력 확대 결정을 지연시키고 있습니다. 이에 대응하여 각 소재 제조업체들은 투과율 90%, 저항값 30Ω/sq 미만을 실현하고 1,000회의 굽힘 사이클을 견디는 은 나노와이어를 대체 소재로 제안하고 있습니다. 그러나 이러한 전환에는 새로운 경화 온도와 패터닝용 화학 약품이 필요하며, 양산을 위한 인증 절차가 장기화되고 있습니다.
부문별 분석
2025년에는 투명 디스플레이가 42.65%로 가장 큰 매출 점유율을 차지했지만, 자가 발전을 장려하는 건축 기준에 힘입어 투명 태양광 패널은 2031년까지 연평균 성장률(CAGR) 25.05%를 나타낼 것으로 예측됩니다. 스위스의 한 벤처 기업이 외관의 미관을 해치지 않으면서 표준 파사드에 자연스럽게 어우러지는 400W의 유리 같은 BIPV 모듈을 발표했습니다. 태양광 패널 분야의 투명 전자 시장 규모는 발전 기능과 채광 면이라는 이중적인 역할을 반영하여 2031년까지 22억 6,000만 달러에 달할 것으로 예측됩니다. 제품의 다양화는 현재 터치 센서나 히터의 기반이 되는 투명 전도성 필름은 물론, 항공우주 분야의 차폐용으로 사용되는 견고한 투명 세라믹까지 확대되고 있습니다. 동적 착색 기능을 갖춘 스마트 윈도우 유닛은 따뜻한 기후에서 운영 비용 절감으로 인해 투자 회수 기간이 5년 미만으로 단축된다는 점도 뒷받침되어, 상업용 부동산 분야에서 계속해서 보급이 확대되고 있습니다.
투명 전자 시장에서는 제품 카테고리 간의 상호 운용성이 점점 더 중요시되고 있습니다. 신기술인 탠덤 태양전지는 마이크로 LED 백플레인과 성막 장비를 공유하여 다목적 생산 라인의 구현을 가능하게 하고 있습니다. 차량 전면 유리에 내장된 투명 센서는 탑승 현황 및 환경 데이터를 첨단 운전자 보조 시스템(ADAS)에 제공하기 시작했으며, 이는 그 가치가 단일 부품에서 통합된 기능으로 전환되고 있음을 보여줍니다.
2025년 시점에서 인듐주석산화물(ITO)은 투명 전자 시장 점유율의 51.35%를 차지하며, LCD/TFT 및 터치패널 공급망 전반에서 확고한 입지를 뒷받침했습니다. 그러나 은 나노와이어 복합재료와 금속 메쉬가 이러한 우위를 서서히 잠식하고 있으며, 2031년까지 연평균 성장률(CAGR) 21.90%로 시장 점유율을 확대할 것으로 예측됩니다. 실험실 환경에서 제작된 디바이스의 경우, 투과율 90%에서 26Ω/sq의 시트 저항이 입증되었으며, 120%의 변형 하에서도 저항 드리프트가 10%에 불과하여 폴더블 스마트폰이나 전자 피부 패치에 적용할 수 있습니다. 용도에 따른 최적화가 소재 선정의 지침이 됩니다. PEDOT, PSS 등의 전도성 폴리머는 현재 저비용의 유연한 디스플레이용으로 사출 성형된 플라스틱 기판에 코팅되어 있는 반면, 그래핀은 웨어러블 생체 센서의 열 관리 및 신호 균일성 문제를 해결하고 있습니다. 투명 세라믹은 가혹한 환경 하의 광학 용도에서 틈새 수요를 확보하고 있으며, 탄소나노튜브 하이브리드는 광학적 투명성이 필수적인 전자기파 차폐층 분야에서 두각을 나타내고 있습니다.
지역별 분석
아시아태평양은 디스플레이용 대규모 제조 공장과 중국 내 세계 최대 규모의 BIPV(건축 통합형 태양광 발전) 프로그램을 기반으로 2025년 매출의 42.80%를 차지했습니다. 도시의 대기질 목표와 재생에너지 용량을 연계하는 정부의 인센티브 덕분에 상하이나 선전 등 대도시에서는 투명 태양광 파사드의 도입이 촉진되고 있습니다. 일본과 한국의 기업들이 OLED 연구를 주도하고 있으며, 투과율과 화소 밀도 측면에서 새로운 기준을 제시하는 프로토타입을 정기적으로 발표하고 있습니다.
북미에서는 자율주행차용 소프트웨어 분야의 리더십을 바탕으로, 투명 HUD와 다수의 센서가 탑재된 전면 유리에 대한 수요 증가를 가속화하고 있습니다. 건물의 에너지 규제는 주마다 다르지만, 전반적으로 상업시설 리모델링 시 일렉트로크로믹 유리의 채택을 뒷받침하고 있습니다. 유럽의 엄격한 2030 기후 의제에 따라 스마트 유리와 BIPV가 리모델링 자금의 핵심으로 자리 잡으면서, 파사드 시공업체와 소재 전문 기업 간의 국경을 초월한 제휴가 급증하고 있습니다.
중동 및 아프리카에서는 스마트 시티에 대한 투자로 인해 랜드마크적인 프로젝트에 디지털 사이니지, 적응형 차광 시스템, 태양광 유리가 통합됨에 따라 2026년부터 2031년까지 연평균 성장률(CAGR) 22.15%를 나타낼 것으로 예측됩니다. 사우디아라비아의 ‘비전 2030’에서는 투명한 디스플레이 벽과 인터랙티브 콘텐츠를 융합한 몰입형 문화유산 시설에 수십억 달러 규모의 예산이 배정되어 있습니다. 라틴아메리카는 풍부한 일사량이 도시 지역의 고층 빌딩 개발에 투명형 태양광 발전의 도입과 맞물려 미개척 시장으로 부상하고 있으나, 공급망상의 과제와 자금 조달 비용이 단기적인 보급을 저해하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the transparent electronics market size was valued at USD 2.78 billion in 2025 and estimated to grow from USD 3.37 billion in 2026 to reach USD 8.86 billion by 2031, at a CAGR of 21.30% during the forecast period (2026-2031).
This report is Segmented by Product (Transparent Displays, Transparent Solar Panels, Smart, and More), Material Type (Indium Tin Oxide (ITO), Alternative TCOs (AZO, FTO), and More), Technology (LCD/TFT, and More), End-User Application (Consumer Electronics, Automotive and Transportation, Aerospace and Defense, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Transparent Electronics Market Trends and Insights
Net-zero building codes driving smart-window integration
European legislation that mandates nearly zero-energy performance for all new structures by 2030 is pushing architects toward electrochromic glazing that dynamically modulates solar gain. Pilot installations across Germany and Scandinavia have shown cooling-energy cuts exceeding 20%, and newer liquid-flow electrochromic designs added the ability to shift interior temperatures 5 °C seasonally. Integration with building-automation systems is becoming standard, opening revenue streams for sensor and controls suppliers alongside panel manufacturers. Medium-term growth prospects are reinforced by funding under national renovation programs, which reserve dedicated budgets for envelope upgrades that include smart windows.
Autonomous vehicles accelerating transparent display adoption
Automakers are turning to large-format transparent head-up displays (HUDs) that project navigation, driver-assist, and infotainment data directly onto windshields. Recent micro-LED prototypes have achieved 85% transparency while retaining 1,000-nit brightness, overcoming prior glare limitations in variable daylight. This capability satisfies stringent driver-distraction and safety norms in the United States, Japan, and the EU, triggering design wins in mid-segment electric vehicles slated for 2026 release. Short-term demand is amplified by the transition to autonomous Level 3 functions, which require larger visual fields for system-status information.
Indium supply vulnerabilities threatening production stability
ITO remains the workhorse transparent conductor, yet more than half of refined indium originates from a single country, exposing panel producers to sudden spot-price swings above 30% per annum. These spikes compress display-maker margins and delay capacity-expansion decisions. Materials firms are responding with silver-nanowire alternatives that exhibit sub-30 Ω/sq resistance at 90% transmittance while tolerating 1,000 bending cycles. The transition, however, requires new curing temperatures and patterning chemistries, prolonging qualification cycles for high-volume production.
Other drivers and restraints analyzed in the detailed report include:
- Retail transformation through transparent digital signage
- Building-integrated photovoltaics expanding transparent solar innovation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transparent displays generated the largest revenue share in 2025 at 42.65%, yet transparent solar panels are projected to grow at a 25.05% CAGR to 2031, propelled by building codes that reward on-site generation. A Swiss venture introduced a 400 W glass-like BIPV module that blends into standard facades without altering exterior aesthetics. The transparent electronics market size for solar panels is forecast to reach USD 2.26 billion by 2031, reflecting their dual role as power generators and daylighting surfaces. Product diversification now extends to transparent conductive films that underpin touch sensors and heaters, as well as rugged transparent ceramics for aerospace shielding. Smart-window units equipped with dynamic tinting continue to gain traction in commercial real estate, aided by operating-cost reductions that shorten payback periods to under five years in warm climates.
The transparent electronics market increasingly values interoperability between product categories. Emerging tandem solar cells share deposition tools with micro-LED backplanes, enabling multi-purpose manufacturing lines. Transparent sensors embedded in vehicle windshields are beginning to feed occupancy and environment data into advanced driver-assistance systems, illustrating how value migrates from stand-alone components to integrated functions.
Indium tin oxide accounted for 51.35% of transparent electronics market share in 2025, underscoring its entrenched position across LCD/TFT and touch-panel supply chains. Nevertheless, silver-nanowire composites and metal meshes are expected to erode this lead, climbing at 21.90% CAGR through 2031. Lab devices have demonstrated 26 Ω/sq sheet resistance at 90% transmittance, with only 10% resistance drift under 120% strain, making them viable for foldable phones and e-skin patches. Application-specific optimisation guides material choice. Conductive polymers such as PEDOT:PSS now coat injection-moulded plastic substrates for low-cost, flexible displays, while graphene manages heat and signal-uniformity challenges in wearable biosensors. Transparent ceramics secure niche demand in harsh-environment optics, and carbon-nanotube hybrids are emerging in electromagnetic-shielding layers where optical transparency is non-negotiable.
Complete Report Scope:
- By Product
- Transparent Displays
- Transparent Solar Panels
- Smart Windows/Smart Glass
- Transparent Conductive Films
- Transparent Ceramics and Aluminum
- Transparent Sensors and Others
- By Material Type
- Indium Tin Oxide (ITO)
- Alternative TCOs (AZO, FTO)
- Silver Nanowire and Metal Mesh
- Carbon-Based Nanomaterials (Graphene, CNT)
- Conductive Polymers (PEDOT:PSS)
- By Technology
- LCD/TFT
- OLED and micro-OLED
- Quantum-Dot and micro-LED
- Thin-Film Photovoltaic (CIGS, Perovskite)
- Electrochromic and SPD
- By End-user Application
- Consumer Electronics
- Automotive and Transportation
- Building and Infrastructure
- Energy and Utilities (BIPV, Agrivoltaics)
- Aerospace and Defense
- Healthcare and Wearables
- Retail and Digital Signage
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics (Denmark, Sweden, Norway, Finland)
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Southeast Asia
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia Pacific commanded 42.80% of 2025 revenue, anchored by high-volume fabs for displays and the world's largest BIPV programme in China. Government incentives that link urban air-quality targets to renewable-energy capacity fuel adoption of transparent solar facades in megacities such as Shanghai and Shenzhen. Japanese and South Korean firms dominate OLED research, regularly showcasing prototypes that set new benchmarks in transmittance and pixel density.
North America leverages its leadership in autonomous-vehicle software to accelerate demand for transparent HUDs and sensor-rich windshields. Building-energy rules vary by state, yet collectively favour electrochromic adoption in commercial retrofits. Europe's strict 2030 climate agenda places smart glass and BIPV at the centre of renovation funding, driving a surge of cross-border partnerships between facade contractors and materials specialists.
The Middle East and Africa is forecast to grow at 22.15% CAGR from 2026 to 2031 as smart-city investments integrate digital signage, adaptive shading and solar glass in landmark projects. Saudi Arabia's Vision 2030 allocates multi-billion-dollar budgets to immersive heritage sites that blend transparent display walls with interactive content. Latin America represents an untapped frontier where abundant solar irradiance aligns with transparent PV adoption in urban high-rise developments, although supply-chain hurdles and financing costs temper near-term uptake.
- BOE Technology Group Co., Ltd.
- LG Display Co., Ltd.
- Samsung Display Co., Ltd.
- Corning Incorporated
- AGC Inc.
- NSG Group (Pilkington)
- Saint-Gobain SA
- Ubiquitous Energy Inc.
- Brite Solar Inc.
- ClearLED Ltd.
- Panasonic Holdings Corp.
- Cambrios Technology Corp.
- Surmet Corporation
- 3M Company
- DuPont de Nemours Inc.
- PPG Industries Inc.
- Guardian Industries Holdings
- Shenzhen Nexnovo Technology Co., Ltd.
- Shenzhen AuroLED Technology Co., Ltd.
- Street Communication Inc.
- Apple Inc. (Transparent AR Glass R&D)
- JX Nippon Mining and Metals Corp.
- Heraeus Holding GmbH
- American Elements Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Net-Zero Building Codes Accelerating Smart-Window Adoption in EU
- 4.2.2 Rapid Uptake of Head-Up Displays in Autonomous and EV Cockpits (North America)
- 4.2.3 AR-Enabled Transparent Retail Signage Surge in Asia's Tier-1 Cities
- 4.2.4 Building-Integrated PV Mandates Spurring Transparent Solar Panels in China
- 4.2.5 Wearable Medical Sensors Requiring Flexible Transparent Conductors
- 4.3 Market Restraints
- 4.3.1 Indium Price Volatility and Supply Concentration
- 4.3.2 Low Yield Scaling Large-Area Transparent OLED Panels
- 4.3.3 E-waste Rules on Heavy-Metal Oxide Films in Europe
- 4.3.4 High CapEx for Magnetron Sputtering and ALD Equipment
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Product
- 5.1.1 Transparent Displays
- 5.1.2 Transparent Solar Panels
- 5.1.3 Smart Windows/Smart Glass
- 5.1.4 Transparent Conductive Films
- 5.1.5 Transparent Ceramics and Aluminum
- 5.1.6 Transparent Sensors and Others
- 5.2 By Material Type
- 5.2.1 Indium Tin Oxide (ITO)
- 5.2.2 Alternative TCOs (AZO, FTO)
- 5.2.3 Silver Nanowire and Metal Mesh
- 5.2.4 Carbon-Based Nanomaterials (Graphene, CNT)
- 5.2.5 Conductive Polymers (PEDOT:PSS)
- 5.3 By Technology
- 5.3.1 LCD/TFT
- 5.3.2 OLED and micro-OLED
- 5.3.3 Quantum-Dot and micro-LED
- 5.3.4 Thin-Film Photovoltaic (CIGS, Perovskite)
- 5.3.5 Electrochromic and SPD
- 5.4 By End-user Application
- 5.4.1 Consumer Electronics
- 5.4.2 Automotive and Transportation
- 5.4.3 Building and Infrastructure
- 5.4.4 Energy and Utilities (BIPV, Agrivoltaics)
- 5.4.5 Aerospace and Defense
- 5.4.6 Healthcare and Wearables
- 5.4.7 Retail and Digital Signage
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Nordics (Denmark, Sweden, Norway, Finland)
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 Southeast Asia
- 5.5.3.6 Australia
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Gulf Cooperation Council Countries
- 5.5.5.2 Turkey
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BOE Technology Group Co., Ltd.
- 6.4.2 LG Display Co., Ltd.
- 6.4.3 Samsung Display Co., Ltd.
- 6.4.4 Corning Incorporated
- 6.4.5 AGC Inc.
- 6.4.6 NSG Group (Pilkington)
- 6.4.7 Saint-Gobain SA
- 6.4.8 Ubiquitous Energy Inc.
- 6.4.9 Brite Solar Inc.
- 6.4.10 ClearLED Ltd.
- 6.4.11 Panasonic Holdings Corp.
- 6.4.12 Cambrios Technology Corp.
- 6.4.13 Surmet Corporation
- 6.4.14 3M Company
- 6.4.15 DuPont de Nemours Inc.
- 6.4.16 PPG Industries Inc.
- 6.4.17 Guardian Industries Holdings
- 6.4.18 Shenzhen Nexnovo Technology Co., Ltd.
- 6.4.19 Shenzhen AuroLED Technology Co., Ltd.
- 6.4.20 Street Communication Inc.
- 6.4.21 Apple Inc. (Transparent AR Glass R&D)
- 6.4.22 JX Nippon Mining and Metals Corp.
- 6.4.23 Heraeus Holding GmbH
- 6.4.24 American Elements Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


