

|
시장보고서
상품코드
2122578
치과 진료 관리 소프트웨어 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Dental Practice Management Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 치과 진료 관리 소프트웨어 시장 규모는 2025년에 23억 6,000만 달러로 평가되었습니다. 2026년에 26억 2,000만 달러에 달하고, 2031년까지 44억 4,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년에 걸쳐 CAGR 11.12%로 성장할 전망입니다.

본 보고서는 제공 형태(On-Premise 등), 구독 모델(영구 라이선스 및 구독/SaaS), 기능(환자와의 소통 및 참여 등), 진료소 규모(개인 개업(1-2명 체제) 등), 최종 사용자(치과, 병원 등),및 지역(북미 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 치과 진료 관리 소프트웨어 시장 동향 및 인사이트
전 세계적으로 증가하는 구강 질환의 부담
치료되지 않은 충치는 전 세계 25억 명의 성인에게 영향을 미치고 있으며, 치주질환은 10억 명에게 영향을 미치고 있습니다. 그러나 저·중소득 국가에서 1차 진료에 구강 보건을 포함하고 있는 비율은 고작 23%에 불과합니다. 현재 각국 정부는 진료비 지급을 전자 치과 차트 도입과 연계하고 있으며, 그 예로 인도에서는 2025년 3월까지 모든 지역 병원이 디지털 차트를 도입하도록 의무화했습니다. 미국의 치과 진료소에서는 내장형 선별 검사 프로토콜을 활용하여 환자 1인당 연간 340달러 상당의 만성 질환 관리 코드를 청구하고 있습니다. 원격 치과 진료 건수는 2019년 5만 건 미만에서 2024년에는 410만 건으로 증가했습니다. 이는 보험사가 원격 진료 평가에 대해 내원 진료비의 85%를 상환하고 있는 것이 뒷받침되고 있습니다. 원격 트리아지에 대한 수요가 증가함에 따라, 환자와의 커뮤니케이션 기능은 단순한 추가 옵션에서 구매의 핵심 기준으로 그 위상이 변화하고 있습니다. 위험 평가 워크플로를 통합한 공급업체는 가치 기반 의료 계약에서 우선적으로 선정되고 있습니다.
디지털 건강 기록 및 상호운용성 기준 도입
데이터 교환을 방해할 경우 최대 100만 달러의 민사 벌금이 부과되는 규정이 2023년 10월에 시행되었습니다. 2025년 중반까지 미국 치과 진료소의 68%가 구조화된 치료 계획을 의료용 전자 건강 기록(EHR)으로 전송할 수 있게 되었습니다(2022년 12%에서 증가). 2027년부터 메디케어 어드밴티지가 SNODENT 코드가 포함된 청구를 수용함에 따라 변환에 따른 마찰이 해소되고, 공급업체는 확장된 용어 집합을 지원해야 할 압박을 받게 될 것입니다. 유럽의 GDPR(EU 개인정보보호규정)은 지역별 데이터 상주 요건의 필요성을 더욱 강화하고 있으며, 다중 지점 그룹의 경우 인증받은 클라우드 공급자가 기본 선택지가 되고 있습니다. 상호 운용성은 단순한 기술적 부가가치에서 생존과 직결된 필수 요건으로 변화하여, 공급업체의 로드맵 및 구매 결정을 좌우하는 요소가 되고 있습니다.
데이터 개인정보 보호 및 사이버 보안 규정 준수의 복잡성
2024년에는 치과 분야의 정보 유출로 인해 120만 건의 기록이 유출되었으며, HIPAA에 따른 평균 합의금은 47만 5,000달러에 달했습니다. 랜섬웨어로 인한 사고는 급증했으며, 백업 체계가 미흡했던 탓에 피해를 입은 진료소의 41%가 공격자에게 몸값을 지불했습니다. EU의 GDPR(EU 개인정보보호규정)에 따른 과징금은 전 세계 매출액의 4%에 달할 수 있으며, 2024년에는 클라우드 스토리지 설정 오류로 인해 120만 유로의 과징금이 부과된 사례가 이를 뒷받침하고 있습니다. FDA의 지침 초안에서는 진단용 소프트웨어에 대해 다중 인증과 6년간의 감사 로그 보관을 의무화하고 있어, 보안 엔지니어링 전문 지식이 부족한 소규모 벤더들은 어려운 상황에 몰리고 있습니다. 규정 준수 부담으로 인해 치과 진료소는 인증을 받은 클라우드 제공업체를 이용해야만 하는 한편, 직원의 재교육과 워크플로우 재설계도 시급히 추진해야 하는 상황에 놓여 있습니다.
부문별 분석
2025년에도 On-Premise 배포는 매출의 45.56%를 차지했으며, 그 대부분은 2020년 이전에 영구 라이선스를 구매한 진료소에서 비롯된 것입니다. 이 기존 시스템을 마이그레이션할 경우, 진료실 5개 규모의 진료소에서는 데이터 변환 및 교육에 1만 8,000달러의 비용이 발생할 수 있습니다. 그러나 치과 서비스 기관들이 중앙 집중식 청구 및 분석을 위해 멀티테넌트 아키텍처를 표준화하고 있는 것을 배경으로, 클라우드 솔루션은 연평균 14.25%의 성장률이 예상됩니다. 구독형 비즈니스 모델은 사이버 보안, 중복성,업데이트가 패키지로 제공되므로, IT 인력을 보유하지 않은 개인 개업 치과에 매력적입니다. HHS(미국 보건복지부)의 다단계 인증 도입 기한으로 인해 시스템 현대화가 시급해졌으며, 2024년부터 2025년에 걸쳐 전환이 가속화되었습니다. 연방 정부의 인프라 자금 지원으로 94%의 진료소에서 100 Mbps를 초과하는 접속이 가능해지면서, 지방 지역의 대역폭 제약은 점차 완화되고 있습니다. 자동 업데이트 주기에 따라 취약점은 공개 후 72시간 이내에 수정되는데, 이는 대부분의 On-Premise 사용자에게는 달성하기 어려운 수준입니다. 여전히 인터넷 회선 중단이나 구독에 대한 피로감을 이유로 꼽는 진료소도 소수 존재하지만, 총 소유 비용(TCO) 측면에서는 클라우드 플랫폼으로의 전환이 결정적으로 우위를 점하고 있습니다.
전용 설치 프로그램이 필요 없이 브라우저에서 작동하는 웹 기반 하이브리드형 솔루션은 과도기적 틈새 시장을 충족시키고 있지만, 오프라인 상태에서의 내구성이 부족합니다. 각 벤더들은 신중한 도입층을 확보하기 위해 엣지 캐싱 및 로컬 동기화 기능을 내세우고 있습니다. 기능의 동등성이 향상됨에 따라, 규제 준수 및 설비 투자(CapEx) 절감을 배경으로 치과 진료 관리 소프트웨어 시장 내 클라우드 서비스 규모는 2029년까지 On-Premise형의 매출액을 넘어설 것으로 전망됩니다. 현재 경쟁 전략은 진료소의 다운타임을 최소화하기 위한 마이그레이션 도구와 세심한 도입 지원에 중점을 두고 있습니다. 레거시 데이터베이스 변환 및 직원 교육을 효율화하는 벤더들은 시장 점유율을 급성장하고 있습니다.
SaaS는 2025년에 매출의 60.53%를 차지했으며, 진료소가 현금 흐름에 맞춘 예측 가능한 월별 지출을 선호함에 따라 연평균 성장률(CAGR) 13.85%로 증가할 것으로 전망됩니다. 한때 8,000-1만 5,000달러에 18-22%의 유지보수 비용이 부과되던 영구 라이선스는 CFO들이 혁신 지연이나 업그레이드의 번거로움으로 인한 가치 하락을 우려하고 있어 감소 추세를 보이고 있습니다. 패터슨 컴퍼니즈는 2024 회계연도에 구독 수익이 27% 증가한 반면, 영구 라이선스 매출은 11% 감소했다고 보고했으며, 이에 따라 2026년부터 ‘Eaglesoft’의 가격 체계를 구독 전용으로 전환할 방침을 밝혔습니다.
단계적인 SaaS 패키지를 통해 벤더는 AI 분석, 이미지 통합, API 액세스 등의 업셀링이 가능해집니다. Open Dental의 ‘진료소당 199-399달러’라는 가격대는 긴 판매 주기를 거치지 않고도 클리닉이 스스로 기능을 선택할 수 있는 구조를 보여줍니다. 엔터프라이즈용 DSO(치과 진료소 운영 조직)의 경우, 볼륨 할인을 통해 소프트웨어 비용을 22% 절감할 수 있을 뿐만 아니라, 벤치마킹을 위한 데이터 레이크를 통합할 수 있습니다. 구독 갱신에 따라 협상력이 집중되는 가운데, 벤더들은 고객 성공 팀의 강화와 고객 이탈률 감소에 주력하고 있습니다. 분석가들은 영구 라이선스에 기인한 치과 진료 관리 소프트웨어 시장 규모가 2030년까지 10억 달러 미만으로 떨어질 것으로 예측하고 있으며, 이는 수익 모델의 구조적 재편을 시사합니다.
지역별 분석
2025년, 북미는 전 세계 매출의 45.13%를 차지했습니다. 이는 원격 치과 진료에 대한 메디케어 어드밴티지의 환급 및 각 주 메디케이드의 전자 사전 승인 의무화에 힘입은 결과입니다. 암호화 및 다단계 인증을 의무화하는 HIPAA 보안 업데이트로 인해 진료소 전반에 걸친 클라우드 전환이 가속화되었습니다. 캐나다에서는 치과 의료의 점진적인 확대에 따라 국가 EDI 표준에 기반한 전자 청구가 의무화되어 11,000개 진료소에서 도입이 촉진되고 있습니다. 멕시코의 사회보장 네트워크는 2024년에 340개의 진료소를 추가했으며, 소프트웨어 보조금으로 12억 멕시코 페소(7,000만 달러)가 배정되었습니다. 미국 치과 진료소의 94%에서 100 Mbps를 초과하는 광대역 보급률이 달성됨에 따라, 오랫동안 남아 있던 기술적 장벽이 해소되었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 15.52%로 가장 빠르게 성장하는 지역이며, 그 원동력은 중국의 120억 위안(17억 달러) 규모의 지방 진료소 디지털화 기금과, 인도의 3억 4,000만 명 국민을 대상으로 한 디지털 헬스 ID 도입입니다. 일본에서는 치과 진료 보수 청구의 100% 전자화가 의무화됨에 따라, 디지털화에 소극적이었던 의료기관의 디지털화가 가속화되었습니다. 한편, 한국에서는 AI를 활용한 충치 검출에 대해 수동 검사의 90%에 해당하는 보수가 지급되므로 소프트웨어 업그레이드가 촉진되고 있습니다. 호주의 ‘My Health Record’에서는 진료소당 5,000호주달러(3,300미국달러)의 보조금이 지급되어 시스템 통합 비용 절감으로 이어지고 있습니다. 다국어 지원 SNOMED 확장 기능 및 클라우드 데이터 주권 구역을 포함한 지역별 현지화는 벤더의 성공에 매우 중요합니다.
유럽에서는 의료기기 규정(MDR)의 장벽으로 인해 발전 속도가 비교적 완만합니다. 이로 인해 제품 인증에 최대 2년이 추가로 소요되며, 경험이 풍부한 규제 대응 팀을 보유한 벤더에게 시장 점유율이 집중되고 있습니다. 독일에서는 규정을 준수하지 않는 진료소에 대해 환급 페널티가 부과되므로 소프트웨어의 신속한 업그레이드가 진행되고 있습니다. 영국에서는 NHS 소속 1만 1,000개 치과 진료소의 디지털화를 위해 1억 2,000만 파운드(1억 5,000만 달러)를 지원하여 교육비 및 전환 비용을 충당하고 있습니다. 중동 및 아프리카, 남미에서는 태블릿 기반 워크플로가 데스크톱 인프라를 우회함에 따라 모바일 우선 솔루션이 탄력을 받고 있습니다. 아랍어, 포르투갈어, 스와힐리어 인터페이스를 현지 언어로 지원한 벤더들은 얼리 모버로서의 우위를 점하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the dental practice management software market size is projected to be USD 2.36 billion in 2025, USD 2.62 billion in 2026, and reach USD 4.44 billion by 2031, growing at a CAGR of 11.12% from 2026 to 2031.
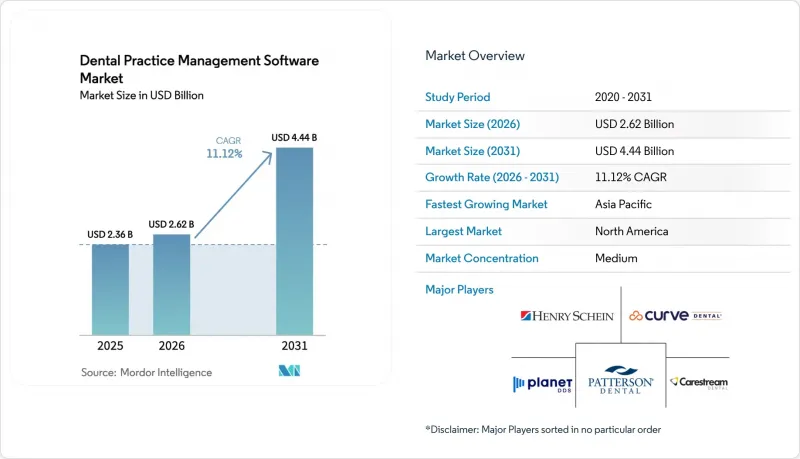
This report is Segmented by Delivery Mode (On-Premises, and More), Subscription Model (Perpetual License and Subscription / SaaS), Functionality (Patient Communication & Engagement, and More), Practice Size (Solo Practices (1-2 Ops), and More), End User (Dental Clinics, Hospitals, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Dental Practice Management Software Market Trends and Insights
Rising Global Burden of Oral Diseases
Untreated dental caries affects 2.5 billion adults worldwide, while periodontal disease impacts 1 billion people, yet only 23% of low- and middle-income countries integrate oral health into primary care. Governments now tie reimbursement to electronic dental records, illustrated by India's mandate that all district hospitals adopt digital charting by March 2025. U.S. practices use embedded screening protocols to bill chronic-care codes worth USD 340 per patient annually. Teledentistry visits rose from under 50,000 in 2019 to 4.1 million in 2024, helped by payers reimbursing virtual assessments at 85% of the in-office rate. Demand for remote triage elevates patient-communication modules from optional add-ons to core purchase criteria. Vendors that embed risk-assessment workflows gain preference among value-based care contracts.
Adoption of Digital Health Records & Interoperability Standards
Civil monetary penalties of up to USD 1 million for blocking data exchange took effect in October 2023. By mid-2025, 68% of U.S. dental practices could transmit structured treatment plans to medical EHRs, up from 12% in 2022. Acceptance of SNODENT-coded claims by Medicare Advantage from 2027 removes translation friction and pushes vendors to support the expanded terminology set. Europe's GDPR reinforces the need for regional data residency, making certified cloud providers the default for multi-site groups. Interoperability has shifted from technical nicety to existential requirement, dictating vendor roadmaps and purchase decisions.
Data-Privacy & Cyber-Security Compliance Complexities
Dental breaches exposed 1.2 million records in 2024, with average HIPAA settlements of USD 475,000. Ransomware incidents rose sharply; 41% of affected practices paid attackers due to inadequate backups. EU GDPR fines can reach 4% of global turnover, demonstrated by a EUR 1.2 million penalty issued in 2024 for misconfigured cloud storage. Draft FDA guidance now requires multi-factor authentication and six-year audit logs for diagnostic software, squeezing small vendors without security engineering depth. Compliance burdens push clinics toward certified cloud providers but force retraining and workflow redesign.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Cloud-Based SaaS Models with Lower CapEx
- Integration with Imaging, CAD/CAM & Chair-Side Systems
- Lack of Standardized Clinical Coding & Workflow Harmonization
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
On-premises deployments retained 45.56% revenue in 2025, largely from clinics that purchased perpetual licenses before 2020. Migrating this installed base can cost a five-operatory practice USD 18,000 in data conversion and training. Yet cloud solutions are projected to grow 14.25% annually, propelled by dental service organizations standardizing multi-tenant architectures for centralized billing and analytics. Subscription economics appeal to solo practices lacking IT staff because cybersecurity, redundancy, and updates are bundled. The HHS multi-factor authentication deadline made modernization urgent, accelerating conversions in 2024-2025. Rural bandwidth constraints are easing as federal infrastructure funds extend >100 Mbps access to 94% of clinics. Automatic update cycles mitigate vulnerabilities within 72 hours of disclosure, a level unattainable for most on-premises users. While a minority of practices still cite internet outages and subscription fatigue, the total cost of ownership has tilted decisively toward cloud platforms.
Web-based hybrids that run in browsers without dedicated installers fill a transitional niche but lack offline resilience. Vendors position edge-caching or local-sync features to win cautious adopters. As feature parity improves, the dental practice management software market size for cloud offerings is set to surpass on-premises revenue before 2029, driven by regulatory compliance and lower CapEx. Competitive strategies now focus on migration tools and white-glove onboarding to minimize clinic downtime. Vendors that streamline legacy database conversion and staff training gain accelerated share.
SaaS captured 60.53% revenue in 2025 and is forecast to rise at 13.85% CAGR as practices favor predictable monthly spending aligned with cash flow. Perpetual licenses once priced at USD 8,000-15,000 plus 18-22% maintenance are declining because CFOs discount the value of slower innovation and higher upgrade friction. Patterson Companies reported 27% subscription revenue growth in fiscal 2024 while perpetual sales dropped 11%, prompting a pivot to subscription-only pricing for Eaglesoft beginning 2026.
Tiered SaaS packaging lets vendors upsell AI analytics, imaging integration, and API access. Open Dental's USD 199-399 per-provider tiers illustrate how clinics self-select functionality without lengthy sales cycles. For enterprise DSOs, volume pricing unlocks 22% software savings and centralizes data lakes for benchmarking. As subscription renewals concentrate bargaining power, vendors emphasize customer success teams and low churn. Analysts expect the dental practice management software market size stemming from perpetual licenses to fall below USD 1 billion by 2030, signaling structural revenue model realignment.
Complete Report Scope:
- By Delivery Mode
- On-premises
- Web-based
- Cloud-based
- By Subscription Model
- Perpetual License
- Subscription / SaaS
- By Functionality
- Patient Communication & Engagement
- Appointment Scheduling & Calendar
- Billing & Invoicing
- Insurance & Claims Management
- Treatment Planning & Charting
- Imaging & Diagnostics Integration
- Analytics & Business Intelligence
- By Practice Size
- Solo Practices (1-2 ops)
- Small Group Practices (3-9 ops)
- Large Group Practices (10+ ops)
- Dental Service Organizations (DSOs)
- By End User
- Dental Clinics
- Hospitals & Specialty Dental Centers
- Academic & Research Institutes
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 45.13% of global revenue in 2025, supported by Medicare Advantage reimbursement for teledentistry and state Medicaid e-prior authorization mandates. HIPAA security updates requiring encryption and multi-factor authentication accelerated cloud migrations across clinics. Canada's phased dental-care expansion obliges electronic claims via the national EDI standard, spurring adoption among 11,000 practices. Mexico's social-security network added 340 clinics in 2024, with MXN 1.2 billion (USD 70 million) earmarked for software subsidies. Broadband penetration exceeding 100 Mbps coverage for 94% of U.S. dental offices removes a lingering technical barrier.
Asia-Pacific is the fastest-growing region at 15.52% CAGR through 2031, anchored by China's CNY 12 billion (USD 1.7 billion) rural-clinic digitization fund and India's 340 million-citizen digital-health identifier rollout. Japan's mandate for 100% electronic dental claims accelerated digitization among holdouts, while South Korea reimburses AI-assisted caries detection at 90% of manual rates, incentivizing software upgrades. Australia's My Health Record grants of AUD 5,000 (USD 3,300) per clinic reduce integration costs. Regional localization, including multi-language SNOMED extensions and cloud data-sovereignty zones, is critical for vendor success.
Europe advances at a steadier pace due to Medical Device Regulation hurdles, which add up to two years to product certification and concentrate share among vendors with seasoned regulatory teams. Germany enforces reimbursement penalties for non-compliant clinics, prompting rapid software upgrades. The United Kingdom funds GBP 120 million (USD 150 million) to digitize 11,000 NHS dental practices, covering training and migration costs. Mobile-first solutions gain traction in Middle East, Africa, and South America, where tablet-based workflows bypass desktop infrastructure. Vendors that localize Arabic, Portuguese, and Swahili interfaces capture early-mover advantage.
- ABELDent Inc.
- ACE Dental Software
- CareStack (Good Methods Global)
- Carestream Dental
- ClearDent
- Curve Dental
- DentiMax LLC
- Dovetail Dental Software
- Exan Software (axiUm)
- iDentalSoft
- MOGO
- NextGen Healthcare
- Open Dental Software
- Patterson Companies Inc. (Eaglesoft)
- Planet DDS Inc. (Denticon)
- Practice-Web Inc.
- RxNT Inc.
- Software of Excellence Intl.
- tab32
- Henry Schein Inc. (Dentrix)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising global burden of oral diseases
- 4.2.2 Adoption of digital health records & interoperability standards
- 4.2.3 Expansion of cloud-based SaaS models with lower CapEx
- 4.2.4 Integration with imaging, CAD/CAM & chair-side systems
- 4.2.5 AI-powered clinical decision add-ons & predictive analytics
- 4.2.6 API marketplaces enabling third-party app ecosystems
- 4.3 Market Restraints
- 4.3.1 Data-privacy & cyber-security compliance complexities
- 4.3.2 Lack of standardized clinical coding & workflow harmonization
- 4.3.3 Rising vendor lock-in risk as ecosystems consolidate
- 4.3.4 Limited IT budgets among small independent practices
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Delivery Mode
- 5.1.1 On-premises
- 5.1.2 Web-based
- 5.1.3 Cloud-based
- 5.2 By Subscription Model
- 5.2.1 Perpetual License
- 5.2.2 Subscription / SaaS
- 5.3 By Functionality
- 5.3.1 Patient Communication & Engagement
- 5.3.2 Appointment Scheduling & Calendar
- 5.3.3 Billing & Invoicing
- 5.3.4 Insurance & Claims Management
- 5.3.5 Treatment Planning & Charting
- 5.3.6 Imaging & Diagnostics Integration
- 5.3.7 Analytics & Business Intelligence
- 5.4 By Practice Size
- 5.4.1 Solo Practices (1-2 ops)
- 5.4.2 Small Group Practices (3-9 ops)
- 5.4.3 Large Group Practices (10+ ops)
- 5.4.4 Dental Service Organizations (DSOs)
- 5.5 By End User
- 5.5.1 Dental Clinics
- 5.5.2 Hospitals & Specialty Dental Centers
- 5.5.3 Academic & Research Institutes
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 ABELDent Inc.
- 6.3.2 ACE Dental Software
- 6.3.3 CareStack (Good Methods Global)
- 6.3.4 Carestream Dental LLC
- 6.3.5 ClearDent
- 6.3.6 Curve Dental Inc.
- 6.3.7 DentiMax LLC
- 6.3.8 Dovetail Dental Software
- 6.3.9 Exan Software (axiUm)
- 6.3.10 iDentalSoft
- 6.3.11 MOGO Inc.
- 6.3.12 NextGen Healthcare Inc.
- 6.3.13 Open Dental Software
- 6.3.14 Patterson Companies Inc. (Eaglesoft)
- 6.3.15 Planet DDS Inc. (Denticon)
- 6.3.16 Practice-Web Inc.
- 6.3.17 RxNT Inc.
- 6.3.18 Software of Excellence Intl.
- 6.3.19 tab32
- 6.3.20 Henry Schein Inc. (Dentrix)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


