

|
시장보고서
상품코드
2122588
세포 용해 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cell Lysis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
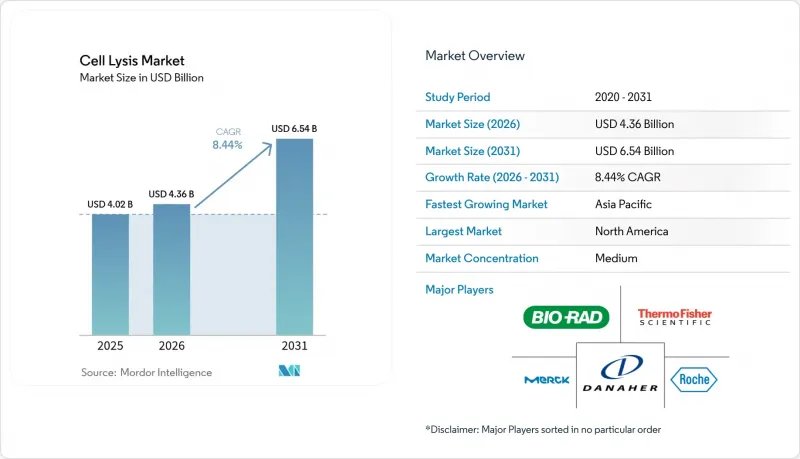
에 의하면, 세포 용해 시장 규모는 2025년 40억 2,000만 달러로 평가되었습니다. 2026년에는 43억 6,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 8.44%로 성장을 지속하여, 2031년에는 65억 4,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 제품 유형(장비(호모지나이저 등) 및 시약), 세포 유형(포유류 세포, 미생물 세포 등), 용해 방법(기계적, 효소적 등),용도(단백질 정제·단백질체학 등), 최종 사용자(생명공학·바이오의약품 기업 등), 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 세포 용해 시장 동향 및 인사이트
단일 세포 오믹스 분야의 시료 전처리 수요 급증
단일 세포 시퀀싱 및 단백질체학의 급속한 성장에 따라, 세포 용해에 대한 요구 사항은 극도로 온화한 처리와 오염 관리로 재정의되었습니다. 첨단 액적 및 마이크로웰 플랫폼을 통해 현재 수천 개의 세포를 동시에 처리할 수 있게 되었으며, 다운스트림 공정의 바코딩을 위해 RNA 및 단백질의 무결성을 유지하는 시약의 배합이 요구되고 있습니다. 각 벤더사는 서브마이크로리터 단위의 반응 부피에 맞추어 조정된 효소 버퍼와 라이브러리 준비 주기를 10시간 미만으로 단축하는 마이크로플루이딕스 하드웨어를 제공함으로써 이러한 수요에 부응하고 있습니다. 현재 임상 실험실에서는 이러한 키트를 활용하여 비침습적인 종양 프로파일링을 수행하고 있으며, 이로 인해 대상 세포 용해 시장 규모가 확대되고 있습니다. 시약의 화학적 특성과 소모품 설계 간의 지속적인 피드백을 통해 프로토콜의 표준화가 가속화되고, 다기관 간 재현성과 규제 당국의 신뢰도가 높아지고 있습니다.
확대되는 바이오로직스 및 바이오시밀러 파이프라인
블록버스터 항체의 특허 만료를 계기로 제조 능력 확충이 진행되고 있으며, 고세포 밀도의 포유류 배양물을 처리할 수 있는 대용량이자 확장 가능한 세포 용해 하드웨어에 대한 수요가 높아지고 있습니다. 아시아태평양의 시설은 스테인리스 스틸 및 일회용 제품의 총 용량이 470만 리터 이상을 차지하고 있어, 견고한 균질기 및 마이크로플루이다이저에 대한 지역적 수요를 뒷받침하고 있습니다. 바이오시밀러 규제 프로세스에서는 세포 내 제품의 검증되고 일관된 방출이 요구되며, 이에 따라 제조업체들은 실시간 모니터링 기능을 통합한 밀폐형 자동 용해 스키드의 도입을 촉진하고 있습니다. 연속 관류로 1 g/L/일 이상의 역가가 달성됨에 따라, 당화 패턴을 유지하고 응집을 최소화하기 위해서는 온화한 용해가 필수적입니다. 시약 공급업체는 장기적인 구매를 보장하는 다중 로트 적격성 평가 프로그램의 혜택을 받고 있습니다.
엄격한 바이오프로세스 밸리데이션 및 QA/QC 프로토콜
FDA가 실시간 방출 시험을 점점 더 중요시함에 따라, 제조업체는 규모나 환경 변수를 초월하여 용해의 일관성을 입증해야만 하며, 이로 인해 개발 기간이 길어지고 제품 원가가 상승하고 있습니다. 첨단 치료제 개발자는 바이러스의 완전성, 불순물 제거 및 잔류 계면활성제 프로파일을 문서화해야 하며, 많은 경우 수년에 걸친 비교 시험이 요구됩니다. 전담 품질 관리 팀을 보유하지 않은 중소규모 기업들은 큰 장벽에 직면하고 있으며, 그 결과 구매자들은 광범위한 검증 자료와 실적 데이터를 갖춘 플랫폼을 선호하는 경향이 강해지고 있습니다.
부문별 분석
루틴 워크플로우에서는 배치마다 소모품이 필요하기 때문에 2025년 매출의 52.07%를 시약이 차지했으나, 장비 시장은 2031년까지 연평균 성장률(CAGR) 12.03%로 시약 시장을 상회하는 성장이 예상되어, 자동화된 바이오프로세스에서 그 전략적 중요성이 부각되고 있습니다. 스폰서 기업들이 운영자의 개입을 최소화한 24시간 365일 연속 가동으로 전환함에 따라, 스마트 균질기 및 비드밀 방식 라이저에 대한 수요가 증가하고 있습니다. 초음파 분쇄 장치에는 현재 캐비테이션 강도를 추적하는 내장 센서가 탑재되어 있어, 고처리량 처리 중 단백질의 무결성을 보장하고 있습니다.
또한, 바이러스 입자나 유전자 변형 세포를 부드럽게 분쇄하도록 설계된 마이크로 플루이다이저 역시 장비 시장의 성장을 뒷받침하고 있습니다. 일회용 유로(flow path)를 제공하는 공급업체들은 교차 오염 위험을 줄이고 세척 검증(validation)을 효율화함으로써 카트리지 판매를 통한 장기적이고 지속적인 수익을 창출하고 있습니다. 시약 분야에서는 식물 세포 및 조류 세포에 맞추어 조정된 효소 칵테일이 주목을 받고 있는 반면, 친환경 계면활성제 대체품이 Triton X-100 사용 제한에 대응하고 있습니다. 완전한 용해 키트에는 완충액, 억제제, 프로토콜이 통합되어 있어 소규모 연구실에서도 독자적인 방법 개발을 거치지 않고도 규제 요건을 충족할 수 있습니다.
포유류 세포는 2025년 수요의 45.13%를 차지했으며, 이는 단일클론 항체 및 재조합 단백질 생산에서 중심적인 역할을 하고 있음을 반영합니다. 고밀도화가 진행되고 있는 관류형 바이오리액터에서는 견고하면서도 온화한 분쇄가 요구되는 세포 밀도가 높아지고 있기 때문에 포유류 배양용 세포 용해 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 한편, 바이러스 입자 분야는 유전자 치료 및 세포 치료 분야의 아데노연관바이러스(AAV) 및 렌티바이러스 벡터 프로그램에 힘입어 연평균 성장률(CAGR) 16.62%로 가장 빠르게 성장하고 있는 분야입니다.
바이러스 전용 용해 프로토콜에서는 효소 분해와 저전단 마이크로플루이딕스 기술을 결합하여 캡시드의 무결성을 유지하고 있습니다. 이는 다운스트림 공정에서 높은 감염력을 확보하기 위한 전제조건입니다. 미생물 세포에서는 계속해서 효소와 산업용 대사 산물이 공급되고 있으며, 비드 파쇄법 및 고압 균질화에 대한 견조한 수요가 유지되고 있습니다. 분자 농업의 노력에 힘입어 식물 세포는 당단백질의 품질을 유지하면서 견고한 세포벽을 파괴하는 독자적인 효소에 대한 틈새 시장을 개척하고 있습니다.
지역별 분석
북미는 2025년에 매출의 38.52%를 차지했으며, 탄탄한 바이오의약품 제조거점, NIH 및 BARDA의 막대한 자금 지원, 그리고 검증된 자동화를 높이 평가하는 FDA의 프레임워크에 힘입고 있습니다. 대규모 다중 생산 거점을 보유한 제조업체들은 원료의약품 제조 시설과 제제 제조 시설 간에 용해 프로토콜을 통일하는 전사적 사양을 도입하고 있습니다. 미국은 첨단 치료제 분야의 신약 승인 건수에서 계속해서 선두를 유지하고 있으며, 이는 GMP 등급 키트에 대한 국내 수요를 뒷받침하고 있습니다.
아시아태평양은 적극적인 정부 인센티브와 CDMO 활동의 확대에 힘입어 연평균 성장률(CAGR) 11.35%를 달성할 것으로 예측됩니다. 중국이 2025년까지 41억 7,000만 달러를 투자한 바이오 제조 계획은 단일클론 항체 및 유전자 치료 프로그램을 위해 밀폐형 자동 용해 모듈을 규정하는 여러 산업 단지의 기반이 되고 있습니다. 인도는 미국의 ‘바이오시큐어법(BioSecure Act)’과의 정책적 일관성과 풍부한 국내 인재 풀을 활용하여 대체 공급망의 거점으로 성장하고 있습니다. 이 지역의 제조업체들은 수출 등급의 품질을 목표로 하고 있어, 종합적인 검증 패키지를 갖춘 시스템에 대한 수요가 증가하고 있습니다.
유럽은 여전히 중요한 시장이며, 엄격한 환경 정책이 구매 결정을 좌우하고 있습니다. Triton X-100 사용 금지로 인해 생분해성 세제로의 급속한 전환이 요구되고 있으며, 선제적으로 대응한 공급업체들이 유리한 입장에 있습니다. 각 제조업체는 대체 계면활성제의 인증 취득 및 마스터배치 기록 갱신을 통해 대응을 추진하고 있으나, 이 과정은 시약 판매를 촉진하는 한편, 적합성 평가가 완료될 때까지 신규 설비 조달이 지연되는 요인이 되고 있습니다. 북유럽 국가들의 순환 경제 원칙에 대한 집중은 에너지 효율이 뛰어난 초음파 장비의 도입을 뒷받침하고 있습니다.
남미, 중동 및 아프리카의 합산 점유율은 작지만, 분산형 진단 키트와 현지 백신 충전·마무리 공장에 대한 관심이 높아지고 있습니다. 브라질의 공공 백신 연구소는 저전단 바이러스 용해 기술에 자금을 배정하고 있는 반면, 걸프 지역의 자유무역지대에서는 바이오프로세스 장비 수입에 대한 세제 혜택 조치를 통해 CDMO 기업을 유치하고 있습니다. 그러나 인프라 제약으로 인해 고비용의 마이크로플루이딕스 장비는 단기적으로 도입이 제한되고 있으며, 수요는 유연한 자금 조달이 가능하고 실적이 입증된 기계식 시스템에 집중되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the cell lysis market size is expected to grow from USD 4.02 billion in 2025 to USD 4.36 billion in 2026 and is forecast to reach USD 6.54 billion by 2031 at 8.44% CAGR over 2026-2031.
This report is Segmented by Product Type (Instruments [Homogenizers, and More], and Reagents), Cell Type (Mammalian Cells, Microbial Cells, and More), Lysis Technique (Mechanical, Enzymatic, and More), Application (Protein Purification & Proteomics, and More), End User (Biotechnology & Biopharma Firms, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cell Lysis Market Trends and Insights
Surge in Single-Cell Omics Sample-Prep Demand
Rapid growth in single-cell sequencing and proteomics has recalibrated lysis requirements toward extreme gentleness and contamination control. Advanced droplet and microwell platforms now process thousands of cells in parallel, demanding reagent formulations that preserve RNA and protein integrity for downstream barcoding. Vendors have responded with enzyme buffers tuned for sub-microliter reaction volumes and microfluidic hardware that shortens library-prep cycles to under 10 hours. Clinical labs now leverage these kits for minimal-invasive tumor profiling, expanding the addressable cell lysis market. Continuous feedback between reagent chemistry and consumable design accelerates protocol standardization, driving multi-site reproducibility and regulatory confidence.
Expanding Biologics & Biosimilars Pipeline
Patent expiries on blockbuster antibodies have triggered a manufacturing build-out that raises demand for large-volume, scalable lysis hardware capable of processing high-cell-density mammalian cultures. Asia-Pacific facilities contribute more than 4.7 million L of stainless and single-use capacity, reinforcing regional pull for robust homogenizers and microfluidizers. Regulatory pathways for biosimilars require validated, consistent release of intracellular product, incentivizing producers to adopt closed, automated lysis skids that integrate real-time monitoring. As continuous perfusion achieves titers above 1 g/L/day, gentle lysis becomes essential for maintaining glycosylation patterns and minimizing aggregation. Reagent suppliers benefit from multi-lot qualification programs that lock in long-term purchasing.
Stringent Bioprocess Validation & QA/QC Protocols
Increased FDA emphasis on real-time release tests forces manufacturers to prove lysis consistency across scales and environmental variables, lengthening development timelines and raising cost of goods. Advanced therapy developers must document viral integrity, impurity clearance, and residual-detergent profiles, often requiring multi-year comparability studies. Smaller firms without dedicated quality teams face steep barriers, reinforcing buyer preference for platforms with extensive validation dossiers and historical performance data.
Other drivers and restraints analyzed in the detailed report include:
- Uptake of High-Throughput Automated Workflows
- Growing Funding for Cell-Based Vaccines
- High Capital Cost of Microfluidic Lysis Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reagents produced 52.07% of 2025 revenue as routine workflows rely on consumables for every batch, yet instruments are set to outpace with a 12.03% CAGR through 2031, underscoring their strategic importance to automated bioprocessing. Demand for smart homogenizers and bead-mill lysers is climbing as sponsors move toward 24/7 continuous operations that require minimal operator intervention. Ultrasonic disruptors now include embedded sensors that track cavitation intensity, ensuring protein integrity during high-throughput runs.
Instrument growth is also propelled by microfluidizers designed for gentle disruption of viral particles and engineered cells. Suppliers offering single-use flow-paths mitigate cross-contamination risks and streamline cleaning validation, creating long-term recurring revenue from cartridge sales. On the reagent side, enzyme cocktails tailored for plant or algal cells are gaining traction, while eco-friendly detergent replacements address Triton X-100 restrictions. Complete lysis kits integrate buffers, inhibitors, and protocols, enabling small labs to meet regulatory expectations without in-house method development.
Mammalian cells maintained 45.13% of 2025 demand, reflecting their centrality in monoclonal antibody and recombinant protein production. The cell lysis market size for mammalian cultures is projected to expand steadily as intensified perfusion bioreactors raise cell densities that require robust yet gentle disruption. Viral particles, however, represent the fastest-growing opportunity at a 16.62% CAGR, fueled by adeno-associated virus (AAV) and lentiviral vector programs in gene and cell therapy.
Viral-specific lysis protocols combine enzymatic digestion and low-shear microfluidics to preserve capsid integrity, a prerequisite for high infectious titers downstream. Microbial cells continue to supply enzymes and industrial metabolites, sustaining solid demand for bead-beating and high-pressure homogenization. Plant cells, driven by molecular-farming initiatives, open niche avenues for proprietary enzymes that break robust cell walls while maintaining glycoprotein quality.
Complete Report Scope:
- By Product Type
- Instruments
- Homogenizers
- Bead-mill Lyser
- Ultrasonic Disruptors
- Microfluidizers
- Centrifuges
- Reagents
- Detergent Kits
- Enzymes & Nucleases
- Chemical Buffers
- Complete Lysis Kits
- Instruments
- By Cell Type
- Mammalian Cells
- Microbial Cells
- Plant Cells
- Viral Particles
- Others
- By Lysis Technique
- Mechanical (Physical)
- Chemical / Detergent
- Enzymatic
- Osmotic Shock
- By Application
- Protein Purification & Proteomics
- Nucleic-Acid Extraction & Genomics
- Cell-Based Vaccines
- Drug Discovery & Screening
- Diagnostics
- By End User
- Biotechnology & Biopharma Firms
- Contract Research & Manufacturing Organizations (CRO/CMO)
- Academic & Research Labs
- Clinical Diagnostics Centers
- Others
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 38.52% revenue in 2025, supported by a deep biopharmaceutical manufacturing base, significant NIH and BARDA funding, and an FDA framework that rewards validated automation. Large multi-site manufacturers deploy enterprise-wide specifications that harmonize lysis protocols across drug-substance and drug-product facilities. The United States continues to lead new-drug approvals in advanced therapies, reinforcing domestic demand for GMP-grade kits.
Asia-Pacific is forecast to achieve an 11.35% CAGR, driven by aggressive government incentives and rising CDMO activity. China's USD 4.17 billion biomanufacturing commitment for 2025 anchors multiple industrial parks that specify closed, automated lysis modules for monoclonal and gene-therapy programs. India expands as an alternative supply-chain hub, benefiting from policy alignment with the US BioSecure Act and large domestic talent pools. Regional producers target export-grade quality, elevating demand for systems with comprehensive validation packages.
Europe remains a pivotal market where stringent environmental policies shape purchasing decisions. The ban on Triton X-100 forces rapid transition to biodegradable detergents, placing early-mover suppliers at an advantage. Manufacturers adapt by certifying alternative surfactants and updating master batch records, a process that drives reagent sales but slows new-equipment procurement until qualification completes. Northern Europe's focus on circular economy principles encourages adoption of energy-efficient ultrasonic devices.
South America and the Middle East & Africa collectively represent smaller shares but register rising interest in decentralized diagnostic kits and local vaccine fill-finish plants. Brazil's public vaccine institutes allocate capital toward low-shear viral-lysis technology, while Gulf region free zones court CDMOs with tax incentives covering bioprocess equipment importation. Infrastructure constraints, however, temper near-term uptake of high-cost microfluidic instruments, aligning demand toward proven mechanical systems with flexible financing.
- Thermo Fisher Scientific
- Danaher
- Merck
- Beckton Dickinson
- Bio-Rad Laboratories
- Eppendorf
- Roche
- Takara Bio
- QIAGEN
- Miltenyi Biotec
- Qsonica
- Claremont BioSolutions
- Microfluidics International Corp.
- Labfreez Instruments Group Co.
- Cell Signaling Technology
- PerkinElmer (Revvity)
- Agilent Technologies
- Promega
- New England Biolabs
- Sigma-Aldrich (SAFC)
- Illumina
- Sartorius
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge In Single-Cell Omics Sample-Prep Demand
- 4.2.2 Expanding Biologics & Biosimilars Pipeline
- 4.2.3 Uptake Of High-Throughput Automated Workflows
- 4.2.4 Growing Funding For Cell-Based Vaccines
- 4.2.5 Adoption Of Plant Molecular Farming Platforms
- 4.2.6 CRISPR-Based Synthetic Biology Toolkits Requiring Gentle Lysis
- 4.3 Market Restraints
- 4.3.1 Stringent Bioprocess Validation & QA/QC Protocols
- 4.3.2 High Capital Cost Of Microfluidic Lysis Systems
- 4.3.3 Cytotoxic Detergent Disposal & ESG Pressures
- 4.3.4 Scale-Up Inefficiencies For Mammalian-Cell Intensification
- 4.4 Porter's Five Forces
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Instruments
- 5.1.1.1 Homogenizers
- 5.1.1.2 Bead-mill Lyser
- 5.1.1.3 Ultrasonic Disruptors
- 5.1.1.4 Microfluidizers
- 5.1.1.5 Centrifuges
- 5.1.2 Reagents
- 5.1.2.1 Detergent Kits
- 5.1.2.2 Enzymes & Nucleases
- 5.1.2.3 Chemical Buffers
- 5.1.2.4 Complete Lysis Kits
- 5.1.1 Instruments
- 5.2 By Cell Type
- 5.2.1 Mammalian Cells
- 5.2.2 Microbial Cells
- 5.2.3 Plant Cells
- 5.2.4 Viral Particles
- 5.2.5 Others
- 5.3 By Lysis Technique
- 5.3.1 Mechanical (Physical)
- 5.3.2 Chemical / Detergent
- 5.3.3 Enzymatic
- 5.3.4 Osmotic Shock
- 5.4 By Application
- 5.4.1 Protein Purification & Proteomics
- 5.4.2 Nucleic-Acid Extraction & Genomics
- 5.4.3 Cell-Based Vaccines
- 5.4.4 Drug Discovery & Screening
- 5.4.5 Diagnostics
- 5.5 By End User
- 5.5.1 Biotechnology & Biopharma Firms
- 5.5.2 Contract Research & Manufacturing Organizations (CRO/CMO)
- 5.5.3 Academic & Research Labs
- 5.5.4 Clinical Diagnostics Centers
- 5.5.5 Others
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Thermo Fisher Scientific Inc.
- 6.3.2 Danaher Corporation
- 6.3.3 Merck KGaA
- 6.3.4 Becton, Dickinson & Company
- 6.3.5 Bio-Rad Laboratories Inc.
- 6.3.6 Eppendorf AG
- 6.3.7 F. Hoffmann-La Roche Ltd
- 6.3.8 Takara Bio Inc.
- 6.3.9 QIAGEN NV
- 6.3.10 Miltenyi Biotec
- 6.3.11 Qsonica LLC
- 6.3.12 Claremont BioSolutions LLC
- 6.3.13 Microfluidics International Corp.
- 6.3.14 Labfreez Instruments Group Co.
- 6.3.15 Cell Signaling Technology Inc.
- 6.3.16 PerkinElmer (Revvity)
- 6.3.17 Agilent Technologies Inc.
- 6.3.18 Promega Corporation
- 6.3.19 New England Biolabs
- 6.3.20 Sigma-Aldrich (SAFC)
- 6.3.21 Illumina Inc.
- 6.3.22 Sartorius AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


