|
시장보고서
상품코드
2122596
세포 신호전달 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cell Signaling - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 세포 신호전달 시장 규모는 2025년에 62억 9,000만 달러로 평가되었습니다. 2026년 67억 5,000만 달러에서 2031년까지 95억 7,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 7.25%를 나타낼 전망입니다.

본 보고서는 신호전달 유형(내분비 신호전달 등), 제품(장비 및 소모품), 기술(유세포분석법, 질량분석법 등), 신호전달 경로(AKT/PI3K 신호전달 등), 용도(신약 개발 등),최종 사용자(제약·바이오기술 기업 등), 지역(북미 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 세포 신호전달 시장 동향 및 인사이트
만성 질환 및 자가면역 질환 유병률 증가
만성 질환 및 자가면역 질환의 유병률 증가에 따라, 체외에서의 장기간 제조 공정이 필요 없이 생체 내에서 CAR-T 세포를 생성하는 모듈식 지질 나노입자 플랫폼으로 자금이 이동하고 있습니다. 중간엽 줄기세포(MSC) 이식은 류마티스 관절염 및 전신성 경피증에서 지속적으로 높은 관해율을 보이고 있으며, 보험사의 수용 범위도 더욱 확대되고 있습니다. 고소득 국가에서 고령화가 진행되는 가운데, 관절 퇴행 및 대사증후군을 대상으로 한 재생의학 임상시험을 통해, 정교한 신호 전달 경로 분석 및 면역 기능 평가에 대한 수요가 더욱 가속화되고 있습니다.
세포 기반 생명과학 연구에 대한 자금 확대
서모피셔 사이언티픽(Thermo Fisher Scientific)은 4년간 20억 달러(이 중 5억 달러를 연구개발에 배정)를 투자하여, 영향력 있는 분석 시스템의 미국 내 생산 기반을 확립하고자 하고 있습니다. 이는 경쟁사들의 유사한 제조 활동의 국내 복귀(온쇼어링) 움직임을 반영한 것입니다. 이와 병행하여 오리온리스 바이오사이언스(Orionis Biosciences)는 분자 접착제 프로그램에 대해 제넨테크(Genentech)로부터 1억 500만 달러의 초기 자금을 확보함으로써, 차세대 치료법 플랫폼에 대한 벤처 기업의 강한 관심을 입증하고 있습니다. 아시아태평양 전체에서는 정부계 펀드가 세포 치료 공정 개발 거점에 자본을 투입하기 시작하면서, 현지 바이오의약품 제조업체들의 기술 이전 리드타임을 단축시키고 있습니다.
고급 세포 신호 전달 시스템에는 막대한 설비 투자가 필요
턴키 방식의 분광식 세포 계수 장치는 대당 75만 달러를 초과하여 학술 연구 보조금 주기를 압박하고, 저소득 지역의 장비 교체를 지연시키고 있습니다. 치료용 단일클론 항체 생산에는 단일 적응증당 여전히 연간 1만 5,000-14만 달러의 비용이 소요되어, 이로 인해 다운스트림 공정의 소모품 예산이 부풀어 오르고 있습니다. 수탁 제조 기업(CMO)은 가동률이 50% 미만이라고 보고하고 있으며, 이러한 수급 불일치는 플랫폼 소유주에게 비용 회수 문제를 더욱 심각하게 만들고 있습니다.
부문별 분석
2025년, 내분비 신호 전달은 세포 신호 전달 시장의 34.41%를 차지했으며, 장기 수준에서 호르몬 수용체 분석이 필요한 대사 및 생식 관련 연구를 뒷받침하고 있습니다. 자율 신호 전달은 종양 증식을 제어하는 자가 자극 루프를 규명하는 종양학 프로그램이 증가함에 따라 연평균 성장률(CAGR) 8.88%라는 가장 높은 성장률을 보일 것으로 전망됩니다. 파라크린 신호 전달은 조직 복구 모델에서 여전히 중요성을 유지하고 있는 반면, 시냅스 메커니즘은 신경과학 분야에 대한 투자 증가의 혜택을 받고 있습니다.
자가신호 피드백에 관한 메커니즘의 규명이 진전됨에 따라, 경로 선택적 억제제 및 동반 진단제 개발이 촉진되고 있습니다. 파라클린에 관한 연구 결과는 림프절의 케모카인 농도 구배를 향해 이동하도록 프로그래밍된 나노 입자 운반체의 개발로 이어졌으며, 이 접근법은 현재 유방암에 대한 중기 임상시험이 진행 중입니다. 이러한 진전이 결합되어, 세포 신호 전달 시장은 신호 전달 경로의 생물학을 정밀 의학에 적용하는 데 계속해서 주력하고 있습니다.
2025년 매출 중 장비가 55.10%를 차지했으며, 이는 실험실의 핵심 인프라를 구성하는 분석용 워크스테이션의 고가 가격을 반영한 것입니다. 반면, 소모품은 분석량에 비례하여 시약의 정기적인 주문이 증가함에 따라 연평균 성장률(CAGR) 9.15%로 장비 부문보다 높은 성장세를 보일 것으로 예측됩니다. 특히 분산형 CRO 시설에서는 유세포분석용 스키드, 고해상도 이미징 칩, 마이크로플루이딕스 카트리지가 장비 교체 주기를 주도하고 있습니다.
또한, 재조합 항체가 기존의 다클론성 시약보다 특이성이 뛰어나기 때문에 소모품 수요도 증가하고 있습니다. 이로 인해, 이전에는 미국 연구소에 연간 최대 18억 달러의 비용을 발생시켰던 재현성 문제가 감소하고 있습니다. 항체 검증 데이터 세트를 제공하는 공급업체들은 고객 유지율을 높이고, 이익률 향상을 도모하고 있습니다.
지역별 분석
북미는 2025년에 전 세계 매출의 42.02%를 차지했습니다. 이는 NIH(미국 국립보건원)의 안정적인 연구비 지원, 벤처 캐피탈의 풍부한 자금력, 그리고 재생의학 후보 약물의 규제 심사 기간을 단축하는 FDA(미국 식품의약국)의 지침에 힘입은 결과입니다. 서모피셔(Thermo Fisher)사의 국내 총 20억 달러 규모의 다년간 설비 확충은 고처리량 기기에 대한 수요가 지속될 것이라는 공급업체들의 확신을 뒷받침하고 있습니다. 특정 미승인 줄기세포 치료를 허용하는 주 차원의 법률로 인해 규정 준수 측면에서 불일치가 발생하고 있으며, 대형 후원사는 이에 대응해야 합니다.
아시아태평양은 각국 정부가 바이오프로세스에 대한 세제 혜택을 확대하고 희귀질환 치료제의 신속 승인 절차를 도입함에 따라 2031년까지 연평균 성장률(CAGR) 8.12%로 성장을 주도하고 있습니다. 중국만 해도 1억 2,000만 개의 세포를 아우르는 단일 세포 오믹스 아틀라스를 구축하여, AI 훈련용 데이터 세트에 대해 타의 추종을 불허하는 상세한 주석을 제공합니다. 일본의 의약품 및 의료기기 종합기구(PMDA)는 미국의 ‘브레이크스루 지정’ 기준에 발맞추기 위해 ‘사키가케’ 제도의 지속적인 재검토를 추진하고 있습니다.
유럽은 큰 점유율을 차지하고 있지만, 속도 면에서는 뒤처지고 있습니다. 엄격한 세포 치료 관련 지침으로 인해 임상시험을 시작하는 데 시간이 걸리는 반면, 공급망의 투명성은 높아지고 있습니다. 이 지역의 활성 성분(API) 시장은 연평균 5.78%의 성장률을 보이고 있으며, 현재 합성 API가 가장 큰 점유율을 차지하고 있고, 생명공학 유래 API가 가장 빠르게 성장하고 있습니다. 병원들이 동반 진단을 표준 치료 과정에 통합함에 따라, 종양학은 여전히 유럽에서 가장 활발한 적응증 분야입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the cell signaling market size was valued at USD 6.29 billion in 2025 and estimated to grow from USD 6.75 billion in 2026 to reach USD 9.57 billion by 2031, at a CAGR of 7.25% during the forecast period (2026-2031).
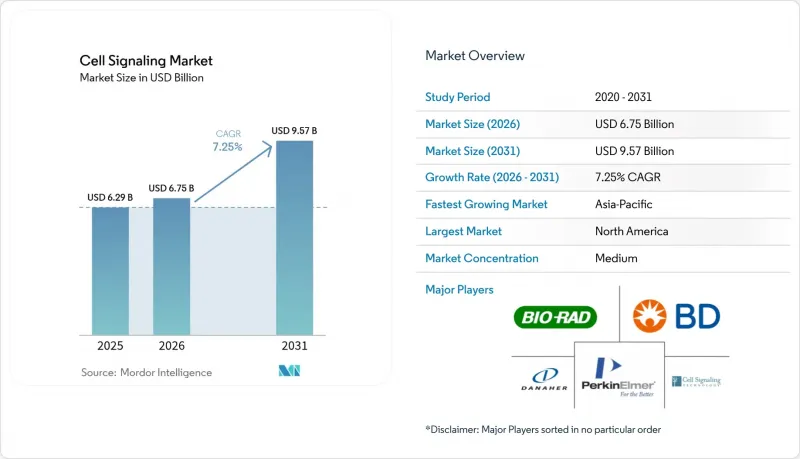
This report is Segmented by Signaling Type (Endocrine Signaling, and More), Product (Instruments and Consumables), Technology (Flow Cytometry, Mass Spectrometry, and More), Pathway (AKT/PI3K Signaling, and More), Application (Drug Discovery & Development, and More), End User (Pharma & Biotech Companies, and More), Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cell Signaling Market Trends and Insights
Growing Prevalence of Chronic and Autoimmune Diseases
The rising incidence of chronic and autoimmune disorders is redirecting capital toward modular lipid-nanoparticle platforms that generate CAR-T cells in vivo, eliminating lengthy ex-vivo manufacturing. Mesenchymal stromal cell (MSC) transplantation continues to produce compelling remission rates across rheumatoid arthritis and systemic sclerosis, fueling wider payer acceptance. As aging populations swell in high-income economies, regenerative medicine trials targeting joint degeneration and metabolic syndrome further accelerate demand for advanced pathway analyses and functional-immune readouts.
Expanding Funding for Cell-Based Life-Science Research
Thermo Fisher Scientific is investing USD 2 billion over four years-USD 500 million earmarked for R&D-to anchor U.S. production of high-impact analytical systems, a move mirroring similar manufacturing onshoring initiatives by rivals. In parallel, Orionis Biosciences secured USD 105 million upfront from Genentech for molecular-glue programs, underscoring venture appetite for next-generation modality platforms. Across Asia-Pacific, sovereign wealth funds have started funneling capital into cell-therapy process-development hubs, compressing technology-transfer timelines for local biologics manufacturers.
High Capital Investment Required for Advanced Cell-Signaling Systems
Turn-key spectral cytometers exceed USD 750,000 per unit, stretching academic grant cycles and delaying upgrades in lower-income regions. Therapeutic-grade monoclonal antibody production still costs between USD 15,000 and USD 140,000 annually for a single indication, which inflates downstream consumable budgets. Contract manufacturing organizations report sub-50% utilization rates, revealing a supply-demand mismatch that exacerbates cost-recovery challenges for platform owners.
Other drivers and restraints analyzed in the detailed report include:
- Continuous Technological Innovations in Cell-Analysis Platforms
- Increasing Adoption of Artificial Intelligence in Assay Design
- Ethical and Regulatory Concerns Surrounding Stem-Cell Research
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Endocrine signaling held 34.41% of the cell signaling market in 2025, underpinning metabolic and reproductive studies that require hormone-receptor assays at organ scale. Autocrine signaling is on track for the fastest 8.88% CAGR because oncology programs increasingly dissect self-stimulating loops that govern tumor proliferation. Paracrine signaling retains relevance for tissue-repair models, while synaptic mechanisms benefit from higher neuroscience funding.
Growing mechanistic clarity around autocrine feedback has spurred design of pathway-selective inhibitors and companion diagnostics. Paracrine insights have inspired nanoparticle carriers programmed to home lymph-node chemokine gradients, an approach now in mid-phase breast-cancer trials. Together, these advances keep the cell signaling market firmly focused on translating pathway biology into precision therapeutics.
Instruments accounted for 55.10% of 2025 revenue, reflecting the hefty ticket price of analytical workstations that constitute the core lab infrastructure. Consumables, however, are poised to outpace with a 9.15% CAGR as recurring reagent orders scale with assay volume. Flow-cytometry skids, high-resolution imaging chips and microfluidic cartridges dominate replacement cycles, especially in decentralized CRO facilities.
Consumables demand also rises because recombinant antibodies outperform conventional polyclonal reagents on specificity, trimming reproducibility failures that previously cost U.S. labs up to USD 1.8 billion annually. Suppliers offering antibody-validation data sets gain customer stickiness and incremental margins.
Complete Report Scope:
- By Signaling Type
- Endocrine Signaling
- Paracrine Signaling
- Autocrine Signaling
- Synaptic Signaling
- Juxtacrine / Gap-Junction Signaling
- By Product
- Instruments
- Flow Cytometers
- Mass Spectrometers
- Western-Blot Imaging Systems
- ELISA Readers
- Other Instruments
- Consumables
- Reagents & Kits
- Antibodies
- Media & Sera
- Other Consumables
- Instruments
- By Technology
- Flow Cytometry
- Mass Spectrometry
- Western Blotting
- ELISA
- Other Technologies
- By Pathway
- AKT / PI3K Signaling
- AMPK Signaling
- ErbB / HER Signaling
- Other Pathways
- By Application
- Drug Discovery & Development
- Cancer & Stem-Cell Research
- Immunology Research
- Diagnostics
- Other Applications
- By End User
- Pharma & Biotech Companies
- Academic & Research Institutes
- Contract Research Organizations
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- GCC
- North America
Geography Analysis
North America generated 42.02% of global revenue in 2025, underpinned by NIH grant stability, venture capital depth and FDA guidance that shortens regulatory review for regenerative candidates. Thermo Fisher's multi-year USD 2 billion domestic build-out underscores supplier confidence in continued demand for high-throughput instrumentation. State-level legislation permitting certain unapproved stem-cell interventions introduces compliance fragmentation that large sponsors must now navigate.
Asia-Pacific leads growth at a 8.12% CAGR through 2031 as governments expand bioprocess tax incentives and roll out accelerated approval pathways for rare-disease therapies. China alone has compiled single-cell-omics atlases covering 120 million cells, offering unparalleled annotation depth for AI-training datasets. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) continues to refine its Sakigake fast-track to keep pace with U.S. breakthrough designation metrics.
Europe holds material share yet lags on speed: stringent cell-therapy directives extend trial-setup timelines, though they bolster supply-chain transparency. The region's active-pharmaceutical-ingredient (API) market is climbing 5.78% annually, with synthetic APIs largest today and biotech APIs growing fastest. Oncology remains Europe's most dynamic indication as hospitals integrate companion diagnostics into standard-of-care pathways.
- Beckton Dickinson
- Bio-Rad Laboratories
- Bio-Techne
- Cell Signaling Technology
- Danaher Corporation (Beckman Coulter, Molecular Devices, Cytiva)
- Merck KGaA (MilliporeSigma)
- Thermo Fisher Scientific
- PerkinElmer
- QIAGEN
- Promega
- Agilent Technologies
- Miltenyi Biotec
- Abcam
- Lonza Group
- Enzo Life Sciences
- Creative Diagnostics
- Tocris Bioscience
- GE Healthcare Life Sciences
- BioLegend Inc.
- Oxford Instruments (Andor)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Prevalence of Chronic And Autoimmune Diseases
- 4.2.2 Expanding Funding For Cell-Based Life Science Research
- 4.2.3 Continuous Technological Innovations In Cell Analysis Platforms
- 4.2.4 Increasing Adoption of Artificial Intelligence In Bioassay Design
- 4.2.5 Emergence of Three-Dimensional Microfluidic Cell Culture Models
- 4.2.6 Rapid Scale-Up of Cell Therapy Manufacturing Workflows
- 4.3 Market Restraints
- 4.3.1 High Capital Investment Required For Advanced Cell Signaling Systems
- 4.3.2 Ethical And Regulatory Concerns Surrounding Stem Cell Research
- 4.3.3 Inconsistent Quality of Critical Reagents And Antibodies
- 4.3.4 Big-Data Management Challenges In Single-Cell Omics Workflows
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat Of New Entrants
- 4.5.2 Bargaining Power Of Buyers
- 4.5.3 Bargaining Power Of Suppliers
- 4.5.4 Threat Of Substitutes
- 4.5.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD million)
- 5.1 By Signaling Type
- 5.1.1 Endocrine Signaling
- 5.1.2 Paracrine Signaling
- 5.1.3 Autocrine Signaling
- 5.1.4 Synaptic Signaling
- 5.1.5 Juxtacrine / Gap-Junction Signaling
- 5.2 By Product
- 5.2.1 Instruments
- 5.2.1.1 Flow Cytometers
- 5.2.1.2 Mass Spectrometers
- 5.2.1.3 Western-Blot Imaging Systems
- 5.2.1.4 ELISA Readers
- 5.2.1.5 Other Instruments
- 5.2.2 Consumables
- 5.2.2.1 Reagents & Kits
- 5.2.2.2 Antibodies
- 5.2.2.3 Media & Sera
- 5.2.2.4 Other Consumables
- 5.2.1 Instruments
- 5.3 By Technology
- 5.3.1 Flow Cytometry
- 5.3.2 Mass Spectrometry
- 5.3.3 Western Blotting
- 5.3.4 ELISA
- 5.3.5 Other Technologies
- 5.4 By Pathway
- 5.4.1 AKT / PI3K Signaling
- 5.4.2 AMPK Signaling
- 5.4.3 ErbB / HER Signaling
- 5.4.4 Other Pathways
- 5.5 By Application
- 5.5.1 Drug Discovery & Development
- 5.5.2 Cancer & Stem-Cell Research
- 5.5.3 Immunology Research
- 5.5.4 Diagnostics
- 5.5.5 Other Applications
- 5.6 By End User
- 5.6.1 Pharma & Biotech Companies
- 5.6.2 Academic & Research Institutes
- 5.6.3 Contract Research Organizations
- 5.6.4 Other End Users
- 5.7 Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East & Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East & Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.5.3.1 GCC
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Becton, Dickinson And Company
- 6.3.2 Bio-Rad Laboratories Inc.
- 6.3.3 Bio-Techne Corporation
- 6.3.4 Cell Signaling Technology Inc.
- 6.3.5 Danaher Corporation (Beckman Coulter, Molecular Devices, Cytiva)
- 6.3.6 Merck KGaA (MilliporeSigma)
- 6.3.7 Thermo Fisher Scientific Inc.
- 6.3.8 PerkinElmer Inc.
- 6.3.9 Qiagen NV
- 6.3.10 Promega Corporation
- 6.3.11 Agilent Technologies
- 6.3.12 Miltenyi Biotec
- 6.3.13 Abcam Plc
- 6.3.14 Lonza Group AG
- 6.3.15 Enzo Life Sciences
- 6.3.16 Creative Diagnostics
- 6.3.17 Tocris Bioscience
- 6.3.18 GE Healthcare Life Sciences
- 6.3.19 BioLegend Inc.
- 6.3.20 Oxford Instruments (Andor)
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment