|
시장보고서
상품코드
2122600
수의용 통증 관리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Veterinary Pain Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 수의용 통증 관리 시장 규모는 2025년에 17억 5,000만 달러로 평가되었습니다. 2026년 18억 5,000만 달러에서 2031년까지 24억 6,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.84%를 나타낼 전망입니다.

본 보고서는 제품 유형별(NSAIDs, 오피오이드, 국소 마취제 등을 포함한 의약품, 레이저 치료, 전자기 치료 등을 포함한 의료기기), 동물 유형별(반려동물, 가축),최종 사용자별(동물병원 및 진료소, 재택 간호 환경 등), 지역별(북미, 유럽 등)로 세분화되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 수의용 통증 관리 시장 동향 및 인사이트
반려동물 사육 마릿수 증가와 ‘인간화’
반려동물 주인들은 인간과 동등한 수준의 임상 기준을 점점 더 기대하게 되었으며, 조에티스(Zoetis)사의 베딘베탐(bedinvetmab) 주사제와 같은 혁신적인 제품에 대한 프리미엄 채택이 촉진되고 있습니다. 미국 동물병원협회(AAHA)의 2024년 지침에서는 다중 모드 요법이 규정되어 있으며, NSAIDs와 함께 항체 사용이 정당화되고 있습니다. 마찬가지로, 복지 인증을 받은 가축 제품 소매업체들도 가격 프리미엄을 정당화하기 위해 신뢰할 수 있는 진통 효과에 대한 주장을 요구하고 있어 전반적인 수요를 확대시키고 있습니다.
퇴행성 관절염 및 수술 후 통증 발생률 증가
퇴행성 관절염은 1세 이상의 개 20%, 12세 이상의 고양이 90% 가까이에게 영향을 미치고 있습니다. 베딘베토마브의 FDA 승인으로 생물학적 제제가 효과적인 장기적 해결책으로 자리 잡았으며, 임상시험에서의 유효율은 43.5%(위약군은 16.9%)였습니다. 엘란코(Elanco)사의 ‘노시타(Nosita)’와 같은 지속성 부피바카인 제제는 72시간 동안 효과를 유지하여 재입원율과 반려인의 부담을 줄여줍니다. 치료를 받지 않은 가축의 생산성 저하는 효과적인 진통의 경제적 중요성을 더욱 강조하고 있습니다.
NSAID 및 오피오이드의 이상반응 프로파일
수의사는 NSAID를 처방할 때 신장, 간 및 소화기 계통의 위험을 고려하며, 오피오이드 조제 시에는 용도 변경에 대한 우려가 문제를 더욱 복잡하게 만듭니다. 베딘베트맙의 시판 후 조사에서는 1,800만 회 투여에 대해 1만 7,162건의 이상반응 보고가 기록되어, 혁신적인 생물학적 제제라 할지라도 안전성에 대한 책임이 수반된다는 점을 임상의들에게 재인식시키고 있습니다. FDA가 수제트리긴의 인간용 사용을 승인한 것은 수의학 분야로도 파급될 가능성이 있는 비오피오이드 계열 약물로 전환하는 추세가 가속화되고 있음을 보여줍니다.
부문별 분석
2025년, 수의학용 통증 관리 시장 규모의 81.05%를 의약품 부문이 차지했으며, 멜록시캄 등의 NSAIDs가 핵심을 이루고 있지만, 의료기기의 매출액은 연평균 성장률(CAGR) 6.03%로 증가하고 있습니다. NSAIDs는 비용 대비 효과가 높아 1차 치료법으로서의 지위를 유지하고 있는 반면, 오피오이드 사용은 불법 전용에 대한 감시가 강화되면서 감소 추세를 보이고 있습니다. 노시타(Nocita)와 같은 장시간 작용형 국소 마취제는 진통 효과를 72시간까지 연장하여 재입원을 줄여줍니다. 알파-2 작용제는 대형 동물의 진정 분야에서 틈새 시장 역할을 유지하고 있습니다. 칸나비노이드 계열 제품의 초기 진출기업들은 규제상의 역풍이 있음에도 불구하고, 기존 약물로 개선하기 어려운 만성 통증 치료에 주력하고 있습니다.
휴대용 다이오드 레이저 장치, PEMF 매트, 충격파 치료 시스템은 단독 또는 보조적인 솔루션으로서 시장에서 입지를 다지고 있습니다. 동물병원에서는 NSAID를 잘 견디지 못하는 고령 반려동물에게 이러한 기술을 권장하고 있는 반면, 말 진료에 종사하는 수의사들은 근골격계 회복을 위해 PEMF를 활용하고 있습니다. 각 제조업체는 현재 시술 매개변수를 기록하는 소프트웨어 분석 기능을 제품에 탑재하고 있으며, 이를 통해 수의사는 다중 모드 치료 요건 준수 현황을 문서화할 수 있게 되었습니다. 이러한 기기 동향은 수의용 통증 관리 시장에서 약물 요법과 비약물 요법의 균형이 앞으로 점점 더 중요해질 것임을 시사합니다.
지역별 분석
북미는 2025년 세계 매출의 41.78%를 차지했습니다. 이는 반려동물 보험의 높은 보급률과 신속한 시장 출시 승인을 가능하게 하는 규제 환경에 힘입은 결과입니다. 단일클론항체 분야의 선구자들은 FDA의 심사 효율성을 활용하여 조기에 브랜드 인지도를 확보했습니다. 그러나 캐나다의 규제 약물에 대한 신중한 태도는 비오피오이드계 약물 및 칸나비노이드 연구 파이프라인에 대한 투자를 촉진하고 있습니다.
유럽은 이에 근소한 차이로 뒤를 이었으며, 세계에서 가장 엄격한 동물 복지법에 의해 형성되어 있습니다. 다각적 진통법의 의무화로 인해 다양한 제품 키트에 대한 수요가 증가함에 따라, 공급업체들은 더 폭넓은 제품 라인업을 갖추도록 압박받고 있습니다. 항균제 적정 사용 프로그램으로 인해 NSAID의 투여 기간이 제한되면서, 간접적으로 레이저 및 전자기 치료 기기의 보급이 촉진되고 있습니다. 영국의 브렉시트 이후 규제상의 자율성으로 인해 틈새 제품용 신속 승인 경로가 확보되었으며, 중소기업은 EU 전역에서의 승인을 앞당겨 시장에 진입할 기회를 얻고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 7.18%로 예측되는 가장 빠르게 성장하는 지역입니다. 중국에서는 팬데믹 이후 생활 방식의 변화에 따라 도시 지역의 반려동물 사육률이 급증했습니다. 한편, 일본에서는 반려동물의 고령화가 유럽 및 미국 시장과 유사한 경향을 보이고 있습니다. 한국에서는 ‘동물보호법’ 개정에 따라 미용 성형 및 질병 치료 시 통증 완화가 의무화되면서 새로운 기초 수요가 창출되고 있습니다. 동남아시아의 신흥 경제국에서는 수출 인증 기준을 준수하기 위해 동물 복지 향상에 힘쓰고 있으며, 이러한 정책이 전 세계적으로 입지를 다진 브랜드가 접근하기 쉬운 시장 규모로 이어지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the veterinary pain management market size was valued at USD 1.75 billion in 2025 and estimated to grow from USD 1.85 billion in 2026 to reach USD 2.46 billion by 2031, at a CAGR of 5.84% during the forecast period (2026-2031).
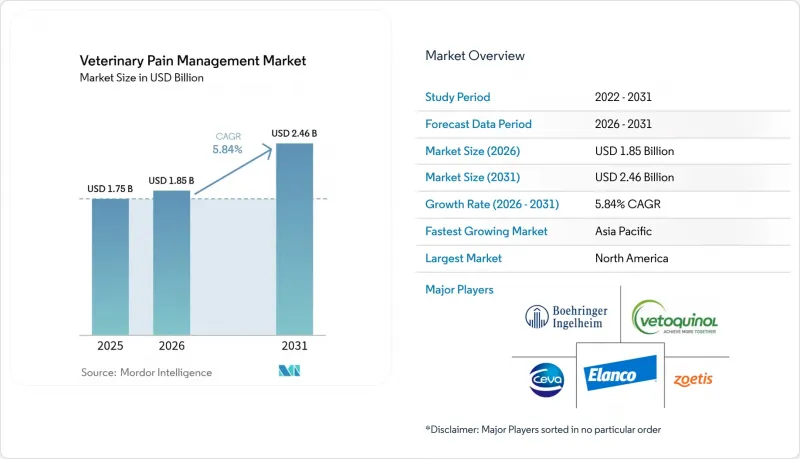
This report is Segmented by Product (Drugs Including NSAIDs, Opioids, Local Anesthetics, and More; Devices Including Laser Therapy, Electromagnetic Therapy), Animal Type (Companion Animals, Livestock), End User (Veterinary Hospitals & Clinics, Homecare Settings, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Veterinary Pain Management Market Trends and Insights
Rising Pet Ownership & Humanization
Pet owners increasingly expect human-level clinical standards, prompting premium adoption of innovations such as Zoetis' bedinvetmab injections. The American Animal Hospital Association's 2024 guidelines codify multimodal regimens, legitimizing antibody use alongside NSAIDs. Retailers of welfare-certified livestock products likewise seek credible analgesia claims to justify price premiums, widening overall demand.
Growing Osteoarthritis & Post-Operative Pain Incidence
Osteoarthritis affects 20% of dogs older than one year and nearly 90% of cats above 12 years. FDA approval of bedinvetmab established biologics as viable long-term solutions, with trial success rates of 43.5% versus 16.9% for placebo. Long-acting bupivacaine formulations such as Elanco's Nocita deliver 72-hour coverage, curbing readmission rates and owner burden. Productivity losses in untreated livestock further amplify the economic argument for effective analgesia.
Adverse-Event Profile of NSAIDs & Opioids
Veterinarians weigh renal, hepatic, and gastrointestinal risks when prescribing NSAIDs, and diversion concerns complicate opioid dispensing. Post-marketing surveillance of bedinvetmab documented 17,162 adverse reports from 18 million doses, reminding clinicians that even innovative biologics carry safety obligations. FDA approval of suzetrigine for human use underscores momentum toward non-opioid classes that may cross into veterinary care.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Livestock Welfare Regulations
- Mandatory Multimodal Analgesia Protocols (EU, US)
- Stringent Regulatory Approval Timelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The pharmaceutical segment captured 81.05% of the veterinary pain management market size in 2025, anchored by NSAIDs such as meloxicam, yet device revenues are growing at a 6.03% CAGR. NSAIDs persist as first-line therapy because of cost efficiency, whereas opioid use retreats under diversion scrutiny. Long-acting local anesthetics like Nocita extend analgesia to 72 hours and mitigate readmission. Alpha-2 agonists retain niche roles in large animal sedation. Early cannabinoid entrants address chronic pain that resists conventional classes, despite regulatory headwinds.
Portable diode-laser units, PEMF mats, and shockwave systems are carving out space as stand-alone or adjunct solutions. Clinics promote these technologies for geriatric pets intolerant of NSAIDs, while equine practitioners leverage PEMF for musculoskeletal recovery. Manufacturers now bundle software analytics that log session parameters, enabling veterinarians to document compliance with multimodal mandates. The device trajectory signals that the veterinary pain management market will increasingly balance pharmacology with non-pharmacologic modalities.
Complete Report Scope:
- By Product (Value)
- Drugs
- NSAIDs
- Opioids
- Local Anesthetics
- Alpha-2 Agonists
- Cannabinoid-based Therapeutics
- Devices
- Laser Therapy
- Electromagnetic Therapy
- Drugs
- By Animal Type (Value)
- Companion Animals
- Livestock
- By End User (Value)
- Veterinary Hospitals & Clinics
- Homecare Settings
- Academic & Research Institutes
- By Region (Value)
- North America
- United States
- Canada
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America contributed 41.78% of global revenue in 2025, underpinned by high pet insurance penetration and a regulatory climate that enables rapid first-to-market approvals. Monoclonal antibody pioneers capitalized on FDA review efficiencies, securing early brand recognition. Canada's cautious stance on controlled substances has, however, catalyzed investment in non-opioid drugs and cannabinoid research pipelines.
Europe follows closely, shaped by some of the world's strictest welfare legislation. Mandatory multimodal analgesia elevates demand for diverse product kits, pushing suppliers to hold broader formularies. Antimicrobial stewardship programs restrain NSAID courses, indirectly prompting uptake of laser and electromagnetic therapy devices. The United Kingdom's post-Brexit regulatory autonomy is allowing accelerated pathways for niche products, giving smaller firms an entry door ahead of pan-EU approvals.
Asia-Pacific is the fastest-expanding region with a projected 7.18% CAGR. Urban pet ownership in China rose sharply after pandemic-era lifestyle shifts, while Japan's aging pet cohort parallels that of Western markets. South Korea's reform of its Animal Protection Act stipulates pain relief during cosmetic surgery and disease treatment, creating new baseline demand. Emerging Southeast Asian economies deploy welfare upgrades to align with export certification criteria, translating policy into accessible market volume for globally established brands.
- Zoetis
- Boehringer Ingelheim
- Elanco Animal Health Inc.
- Merck & Co., Inc. (Animal Health)
- Dechra Pharmaceuticals
- Ceva Sante Animale SAS
- Virbac S.A.
- Vetoquinol
- Norbrook Laboratories Ltd
- Chanelle Pharma Group
- Orion
- Parnell Pharmaceuticals Holdings Ltd
- Assisi Animal Health LLC
- LiteCure LLC (Companion Animal Health)
- PulseVet Technologies Inc.
- Zomedica Corp.
- PetVivo Holdings Inc.
- Ellevet Sciences LLC
- Animalcare Group plc
- Alivira Animal Health Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising pet ownership & humanization
- 4.2.2 Growing osteoarthritis & post-operative pain incidence
- 4.2.3 Expansion of livestock welfare regulations
- 4.2.4 Mandatory multimodal analgesia protocols (EU, US)
- 4.2.5 Commercialization of cannabinoid-based vet therapeutics
- 4.2.6 AI-powered pain-scoring tools boosting early treatment
- 4.3 Market Restraints
- 4.3.1 Adverse-event profile of NSAIDs & opioids
- 4.3.2 Stringent regulatory approval timelines
- 4.3.3 Shortage of veterinary anesthesiologists
- 4.3.4 AMR-linked scrutiny curbing NSAID usage
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product (Value)
- 5.1.1 Drugs
- 5.1.1.1 NSAIDs
- 5.1.1.2 Opioids
- 5.1.1.3 Local Anesthetics
- 5.1.1.4 Alpha-2 Agonists
- 5.1.1.5 Cannabinoid-based Therapeutics
- 5.1.2 Devices
- 5.1.2.1 Laser Therapy
- 5.1.2.2 Electromagnetic Therapy
- 5.1.1 Drugs
- 5.2 By Animal Type (Value)
- 5.2.1 Companion Animals
- 5.2.2 Livestock
- 5.3 By End User (Value)
- 5.3.1 Veterinary Hospitals & Clinics
- 5.3.2 Homecare Settings
- 5.3.3 Academic & Research Institutes
- 5.4 By Region (Value)
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Zoetis Inc.
- 6.3.2 Boehringer Ingelheim International GmbH
- 6.3.3 Elanco Animal Health Inc.
- 6.3.4 Merck & Co., Inc. (Animal Health)
- 6.3.5 Dechra Pharmaceuticals PLC
- 6.3.6 Ceva Sante Animale SAS
- 6.3.7 Virbac S.A.
- 6.3.8 Vetoquinol S.A.
- 6.3.9 Norbrook Laboratories Ltd
- 6.3.10 Chanelle Pharma Group
- 6.3.11 Orion Corporation
- 6.3.12 Parnell Pharmaceuticals Holdings Ltd
- 6.3.13 Assisi Animal Health LLC
- 6.3.14 LiteCure LLC (Companion Animal Health)
- 6.3.15 PulseVet Technologies Inc.
- 6.3.16 Zomedica Corp.
- 6.3.17 PetVivo Holdings Inc.
- 6.3.18 Ellevet Sciences LLC
- 6.3.19 Animalcare Group plc
- 6.3.20 Alivira Animal Health Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment