

|
시장보고서
상품코드
2122699
국소분절사구체경화증(FSGS) 치료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Focal Segmental Glomerulosclerosis (FSGS) Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
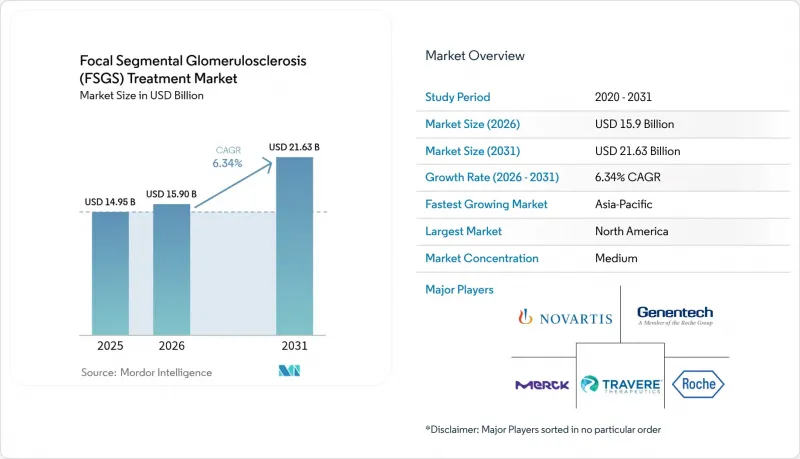
에 의하면, 국소분절사구체경화증(FSGS) 치료 시장 규모는 2025년 149억 5,000만 달러로 평가되었습니다. 2026년에는 159억 달러로 확대되어 2026-2031년에 걸쳐 CAGR 6.34%로 성장을 지속하여, 2031년까지 216억 3,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 질환 유형(원발성 FSGS, 이차성 FSGS), 질환 관리(진단, 치료), 최종 사용자(병원·이식 센터, 전문 클리닉·신장내과 클리닉, 기타), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 국소분절사구체경화증(FSGS) 치료 시장 동향 및 인사이트
대사성 질환과 관련된 FSGS 유병률 증가
당뇨병과 비만의 지속적인 증가는 대사 스트레스가 포도세포의 소실과 사구체 경화를 가속화하기 때문에 FSGS의 발생률을 직접적으로 높이고 있습니다. 이에 따라 제약 개발 기업들은 대사 신호와 신장 신호를 모두 조절하는 이중 경로 약물의 연구를 진행하고 있습니다. 고혈압 및 당뇨병 환자를 대상으로 한 조기 선별 검사의 실시로 진단 건수가 증가하고 있으며, 그 결과 FSGS 치료 시장의 잠재적 대상층이 확대되고 있습니다. 임상의들은 대사 관리 전략을 치료 경로에 통합하고 있어, 혈당 및 지질 관리와 포도세포 보호제를 결합한 병용 요법에 대한 장기적인 수요가 발생하고 있습니다.
탄탄한 치료 파이프라인 및 연구 개발 자금
Vertex의 이낙사프린, Travere의 스파센탄, 그리고 몇 가지 안티센스 제제는 FDA의 ‘획기적 치료제(Breakthrough Therapy)’ 또는 ‘희귀질환 치료제’ 지정을 획득하여 규제 승인까지의 기간이 단축되었습니다. 2024년에는 신장 분야 스타트업에 대한 벤처 자금이 45% 급증했으며, 이로 인해 중소 바이오기술 기업들이 보체 억제제, 사구세포 재생 바이오의약품, 유전자 침묵 분자의 연구 개발에 착수하도록 장려되고 있습니다. 파이프라인의 폭이 넓어짐에 따라 FSGS 치료 시장은 전략적 투자자들에게 점점 더 매력적인 대상이 되고 있으며, 거래 흐름이 가속화되면서 새로운 치료법이 상용화를 향해 나아가고 있습니다.
투석 및 이식의 높은 비용과 이용 제한
미국에서 투석에 대한 연간 지출은 환자 1인당 평균 8만 9,000달러이며, 신장 이식 비용은 약 44만 2,500달러에 달할 전망입니다. 이식 공급이 제한적이고 대기자 명단이 길기 때문에 그 부담은 더욱 커지고 있습니다. 이에 따라 보험사들은 신규 진입 제품 하나하나에 대해 비용 대비 효과를 엄격히 검토하고 있으며, 장기적인 결과 데이터가 없는 고가의 세포 치료나 유전자 치료에 대해서는 승인에 신중한 태도를 보이고 있습니다. 저·중소득 국가에서는 투석 능력의 제약으로 인해 심각한 치료 격차가 발생하고 있으며, 고가 의약품의 보급이 억제되고 있어 FSGS 치료 시장의 성장 잠재력 일부가 둔화되고 있습니다.
부문별 분석
2025년에는 원발성 FSGS가 FSGS 치료 시장의 60.42%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.67%를 나타낼 것으로 전망됩니다. 이러한 높은 점유율은 면역 조절제 및 면역 매개성 포도세포 손실을 억제하는 새로운 표적 치료에 대한 반응이 좋음을 반영합니다. APOL1 유전자형 검사는 일상적으로 시행되고 있으며, 고위험 대립 유전자를 가진 환자들은 이낙사프린과 같은 유전자형 특이적 억제제의 임상시험에 참여하고 있습니다. 따라서 원발성 FSGS 치료 시장 규모는 여전히 당뇨병, 고혈압 또는 약물 독성 관리에 치료의 중점을 두고 있는 이차성 FSGS를 상회할 것으로 예측됩니다.
유전자 검사를 통해 APOL1 상태에 따라 정의된 마이크로 부문이 생겨나고 있으며, 하위 집단이 개별적인 상업적 기회로 통합되고 있습니다. AI를 활용한 디지털 병리학은 분류를 더욱 정교화하여, 제약 기업이 화합물과 반응이 가장 좋은 코호트를 연결할 수 있게 해줍니다. 이러한 정밀한 전략은 임상시험의 성공 확률을 높이고, 투자자의 신뢰를 강화하며, FSGS 치료 시장 전반의 동향을 주도하는 데 있어 원발성 FSGS가 수행하는 중심적인 역할을 더욱 공고히 하고 있습니다.
지역별 분석
북미는 생물학적 제제의 조기 도입, 집중된 신장학 전문 지식, 광범위한 보험 적용을 배경으로 2025년 매출의 38.29%를 차지하며 선두를 달렸습니다. 미국만 해도 4만 명 이상의 확진 환자가 있어, 향후 등장할 정밀 치료법에 있어 최대의 단일 국가 환자 풀을 형성하고 있습니다. 캐나다는 접근성을 원활하게 해주는 보편적인 보험 급여의 혜택을 받고 있는 반면, 멕시코에서는 확대되는 민간 의료 부문이 고도의 신장학 서비스에 대한 수요를 자극하고 있습니다.
유럽은 2위를 차지하고 있으며, EMA의 PRIME 패스웨이 및 수요가 높은 의약품을 신속하게 승인하는 협력적인 의료 기술 평가에 힘입고 있습니다. 독일, 프랑스, 영국은 단백뇨 감소제 사용을 선도하고 있는 반면, 남유럽 국가들은 EU의 구조 기금을 활용하여 신장 의료 인프라 구축을 추진하고 있습니다. 3상 임상시험의 중간 결과를 바탕으로 부여되는 조건부 시판 허가로 인해 환자들의 조기 접근이 가능해지면서, 유럽 전역의 FSGS 치료 시장이 더욱 탄력을 받고 있습니다.
아시아태평양은 가장 빠르게 성장하는 시장으로, 2031년까지 연평균 성장률(CAGR) 17.95%를 기록할 전망입니다. 중국에서는 희귀질환 치료제를 각 성의 보험 약제 목록에 포함시키는 노력을 통해 보험 적용 범위가 확대되고 있으며, 일본에서는 확립된 신장 의료 문화가 신약 보급을 가속화하고 있습니다. 한국의 ‘신장 건강 계획 2033’에서는 전국적인 조기 발견, 원격 신장 의료, 생검 표준화에 주력할 것을 제시하고 있습니다. 인도와 호주에서는 대조적인 동향이 나타나고 있습니다. 인도는 도시와 농촌 간의 접근성 격차에 직면해 있음에도 가장 큰 판매량 증가가 예상되는 반면, 호주는 강력한 연구 네트워크를 활용해 지역별 임상 검사를 주도하고 있습니다. 이러한 요인들이 복합적으로 작용함에 따라 FSGS 치료 시장은 세계화를 지속하고 있으며, 다국적 기업들은 다양한 보험 환급 제도와 인프라 실정에 맞추어 출시 계획을 조정하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the focal segmental glomerulosclerosis treatment market size is expected to grow from USD 14.95 billion in 2025 to USD 15.9 billion in 2026 and is forecast to reach USD 21.63 billion by 2031 at 6.34% CAGR over 2026-2031.
This report is Segmented by Disease Type (Primary FSGS, Secondary FSGS), Disease Management (Diagnosis, Treatment), End User (Hospitals & Transplant Centers, Specialty Clinics & Nephrology Practices, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Focal Segmental Glomerulosclerosis (FSGS) Treatment Market Trends and Insights
Increasing Prevalence of FSGS Linked to Metabolic Disorders
The continuing rise of diabetes and obesity is directly fuelling FSGS incidence, as metabolic stress accelerates podocyte loss and glomerular sclerosis. Pharmaceutical developers are therefore testing dual-pathway agents that modulate both metabolic and renal signals. Earlier screening of hypertensive and diabetic patients is boosting diagnostic volumes, which in turn enlarges the addressable base of the FSGS treatment market. Clinicians are embedding metabolic control measures into care pathways, creating long-term demand for combo regimens that integrate glycaemic and lipid management with podocyte-protective drugs.
Robust Therapeutic Pipeline & R&D Funding
Vertex's inaxaplin, Travere's sparsentan and several antisense constructs have secured FDA Breakthrough Therapy or Orphan Drug designations, shortening regulatory timelines. Venture funding for kidney startups jumped 45% in 2024, which is encouraging smaller biotechs to pursue complement inhibitors, podocyte-regeneration biologics and gene-silencing molecules. Pipeline breadth is making the FSGS treatment market increasingly attractive to strategic investors, accelerating deal flow and advancing first-time modalities toward commercial launch.
High Cost & Limited Access to Dialysis and Transplant
Annual U.S. dialysis expenditure averages USD 89,000 per patient and a kidney transplant costs about USD 442,500. Limited transplant supply and long waiting lists amplify the burden. Payers therefore scrutinize the cost-effectiveness of every new entrant and are slow to endorse high-price cell or gene therapies without long-term outcome data. In low- and middle-income countries, dialysis capacity constraints create a stark treatment gap and temper uptake of premium drugs, muting part of the FSGS treatment market's growth potential.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Incentives for Rare Kidney Disease Drugs
- Advances in Single-Cell Renal Transcriptomics Enabling Precision Targets
- Clinical Trial Recruitment Challenges in Rare Disease
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Primary FSGS captured 60.42% of the FSGS treatment market in 2025 and is set to post a 8.67% CAGR through 2031. The strong share reflects sensitivity to immunomodulators and emerging targeted agents that block immune-mediated podocyte loss. APOL1 genotyping has become routine, and patients with high-risk alleles are enrolling in trials of genotype-specific inhibitors such as inaxaplin. The FSGS treatment market size for primary disease is therefore projected to outpace secondary FSGS, whose therapy still hinges on addressing diabetes, hypertension or drug toxicity.
Genetic testing is spawning micro-segments defined by APOL1 status, collapsing sub-populations into discrete commercial opportunities. AI-enhanced digital pathology further refines classification, allowing drug makers to align compounds with the most responsive cohorts. These precision tactics increase trial success probability and heighten investor confidence, reinforcing the central role of primary FSGS in steering the overall trajectory of the FSGS treatment market.
Complete Report Scope:
- By Disease Type
- Primary FSGS
- Secondary FSGS
- By Disease Management
- Diagnosis
- Kidney Biopsy
- Creatinine Test
- Other Diagnostics
- Treatment
- Drug Therapy
- Corticosteroids
- Calcineurin Inhibitors
- Immunosuppressants
- Biologics
- APOL1 Inhibitors & Emerging Therapies
- Dialysis
- Hemodialysis
- Peritoneal Dialysis
- Kidney Transplant
- Drug Therapy
- Diagnosis
- By End User
- Hospitals & Transplant Centers
- Specialty Clinics & Nephrology Practices
- Dialysis Centers
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 38.29% of 2025 revenue on the back of early biologic uptake, concentrated nephrology expertise and broad insurance coverage. The United States alone hosts more than 40,000 diagnosed patients, forming the largest single-country pool for upcoming precision therapies. Canada benefits from universal reimbursement that smooths access, while Mexico's expanding private-care segment is stimulating demand for advanced nephrology services.
Europe ranks second, supported by the EMA's PRIME pathway and coordinated health-technology assessment that fast-track high-need drugs. Germany, France and the United Kingdom spearhead usage of proteinuria-lowering agents, whereas Southern Europe leverages EU structural funds to upgrade renal-care infrastructure. Conditional marketing approvals granted after interim phase-3 readouts are allowing earlier patient access and reinforcing the FSGS treatment market's momentum across the continent.
Asia Pacific is the fastest-growing arena, scheduled to post an 17.95% CAGR to 2031. China's drive to include rare-disease drugs on provincial formularies is widening the reimbursement base, and Japan's established nephrology culture accelerates new-drug uptake. Korea's Kidney Health Plan 2033 commits to nationwide early detection, tele-nephrology and biopsy standardisation. India and Australia present divergent dynamics: India faces rural-urban access gaps yet offers the largest volume upside, while Australia leverages strong research networks to lead regional trials. Together, these forces ensure that the FSGS treatment market continues to globalise, with multinational firms tailoring launch plans to varied reimbursement and infrastructure realities.
- Roche
- Genentech
- Novartis
- Merck
- Teva Pharmaceutical Industries
- Travere Therapeutics Inc.
- Vertex Pharmaceuticals
- AstraZeneca
- Pfizer
- Bristol-Myers Squibb
- Otsuka Pharmaceutical Co. Ltd.
- Equillium Inc.
- Goldfinch Bio
- Reata Pharmaceuticals Inc.
- Ionis Pharmaceuticals
- Chinook Therapeutics Inc.
- Omeros Corporation
- LabCorp
- Arkana Laboratories
- Allina Health Laboratory
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Prevalence of FSGS Linked to Metabolic Disorders
- 4.2.2 Robust Therapeutic Pipeline & R&D Funding
- 4.2.3 Regulatory Incentives for Rare Kidney Disease Drugs
- 4.2.4 Advances in Single-Cell Renal Transcriptomics Enabling Precision Targets
- 4.2.5 Rising Health-Equity Initiatives Expanding Early Biopsy in High-Risk Ethnic Populations
- 4.2.6 Increasing Adoption of Kidney Function Biomarkers for Early Diagnosis
- 4.3 Market Restraints
- 4.3.1 High Cost & Limited Access to Dialysis and Transplant
- 4.3.2 Clinical Trial Recruitment Challenges in Rare Disease
- 4.3.3 Adverse Effects & Relapse Rates with Current Immunosuppressants
- 4.3.4 Limited Long-Term Data for APOL1-Targeted Therapies
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Disease Type
- 5.1.1 Primary FSGS
- 5.1.2 Secondary FSGS
- 5.2 By Disease Management
- 5.2.1 Diagnosis
- 5.2.1.1 Kidney Biopsy
- 5.2.1.2 Creatinine Test
- 5.2.1.3 Other Diagnostics
- 5.2.2 Treatment
- 5.2.2.1 Drug Therapy
- 5.2.2.1.1 Corticosteroids
- 5.2.2.1.2 Calcineurin Inhibitors
- 5.2.2.1.3 Immunosuppressants
- 5.2.2.1.4 Biologics
- 5.2.2.1.5 APOL1 Inhibitors & Emerging Therapies
- 5.2.2.2 Dialysis
- 5.2.2.2.1 Hemodialysis
- 5.2.2.2.2 Peritoneal Dialysis
- 5.2.2.3 Kidney Transplant
- 5.2.2.1 Drug Therapy
- 5.2.1 Diagnosis
- 5.3 By End User
- 5.3.1 Hospitals & Transplant Centers
- 5.3.2 Specialty Clinics & Nephrology Practices
- 5.3.3 Dialysis Centers
- 5.3.4 Academic & Research Institutes
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 F. Hoffmann-La Roche Ltd.
- 6.3.2 Genentech Inc.
- 6.3.3 Novartis AG
- 6.3.4 Merck KGaA
- 6.3.5 Teva Pharmaceutical Industries Ltd.
- 6.3.6 Travere Therapeutics Inc.
- 6.3.7 Vertex Pharmaceuticals Incorporated
- 6.3.8 AstraZeneca plc
- 6.3.9 Pfizer Inc.
- 6.3.10 Bristol Myers Squibb Company
- 6.3.11 Otsuka Pharmaceutical Co. Ltd.
- 6.3.12 Equillium Inc.
- 6.3.13 Goldfinch Bio
- 6.3.14 Reata Pharmaceuticals Inc.
- 6.3.15 Ionis Pharmaceuticals Inc.
- 6.3.16 Chinook Therapeutics Inc.
- 6.3.17 Omeros Corporation
- 6.3.18 Labcorp
- 6.3.19 Arkana Laboratories
- 6.3.20 Allina Health Laboratory
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


