

|
시장보고서
상품코드
2122705
지붕용 멤브레인 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Roofing Membranes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 지붕용 멤브레인 시장 규모는 2025년에 103억 6,000만 달러로 평가되었고, 2026년 108억 7,000만 달러에서 2031년까지 138억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.97%를 나타낼 전망입니다.
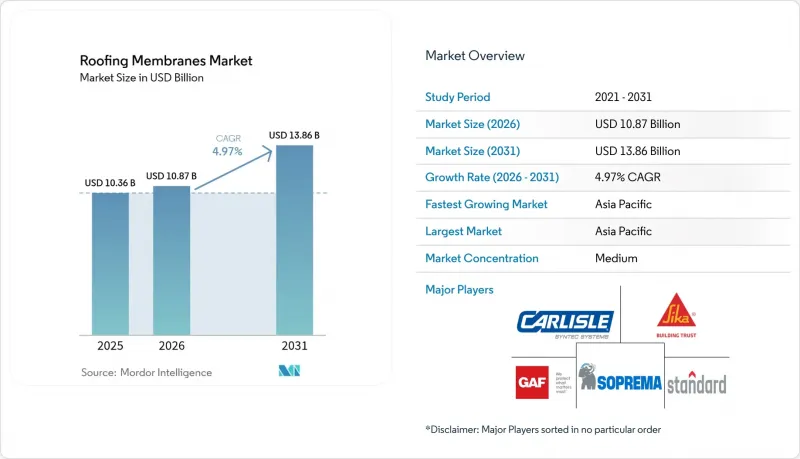
본 보고서는 제품 유형별(액상 도포형 방수 시트 및 시트형 방수 시트), 시공 방법별(기계 고정식, 전면 접착식 등), 용도별(주택, 상업시설, 공공시설, 인프라), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 지붕용 멤브레인 시장 동향 및 인사이트
쿨 루프 기준 준수 및 에너지 규제 강화에 따른 수요
캘리포니아주의 건축 에너지 기준, 국제 에너지 절약 기준(IECC),및 중국의 GB 55015-2021에서는 반사율 기준치가 상향 조정되어, 이로 인해 색상이 짙은 엘라스토머 제품은 사실상 사용이 불가능해졌으며, 사양은 흰색 TPO, PVC 및 고알베도 액체 코팅으로 전환되고 있습니다. ‘타이틀 24’의 2025년 개정에 따라, 경과 후 태양 반사율의 최저 기준이 상향 조정됨에 따라, 고비용이 드는 기존 지붕의 철거를 피하면서 태양 반사율 지수(SRI) 100 이상을 달성하는 아크릴계 및 실리콘계 시스템의 도입이 급속히 진행되고 있습니다. 미국 ‘선벨트’ 지역의 각 주와 여름이 더운 중국의 각 성에서 시행되는 유사한 규제로 인해, 반사성 화학제품의 고가 대가 유지되고 있습니다. 규제 준수 기한으로 인해 판매업체들은 허가 취득 중인 프로젝트의 지연을 피하기 위해 밝은 색상의 롤 소재와 저VOC 프라이머의 재고를 확충할 수밖에 없는 상황입니다. CRRC 등록 제품을 판매하고, 경과 후 가치 유지가 문서로 입증된 제조업체는 학교, 병원, 정부 기관의 공공 입찰 프로젝트에서 수주율 측면에서 유리한 입지를 점하고 있습니다.
친환경 건축 인증 프로그램의 확대
LEED v5, BREEAM International 2024 및 인도의 GRIHA v5는 반사율뿐만 아니라 내재 탄소 감축 및 검증된 환경 제품 선언(EPD)에 대한 평가 항목을 추가하고 있습니다. 사양 수립자들은 재생 소재, 바이오 폴리올,또는 수발포 폼을 포함한 필름 소재를 점점 더 요구하고 있으며, 이로 인해 쿨 루프 성능과 수명 주기 전반에 걸친 투명성이라는 이중 평가 기준이 생겨나고 있습니다. ISO 14025를 준수하는 EPD를 공개하고 있는 세계 주요 화학 제조업체들은 다국적 기업의 캠퍼스에서 우선 공급업체로서의 지위를 확보해 가고 있습니다. 평가 시스템의 통합으로 제출 형식이 표준화되고 컨설팅 비용이 절감될 뿐만 아니라, 대부분의 단일층 및 액상 제품 라인에서 비교 가능한 LCA 데이터를 이용할 수 있게 됨에 따라 입찰 평가가 가속화되고 있습니다.
엄격한 화재 안전 및 VOC/REACH 규제
유럽의 Broof(t1) 방화 분류, 캘리포니아주의 지붕용 코팅제에 대한 50 g/L의 VOC 상한선, 그리고 EU의 REACH에 기반한 PFAS 규제로 인해 배합 변경 비용이 상승하고 제품 포트폴리오가 세분화되고 있습니다. 제조업체는 각 막, 단열재, 데크의 조합마다 여러 차례의 실제 규모 EN 13501-1 시험 비용을 부담해야 하므로, 국경을 초월한 제품의 범용성이 저해되고 있습니다. 비불소계 계면활성제로의 전환으로 인해 원자재 비용이 최대 18% 상승했으며, 폴리우레탄 및 아크릴 제품 라인 전반에 걸쳐 선택적인 가격 인상이 이루어지고 있습니다. 사내 연구개발 체계를 갖추지 않고 신속한 시장 출시를 중시하는 지역 컨버터들은 다국적 위탁 블렌딩 업체로부터의 조달을 늘리고 있어, 이익률이 축소되고 있습니다.
부문 분석
액상 도포 시스템은 2025년에 매출의 60.66%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 5.34%로 확대될 것으로 전망됩니다. 이러한 규모는 지붕용 필름 소재 시장에서 가장 큰 점유율을 차지하는 요인이 되고 있습니다. 이는 아크릴 및 실리콘계 코팅이 기존 기판 위에 시공 가능하며, VOC 규제를 충족하고 이음매 없이 CRRC 인증 반사율을 달성할 수 있기 때문입니다. 아크릴계는 저렴한 비용과 UV 안정성 덕분에 여전히 판매량 1위를 유지하고 있습니다. 한편, 폴리우레아는 15초라는 빠른 경화 시간 덕분에 조기 운영 재개가 필수적인 플라자 데크나 주차장 같은 이용 사례에서 채택이 확대되고 있습니다. 시트 막은 나머지 매출을 차지하고 있으며, 광대한 시공 면적에서 효율적인 시공이 가능한 신축 물류 창고 등에서 여전히 선호되고 있습니다. 북미에서는 칼아일(Carlisle)사의 ‘Sure-Weld TPO’와 같이 ASTM D5034에 기반한 인장 강도가 350 lbf/in을 초과하는 배합이 선호되며, 열가소성 폴리올레핀(TPO)이 기존 PVC 시장 점유율을 꾸준히 잠식하고 있습니다. EPDM은 영하의 기후에서 여전히 중요한 위치를 차지하고 있지만, 그 어두운 표면은 쿨 루프 규제와 상충됩니다. 유럽의 주택용 지붕 개보수 시장에서는 특수한 자가 접착형 아스팔트 롤이 확대되고 있는 반면, 고밀도 폴리에틸렌 필름은 뿌리 침투를 방지하는 특성으로 인해 그린 루프의 틈새 시장을 개척하고 있습니다.
IKO사의 1.2 kg/m2 플리스 제품과 같은 고품질 HDPE 및 경량 TPO 제품군은 구조적 내력에 제약이 있는 개보수 공사 수요를 흡수할 수 있는 위치에 있습니다. 폴리머 원가 상승은 지붕 1동당 시공 공수 절감을 통해 상쇄되므로, 가격 차이는 좁은 수준을 유지하며 제품군 전체적으로 수명 주기 비용의 균형이 유지될 것입니다.
지역별 분석
아시아태평양은 2025년 전 세계 매출의 45.56%를 차지했으며, 예측 기간(2026-2031년) 동안 연평균 성장률(CAGR) 6.33%로 확대되어 지역별 최대 규모의 지붕용 막 시장 증가분을 가져올 것으로 예측됩니다. 중국의 662억 달러 규모의 ‘일대일로’ 관련 계약과 인도의 1,200억 달러 규모의 스마트 시티 주택 예산은 가성비가 뛰어난 EPDM 및 반사형 TPO에 대한 단기적인 수요를 뒷받침하고 있습니다. 2024년 노토 지진 이후 위험에 대한 인식이 높아진 것을 반영하여, 내진성이 뛰어난 기계 고정식 어셈블리가 2025년 도쿄의 상업용 지붕 재시공 공사의 58%를 차지했습니다. 아세안(ASEAN)의 민관 파트너십을 통해 연중 습도가 80%를 초과하는 산업단지에서 곰팡이 방지 폴리우레탄 코팅의 도입이 진행되고 있습니다.
2025년 북미의 매출은 지붕 재시공 주기, 허리케인 대책 기준의 의무화, 그리고 데이터센터 및 냉장 창고 건설 붐에 힘입어 증가했습니다. 플로리다주, 텍사스주, 그리고 캐롤라이나 양주의 창고 건설업자들은 보험 할인 혜택을 받기 위해 FM 인증을 받은 완전 접착형 TPO를 지정하고 있습니다. 캘리포니아주의 ‘타이틀 24’ 쿨 루프 규제로 인해, 해당 주의 연간 120억 달러 규모의 지붕 공사 지출에서 흰색 막재에 대한 수요가 유지되고 있습니다. 멕시코의 니어쇼어링 제조 추진에 따라 누에보 레온 주의 산업 지역에서는 급속 경화형 폴리우레아 막으로의 전환이 진행되고 있는 반면, 캐나다의 주택 개보수 시장에서는 전면 철거를 10년 연기할 수 있는 저VOC 아크릴계 코팅으로의 전환이 진행되고 있습니다.
유럽에서는 ‘리노베이션 웨이브’를 통해 2030년까지 3,500만 채의 건물을 개조한다는 목표가 제시되었으며, 옥상 태양광 발전 의무화로 인해 반사성 시트에 대한 수요가 증가하고 있습니다. 독일에서는 2025년에 14.1 GW 규모의 옥상 태양광 발전이 도입되었으며, 그 중 62%는 25년간의 태양광 발전 보증을 충족하기 위해 TPO 밑받침이 필요한 상업용 지붕에 설치되었습니다. 프랑스의 ‘RE 2020’ 탄소 배출 상한 규제로 인해 바이오 액상 폴리우레탄에 대한 관심이 집중되고 있습니다. 한편, 동유럽의 ‘결속 기금(Cohesion Fund)’ 프로젝트에서는 저소득층 주택을 위해 EPDM 및 아스팔트 롤이 채택되고 있습니다. 튀르키예의 내진 재건 사업으로 인해 유연한 기계 고정식 시스템의 채택이 확대되고 있습니다.
중동 및 아프리카에서는 사우디아라비아의 ‘비전 2030’ 기가 프로젝트, UAE의 7,920억 달러 규모 계획 사업, 그리고 남아프리카공화국의 재생에너지 시설에서 주변 열을 완화하기 위해 반사성 막이 우선적으로 채택되고 있습니다. 사우디아라비아의 대규모 주택 건설에서는 신속한 시공을 위해 박리·부착식 아스팔트가 사용되는 반면, 두바이의 ‘에스티다마 펄’ 기준에 따라 TPO 및 PVC의 채택이 진행되고 있습니다. 남미에서 시장 점유율은 브라질의 ‘민하 카사 민하 비다’ 주택 사업이 주도하고 있지만, 거시경제의 변동으로 인해 수입 공급이 계속해서 제약을 받고 있어, 예산을 중시하는 수요에는 현지 EPDM 제조업체가 대응하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the roofing membranes market size was valued at USD 10.36 billion in 2025 and is estimated to grow from USD 10.87 billion in 2026 to reach USD 13.86 billion by 2031, at a CAGR of 4.97% during the forecast period (2026-2031).
This report is Segmented by Product Type (Liquid Applied Membrane and Sheet Membrane), Installation Type (Mechanically Attached, Fully Adhered, and More), Application (Residential, Commercial, Institutional, and Infrastructural), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Roofing Membranes Market Trends and Insights
Demand for Cool-Roof Compliance and Energy-Code Stringency
Building-energy standards in California, the International Energy Conservation Code, and China's GB 55015-2021 are tightening reflectance thresholds, effectively disqualifying darker elastomeric products and shifting specifications toward white TPO, PVC, and high-albedo liquid coatings. Title 24's 2025 update raised minimum aged solar reflectance, prompting rapid adoption of acrylic and silicone systems that achieve Solar Reflectance Index scores above 100 while sidestepping costly tear-offs. Similar mandates in Sun Belt U.S. states and hot-summer Chinese provinces are sustaining premium pricing for reflective chemistries. Compliance deadlines have forced distributors to widen inventories of light-colored rolls and low-VOC primers to avoid project delays during permitting. Manufacturers that market CRRC-listed products with documented aged-value retention now win close-rate advantages on public-bid work in schools, hospitals, and government offices.
Expansion of Green-Building Certification Programs
LEED v5, BREEAM International 2024, and India's GRIHA v5 have moved beyond reflectance, layering in credits for embodied-carbon reduction and verified environmental product declarations. Specifiers increasingly demand membranes containing recycled content, bio-based polyols, or water-blown foams, creating a dual metric of cool-roof performance plus life-cycle transparency. Global chemical majors that publish ISO 14025-aligned EPDs are qualifying for preferred-supplier status on multinational corporate campuses. The convergence of rating systems is standardizing submittal formats, cutting consultant costs, and accelerating bid evaluations because comparable LCA data are now available across most single-ply and liquid lines.
Stringent Fire-Safety and VOC/REACH Regulations
European Broof(t1) fire classifications, California's 50 g/L VOC cap for roof coatings, and the EU REACH PFAS restrictions are driving reformulation costs upward and fragmenting product portfolios. Manufacturers must finance multiple full-scale EN 13501-1 tests for each membrane-insulation-deck combination, hampering cross-border product portability. Shifts to non-fluorinated surfactants have raised raw-material input costs up to 18%, prompting selective price surcharges across polyurethane and acrylic lines. Fast-to-market regional converters lacking in-house R&D are increasingly sourcing from multinational toll blenders, shrinking margins.
Other drivers and restraints analyzed in the detailed report include:
- Construction Boom in Emerging Economies
- Rooftop-Solar Retrofit Creating Need for Reflective Membranes
- Shortage of Certified Single-Ply Installers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Liquid-applied systems secured 60.66% revenue in 2025 and are projected to advance at a 5.34% CAGR through 2031. That scale translates into the single largest portion of the Roofing Membranes market size because acrylic and silicone coatings can be installed over existing substrates, satisfy VOC rules, and achieve CRRC-listed reflectance without seams. Acrylics remain the volume leader due to low cost and UV stability, while polyurea's rapid 15-second set time is unlocking plaza-deck and parking-garage use cases where fast return to service is critical. Sheet membranes claimed the remaining revenue, still favored for new-build logistics halls where large planes allow efficient roll-out. Thermoplastic polyolefin is steadily eroding legacy PVC share in North America, supported by formulations such as Carlisle's Sure-Weld TPO that deliver ASTM D5034 tensile strengths beyond 350 lbf/in. EPDM maintains relevance in sub-zero climates, though its dark surface conflicts with cool-roof rules. Specialty self-adhesive bitumen rolls are expanding among European residential re-roofing, while high-density polyethylene films are carving green-roof niches due to root-barrier properties.
Premium HDPE and light-weight TPO variants, such as IKO's 1.2 kg/m2 fleece products, are positioned to capture structural-capacity constrained retrofits. Price differentials will remain narrow as higher polymer costs are offset by reduced labor minutes per roof, preserving lifecycle cost parity across product families.
Complete Report Scope:
- By Product Type
- Liquid Applied Membrane
- Acrylic
- Polyurethane
- Polyurea
- Others
- Sheet Membrane
- Polyvinyl Chloride (PVC)
- Ethylene Propylene Diene Monomer (EPDM)
- Thermoplastic Polyolefin (TPO)
- Self-adhesive Bitumen
- High-density Polyethylene (HDPE)
- Others
- Liquid Applied Membrane
- By Installation Type
- Mechanically Attached
- Fully Adhered
- Ballasted
- Other Installation Types
- By Application
- Residential
- Commercial
- Institutional
- Infrastructural
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Romania
- Poland
- Serbia
- Turkey
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 45.56% of 2025 global revenues and is expected to rise at a 6.33% CAGR during the forecast period (2026-2031), adding the largest incremental Roofing membranes market size among regions. China's Belt and Road contracts worth USD 66.2 billion and India's USD 120 billion smart-city housing allocation underpin near-term demand for cost-effective EPDM and reflective TPO. Seismic-resilient mechanically attached assemblies secured 58% of Tokyo's 2025 commercial reroof activity, reflecting heightened risk awareness after the 2024 Noto event. ASEAN public-private partnerships are driving fungal-resistant polyurethane coatings on industrial parks where humidity exceeds 80% year-round.
North America's revenue in 2025 was held up by re-roofing cycles, hurricane-code dictate, and a wave of data-center and cold-storage jobs. Warehouse builders across Florida, Texas, and the Carolinas specify FM-rated fully adhered TPO to qualify for insurance credits. California's Title 24 cool-roof rule sustains white membrane volume in the state's USD 12 billion annual roofing spend. Mexico's near-shoring manufacturing drive is pivoting to rapid-cure polyurea membranes in Nuevo Leon industrial zones, while Canadian residential refurbishments are switching to low-VOC acrylic coatings that postpone full tear-offs by a decade.
In Europe, the Renovation Wave aims to upgrade 35 million buildings by 2030, with rooftop solar mandates pushing reflective sheets. Germany installed 14.1 GW of rooftop PV in 2025, 62% on commercial roofs that needed TPO substrates to match 25-year PV warranties. France's RE 2020 carbon caps are channeling interest toward bio-based liquid polyurethane, while Eastern European Cohesion Fund projects rely on EPDM and bitumen rolls for affordable housing. Turkish seismic reconstruction is boosting uptake of flexible mechanically attached systems.
In the Middle East and Africa, Saudi Vision 2030 giga-projects, the UAE's USD 792 billion pipeline, and South Africa's renewable-energy facilities all prefer reflective membranes to moderate ambient heat. Saudi mass-housing uses peel-and-stick bitumen for rapid construction, whereas Dubai's Estidama Pearl standards are driving TPO and PVC adoption. South America's share is paced by Brazil's Minha Casa Minha Vida housing, though macroeconomic volatility continues to constrain import supply, leaving local EPDM makers to meet budget-driven demand.
- Carlisle SynTec Systems
- Dow
- Duro-last Inc.
- Fosroc Inc.
- GAF Materials LLC
- Holcim
- IB Roof
- IKO Polymeric
- Isomat SA
- Johns Manville
- Juta Ltd
- Kemper System America Inc.
- Kingspan Group
- Nordic Waterproofing
- Owens Corning
- Paul Bauder GMBH & Co. KG
- Ph Plastics
- Saint-Gobain
- Sika AG
- Soprema Group
- Standard Industries Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for cool-roof compliance and energy-code stringency
- 4.2.2 Expansion of green-building certification programs
- 4.2.3 Construction boom in emerging economies
- 4.2.4 Rooftop-solar retrofit creating need for reflective membranes
- 4.2.5 Prefabricated modular roof-kit adoption accelerating membrane demand
- 4.3 Market Restraints
- 4.3.1 Stringent fire-safety and VOC / REACH regulations
- 4.3.2 Shortage of certified single-ply installers
- 4.3.3 Competition from spray-applied continuous-roof coatings
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Liquid Applied Membrane
- 5.1.1.1 Acrylic
- 5.1.1.2 Polyurethane
- 5.1.1.3 Polyurea
- 5.1.1.4 Others
- 5.1.2 Sheet Membrane
- 5.1.2.1 Polyvinyl Chloride (PVC)
- 5.1.2.2 Ethylene Propylene Diene Monomer (EPDM)
- 5.1.2.3 Thermoplastic Polyolefin (TPO)
- 5.1.2.4 Self-adhesive Bitumen
- 5.1.2.5 High-density Polyethylene (HDPE)
- 5.1.2.6 Others
- 5.1.1 Liquid Applied Membrane
- 5.2 By Installation Type
- 5.2.1 Mechanically Attached
- 5.2.2 Fully Adhered
- 5.2.3 Ballasted
- 5.2.4 Other Installation Types
- 5.3 By Application
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Institutional
- 5.3.4 Infrastructural
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Romania
- 5.4.3.7 Poland
- 5.4.3.8 Serbia
- 5.4.3.9 Turkey
- 5.4.3.10 Russia
- 5.4.3.11 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Carlisle SynTec Systems
- 6.4.2 Dow
- 6.4.3 Duro-last Inc.
- 6.4.4 Fosroc Inc.
- 6.4.5 GAF Materials LLC
- 6.4.6 Holcim
- 6.4.7 IB Roof
- 6.4.8 IKO Polymeric
- 6.4.9 Isomat SA
- 6.4.10 Johns Manville
- 6.4.11 Juta Ltd
- 6.4.12 Kemper System America Inc.
- 6.4.13 Kingspan Group
- 6.4.14 Nordic Waterproofing
- 6.4.15 Owens Corning
- 6.4.16 Paul Bauder GMBH & Co. KG
- 6.4.17 Ph Plastics
- 6.4.18 Saint-Gobain
- 6.4.19 Sika AG
- 6.4.20 Soprema Group
- 6.4.21 Standard Industries Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


