

|
시장보고서
상품코드
2122718
뇌 임플란트 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Brain Implants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 뇌 임플란트 시장 규모는 2025년에 31억 3,000만 달러로 평가되었고, 2026년 34억 5,000만 달러에서 2031년까지 56억 4,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 10.31%를 나타낼 전망입니다.

본 보고서는 제품 유형별(심부 뇌 자극 장치, 척수 자극 장치, 미주신경 자극 장치), 기술별(침습적, 저침습적, 비침습적), 용도별(파킨슨병, 만성 통증, 간질 등), 최종 사용자별(병원·뇌신경외과 센터, 전문 클리닉 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다.
세계의 뇌 임플란트 시장 동향 및 인사이트
신경퇴행성 질환 및 운동 장애 유병률 증가
세계 파킨슨병 환자 수는 2050년까지 2,520만 명에 달할 전망이며, 이는 현재 환자 수의 두 배로 증가하여 DBS(뇌심부 자극 요법)의 적응증 대상자층이 확대될 것입니다. 약물 저항성 간질은 이미 1,010만 명에게 영향을 미치고 있으며, 이들 환자는 여전히 외과적 개입의 대상이 됩니다. 한편, 치료 저항성 우울증은 정신과용 의료기기의 도입을 지속적으로 견인하고 있습니다. 선진국 시장의 고령화와 신흥 경제국의 진단 자원 향상이 맞물려, 수술 건수는 안정적으로 유지될 것으로 전망됩니다. 의료경제학 연구에 따르면, 2024년 DBS 수술을 통해 환자 1인당 연간 20,000-35,000달러의 약물비가 절감되어, 총 지출은 일반적으로 인정되는 비용 대비 효과의 기준치 이하로 억제되고 있습니다.
소형화 및 폐쇄 루프 기술의 발전
그래핀 전극과 나노 다공성 금속의 채택으로 임플란트의 점유 면적이 최대 70% 축소되어 신호의 충실도가 향상될 뿐만 아니라, 수술 후 염증도 경감되고 있습니다. 또한, 전력 소비를 줄여주는 뉴로모픽 프로세서 덕분에 배터리 수명이 연장되었으며, 애보트(Abbott)사의 ‘Infinity DBS’와 같은 충전식 플랫폼에서는 스마트폰을 이용한 매개변수 업데이트가 가능해졌습니다. 장치에 내장된 머신러닝 펌웨어가 자극을 실시간으로 조정함으로써, 치료는 고정된 설정에서 환자별로 최적화된 동적 프로토콜로 전환되고 있습니다. 이러한 발전들이 결합되어 외래 환자의 회복을 촉진하고, 장기적인 유효성을 높이며, 의료진의 수용을 더욱 확대하는 원동력이 되고 있습니다.
기기 및 수술 비용의 고가
하드웨어, 수술, 그리고 도입 첫해의 프로그래밍을 포함한 DBS 치료의 총 비용(1회분)은 14만-19만 달러 범위이며, 이후 유지 관리 비용은 연간 4,500-7,800달러가 듭니다. 많은 신흥국에서는 이러한 비용이 가구 연소득을 초과하여 보급을 저해하고 있습니다. 의료 제공업체와 제조업체 간의 가치 기반 계약은 점차 발전하고 있지만, 여전히 극히 일부 고소득 국가로 한정되어 있어 경제적 부담의 격차가 지속되고 있습니다.
부문 분석
심부 뇌 자극 장치는 파킨슨병, 본태성 진전, 근긴장 이상증에 대한 30년에 걸친 임상적 근거에 힘입어, 2025년에는 뇌 임플란트 시장에서 42.10%라는 압도적인 점유율을 차지했습니다. 전 세계적으로 16만 건 이상의 이식 수술이 이루어지고 있으며, 이 치료법은 외과의사와 보험사에게 그 어느 때보다 친숙한 것이 되었습니다. 강박 장애와 같은 새로운 적응증이 3상 임상시험을 통과함에 따라 전 세계적인 성장은 견조한 추세를 보이고 있습니다. 한편, 척수 자극 장치는 만성 통증 및 당뇨병성 신경병증 사례에서 꾸준한 도입 실적을 유지하며, 기존 기업의 수익원을 더욱 다각화하고 있습니다.
미주신경 자극 장치는 가장 빠르게 성장하고 있는 분야로, 2031년까지 연평균 성장률(CAGR)이 11.22%를 나타낼 것으로 예측됩니다. 약물 저항성 간질, 치료 저항성 우울증, 염증성 질환 등 광범위한 적응증이 전문 분야를 초월한 도입을 뒷받침하고 있습니다. 기술의 최첨단을 달리는 기업들은 펄스 발생기의 소형화와 리드선의 내구성 향상에 주력하고 있으며, 이를 통해 수술 시간 단축과 재수술 건수 감소를 가능하게 하고 있습니다. 전반적으로 뇌 임플란트 시장은 여전히 제품 혁신이 주도하고 있으며, 폐쇄 루프형 DBS 시스템과 발작 반응형 신경 자극 장치가 이용 사례를 확대하는 동시에 안정적인 평균 판매 가격(ASP)을 뒷받침하고 있습니다.
2025년에도 정확한 전극 배치와 충분한 보험 환급을 받을 수 있는 치료 경로 덕분에, 침습적 정위 수술은 뇌 임플란트 시장에서 70.85%의 점유율을 계속 차지했습니다. 2025년 코호트를 대상으로 한 메타분석에 따르면, 뇌혈관 장애 발생률은 2.71%, 영구적 장애는 1.0%, 사망률은 0.4%로 보고되었으며, 이러한 수치는 외과의사와 규제 당국 모두에게 안심할 수 있는 근거가 되고 있습니다. 로봇 보조 내비게이션과 3테슬라 MRI 유도 기술을 병용함으로써 합병증 발생률은 감소 추세를 유지하고 있습니다.
한편, Synchron사의 혈관 내 스텐트로드(Stentrode)와 같은 저침습적 접근법도 세를 넓혀가고 있으며, 연평균 성장률(CAGR)은 11.74%로 예측됩니다. 경정맥을 통한 삽입으로 개두술이 불필요해지고 수술 시간이 단축될 뿐만 아니라, 외래수술센터(ASC)로의 확대도 가능해질 수 있습니다. 항염증제로 코팅된 유연한 폴리머 리드는 이물 반응을 완화하며, 단일 접근을 통한 삽입은 감염 위험을 줄여줍니다. 이러한 저침습 전략이 성숙해짐에 따라 적응증 환자층이 확대되고, 지역적 확산이 가속화되어 수술 건수의 점진적인 증가를 뒷받침하고 있습니다.
지역별 분석
북미는 여전히 주도적인 위치를 유지하고 있으며, 전 세계 매출의 52.70%를 차지하고 있습니다. 이는 FDA의 패스트트랙 제도, 풍부한 자금원, 그리고 여러 적응증에 대한 확립된 보험 적용이 뒷받침하고 있습니다. 미국의 병원들은 펠로우십 과정을 수료한 기능 신경외과 전문의가 밀집해 있다는 점과, Neuralink, Precision Neuroscience, Synchron이 주도하는 활기찬 스타트업 생태계로부터도 혜택을 받고 있습니다. 캐나다에서는 파킨슨병 및 본태성 진전에 대한 DBS를 의학적으로 필요한 것으로 인정하는 국민건강보험 제도 덕분에 지역 전체의 총 환자 수가 증가하고 있습니다.
유럽은 이에 근소한 차이로 뒤를 잇고 있으며, 조정된 의료 기술 평가(HTA) 절차와 혁신적인 임플란트 승인을 가속화하는 EU 의료기기 규정(MDR)의 신속 심사 절차가 그 기반이 되고 있습니다. 독일, 프랑스, 영국은 합쳐서 수많은 DBS 전문센터를 보유하고 있으며, VNS 및 RNS의 보험 적용과 관련된 대규모 시범 사업을 계속하고 있습니다. 북유럽 국가들은 디지털 헬스 프레임워크를 활용하여 원격 DBS 프로그래밍을 지원하고, 효율적인 장거리 치료 모델을 입증하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 12.11%를 나타낼 것으로 전망되며, 가장 역동적인 성장 지역으로 부상하고 있습니다. 중국은 신경과학 연구 개발 및 고성능 의료기기 제조에 막대한 투자를 단행하며, 서유럽 국가들과의 기술 격차를 좁혀가고 있습니다. 일본에서는 고령화가 진행됨에 따라 운동 장애 치료법에 대한 수요가 증가하고 있으며, 국민건강보험제도로 인해 환자의 진료 접근성이 용이해지고 있습니다. 인도, 한국, 호주는 민관 파트너십과 최첨단 학술 연구를 결합하여 임상시험 처리 능력을 향상시킴으로써 지역 성장을 주도하고 있습니다. 중동 및 아프리카 및 남미는 아직 발전 단계에 있지만, 미래가 기대되고 있습니다. GCC 국가들은 국가 의료 혁신 계획의 일환으로 주요 뇌신경외과 허브를 지원하고 있는 반면, 브라질과 아르헨티나는 거시경제의 변동에도 불구하고, 대상을 좁힌 보험 급여 시범 사업을 추진하고 있습니다. 장기적인 성장 가능성은 전문의 양성 확대, 환율 리스크 안정화, 그리고 지방 지역의 원격의료 인프라 확충에 달려 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the brain implants market size was valued at USD 3.13 billion in 2025 and estimated to grow from USD 3.45 billion in 2026 to reach USD 5.64 billion by 2031, at a CAGR of 10.31% during the forecast period (2026-2031).
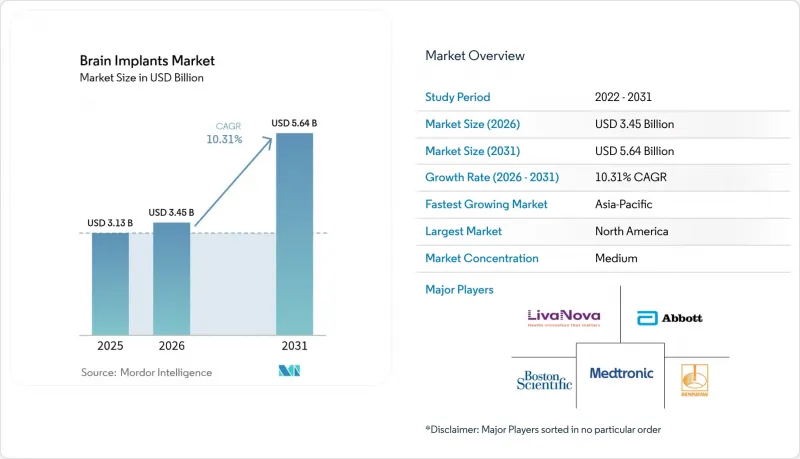
This report is Segmented by Product Type (Deep Brain Stimulators, Spinal Cord Stimulators, Vagus Nerve Stimulators), by Technology (Invasive, Minimally-Invasive, Non-Invasive), by Application (Parkinson's Disease, Chronic Pain, Epilepsy, and More), by End User (Hospitals & Neurosurgical Centers, Specialty Clinics, and More), by Geography (North America, Europe, Asia-Pacific, and More).
Global Brain Implants Market Trends and Insights
Rising Prevalence of Neuro-degenerative & Movement Disorders
Global Parkinson's disease cases are on track to hit 25.2 million by 2050, doubling today's burden and widening the pool of DBS candidates. Drug-resistant epilepsy already affects 10.1 million people who remain eligible for surgical intervention, while treatment-resistant depression continues to drive psychiatric device adoption. Aging demographics in developed markets and improved diagnostic resources in emerging economies combine to ensure consistent procedure volumes. Health-economic studies showed 2024 DBS procedures saving USD 20,000-35,000 per patient annually in medication costs, keeping total expenditures below commonly accepted cost-effectiveness thresholds.
Miniaturization & Closed-loop Technology Advances
Graphene electrodes and nanoporous metals have shrunk implant footprints by up to 70%, improving signal fidelity and lowering post-surgical inflammation. Batteries now last longer thanks to neuromorphic processors that cut power draw, with rechargeable platforms such as Abbott's Infinity DBS allowing smartphone-based parameter updates. On-device machine-learning firmware adjusts stimulation in real time, moving therapy from static settings to dynamic, patient-specific protocols. These advances collectively accelerate outpatient recovery, lift long-term efficacy, and fuel wider physician acceptance.
High Device & Surgical Procedure Cost
A full DBS episode, including hardware, surgery, and year-one programming, ranges from USD 140,000 to 190,000, with follow-up maintenance at USD 4,500-7,800 per year. In many emerging countries these fees outstrip annual household income, curbing penetration. Value-based contracting between providers and manufacturers is evolving, yet remains confined to a handful of high-income settings, prolonging the affordability gap.
Other drivers and restraints analyzed in the detailed report include:
- Favorable Reimbursement Expansion in U.S./EU
- AI-driven Adaptive Stimulation Algorithms
- Cybersecurity & Data-privacy Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Deep brain stimulators held a commanding 42.10% of brain implants market share in 2025, anchored by three-decade clinical evidence for Parkinson's, essential tremor, and dystonia. More than 160,000 implants have been placed worldwide, giving the modality unrivalled procedural familiarity among surgeons and payers. Global growth remains healthy as new indications such as obsessive-compulsive disorder move past pivotal trials. Meanwhile, spinal cord stimulators maintain solid volumes across chronic pain and diabetic neuropathy cases, further diversifying revenue streams for incumbents.
Vagus nerve stimulators represent the fastest-moving opportunity, charting an 11.22% CAGR through 2031. Multipronged utility in drug-resistant epilepsy, treatment-resistant depression, and inflammatory disorders boosts cross-specialty adoption. Technology front-runners are miniaturising pulse generators and improving lead durability, allowing shorter operating times and fewer revision surgeries. Overall, the brain implants market remains product-innovation led, with closed-loop DBS systems and seizure-responsive neurostimulators expanding use cases while supporting stable ASPs.
Invasive stereotactic surgery continues to account for a 70.85% foothold within the brain implants market in 2025 thanks to precise electrode positioning and well-reimbursed care pathways. Meta-analyses covering 2025 cohorts document cerebrovascular events at 2.71%, permanent impairment at 1.0%, and mortality at 0.4%, numbers that reassure surgeons and regulators alike. Concurrent adoption of robot-assisted navigation and 3-Tesla MRI guidance keeps complication rates on a downward trajectory.
Yet, minimally-invasive approaches such as Synchron's endovascular Stentrode are gaining momentum with a forecast 11.74% CAGR. Implantation via the jugular vein eliminates craniotomy, cuts procedure time, and may allow expansion into ambulatory surgical centers. Flexible polymer leads coated with anti-inflammatory agents reduce foreign-body responses, while single-access delivery lowers infection risks. As these less-invasive strategies mature, they broaden candidate pools and speed geographic roll-outs, propelling incremental volume growth.
Complete Report Scope:
- By Product Type
- Deep Brain Stimulators
- Spinal Cord Stimulators
- Vagus Nerve Stimulators
- By Technology
- Invasive (Surgical)
- Minimally-Invasive / Percutaneous
- Non-invasive (Trans-cranial)
- By Application
- Parkinson's Disease
- Chronic Pain
- Epilepsy
- Depression & Psychiatric Disorders
- Essential Tremor
- Other Applications
- By End User
- Hospitals & Neurosurgical Centers
- Specialty Clinics
- Ambulatory Surgical Centers
- Academic & Research Institutes
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of APAC
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retains primacy, contributing 52.70% of global revenue, anchored by FDA fast-track pathways, deep capital pools, and entrenched reimbursement coverage for multiple indications. U.S. hospitals also benefit from a dense concentration of fellowship-trained functional neurosurgeons and a flourishing start-up ecosystem led by Neuralink, Precision Neuroscience, and Synchron. Canada amplifies regional totals through universal health insurance that recognises DBS as medically necessary for Parkinson's and essential tremor.
Europe follows closely, underpinned by coordinated HTA processes and EU MDR accelerated review tracks that expedite innovative implants. Germany, France, and the United Kingdom collectively host scores of DBS centers of excellence and continue to pilot large-scale VNS and RNS reimbursements. Nordic countries leverage digital health frameworks to support remote DBS programming, demonstrating efficient long-distance care models.
Asia-Pacific emerges as the most dynamic corridor with a 12.11% CAGR outlook. China invests heavily in neuroscience R&D and high-end device manufacturing, narrowing technology gaps with Western peers. Japan's aging population fuels strong demand for movement-disorder solutions, while the nation's universal insurance simplifies patient uptake. India, South Korea, and Australia round out regional growth by combining public-private partnerships with leading academic research to spur clinical trial throughput. The Middle East & Africa and South America remain nascent yet promising. GCC states back flagship neurosurgical hubs as part of national health-innovation agendas, while Brazil and Argentina push forward targeted reimbursement pilots despite macroeconomic volatility. Long-term upside hinges on scaling specialist training, stabilizing currency risk, and expanding tele-programming infrastructure in rural locales.
- Abbott Laboratories
- Boston Scientific
- Medtronic
- LivaNova
- NeuroPace
- Aleva Neurotherapeutics
- Newronika S.p.A.
- Saluda Medical
- Renishaw
- Paradromics
- MicroTransponder, Inc.
- Synchron
- Blackrock Neurotech
- Precision Neuroscience Corporation
- Synergia Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of neuro-degenerative & movement disorders
- 4.2.2 Miniaturization & closed-loop technology advances
- 4.2.3 Favorable reimbursement expansion in U.S./EU
- 4.2.4 AI-driven adaptive stimulation algorithms (under-reported)
- 4.2.5 FDA Breakthrough & EU MDR fast-track pathways (under-reported)
- 4.2.6 Surge in neurotech mega-funding & VC activity
- 4.3 Market Restraints
- 4.3.1 High device & surgical procedure cost
- 4.3.2 Limited long-term clinical evidence in some indications
- 4.3.3 Cyber-security & data-privacy concerns (under-reported)
- 4.3.4 Scarcity of specialist neurosurgeons in emerging markets (under-reported)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Deep Brain Stimulators
- 5.1.2 Spinal Cord Stimulators
- 5.1.3 Vagus Nerve Stimulators
- 5.2 By Technology
- 5.2.1 Invasive (Surgical)
- 5.2.2 Minimally-Invasive / Percutaneous
- 5.2.3 Non-invasive (Trans-cranial)
- 5.3 By Application
- 5.3.1 Parkinson's Disease
- 5.3.2 Chronic Pain
- 5.3.3 Epilepsy
- 5.3.4 Depression & Psychiatric Disorders
- 5.3.5 Essential Tremor
- 5.3.6 Other Applications
- 5.4 By End User
- 5.4.1 Hospitals & Neurosurgical Centers
- 5.4.2 Specialty Clinics
- 5.4.3 Ambulatory Surgical Centers
- 5.4.4 Academic & Research Institutes
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of APAC
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, ... Recent Developments)
- 6.4.1 Abbott
- 6.4.2 Boston Scientific Corporation
- 6.4.3 Medtronic
- 6.4.4 LivaNova PLC
- 6.4.5 NeuroPace, Inc.
- 6.4.6 Aleva Neurotherapeutics
- 6.4.7 Newronika S.p.A.
- 6.4.8 Saluda Medical Pty Ltd.
- 6.4.9 Renishaw plc.
- 6.4.10 Paradromics
- 6.4.11 MicroTransponder, Inc.
- 6.4.12 Synchron
- 6.4.13 Blackrock Neurotech
- 6.4.14 Precision Neuroscience Corporation
- 6.4.15 Synergia Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


