

|
시장보고서
상품코드
2122724
소화관 스텐트 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Gastrointestinal Stent - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 소화관 스텐트 시장 규모는 2025년에 5억 8,780만 달러로 평가되었고, 2026년 6억 1,784만 달러에서 2031년까지 7억 9,264만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.11%를 나타낼 전망입니다.
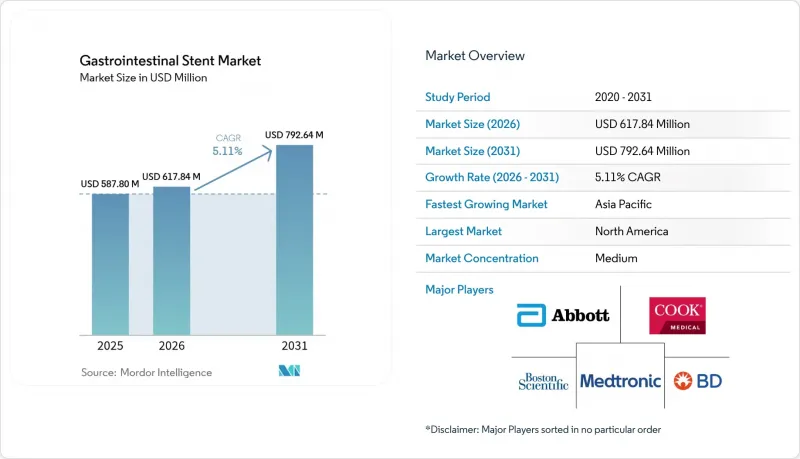
본 보고서는 제품 유형별(담도 스텐트, 결장 스텐트 등), 소재별(자가팽창형 금속 스텐트, 플라스틱 스텐트 등), 용도별(담도 질환, 대장암 등), 최종 사용자별(병원, 외래수술센터(ASC) 등), 지역별(북미, 유럽, 아시아태평양 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 소화관 스텐트 시장 동향 및 인사이트
소화기암 유병률 증가
2024년, 아시아의 대장암 발생률은 인구 10만 명당 23.88명에 달하여 위암을 제치고 가장 흔한 소화기 계통 악성 종양이 되었으며, 수술 전까지의 가교 역할로서 대장 스텐트에 대한 지속적인 수요를 창출하고 있습니다. 자가 팽창형 금속 스텐트는 악성 위출구 폐색에서 현재 89.7%의 임상 성공률을 달성하고 있으며, 지속적인 개통성을 확보하여 응급 수술 횟수를 줄이고 있습니다. 수술 전 화학요법과 스텐트 삽입의 병용으로 종양 축소와 수술 결과가 최적화되어 시술 건수가 더욱 증가하고 있습니다. 암 검진 활동의 확대와 생존율 향상으로 인해 경과 관찰이나 완화 치료 상황에서도 시술 빈도가 유지되고 있습니다.
고령화와 동반되는 소화기 질환
인구 고령화에 따라 양성 담도 협착이나 췌장염 관련 합병증이 증가하고 있으나, 이러한 사례는 개복 수술에 적합하지 않은 경우가 많습니다. 단축형 완전 피복형 금속 스텐트는 고령 환자군에서 발생하는 양성 협착의 99%를 해소함과 동시에, 수술에 비해 시술 위험과 입원 기간을 단축시킵니다. 강화된 이동 방지 기능 덕분에 고령 환자에게서 흔히 나타나는 취약한 조직 구조에도 대응할 수 있습니다. 가치 기반 의료를 추구하는 의료 시스템에서는 이러한 저침습적 치료법이 선호되며, 성숙한 시장에서 장기적인 활용이 촉진되고 있습니다.
의료기기와 관련된 유해 사건 및 재시술
FDA 보고서에 따르면, 스텐트 삽입 위치 문제(35.6%)와 이탈 사건(12.4%)이 의료기기와 관련된 주요 불만 사항으로 꼽혔으며, 환자 관련 사건에서는 출혈과 천공이 가장 많이 발생했습니다. 이탈률은 40%에 육박하기도 하여, 비용 및 환자 안전에 대한 우려가 커지고 있습니다. 체내에 남아 있는 플라스틱 담관 스텐트는 담관염의 위험이나 폐색 사고를 증가시키기 때문에 자동 회수 알림 시스템의 도입이 요구되고 있습니다. 차세대 이탈 방지 핀이나 생분해성 스텐트는 2차 시술을 줄이고 품질 지표를 향상시키는 것을 목표로 하고 있습니다.
부문 분석
담도 스텐트는 2025년 소화관 스텐트 시장 매출의 36.82%를 차지했으며, 악성 및 양성 담도 폐쇄에서 확고한 역할을 수행하고 있음을 반영합니다. 레이저 절단 방식의 형상, 친수성 코팅, 그리고 저프로파일 전달 카테터를 통해 협착된 담관이나 복잡한 담관 문부 병변에 정확하게 삽입할 수 있습니다. 식도 및 십이지장용 스텐트는 연하 곤란 완화를 개선하는 개량형 역류 방지 밸브의 혜택을 받아 판매량 측면에서 그 뒤를 잇고 있습니다.
대장용 스텐트는 2031년까지 연평균 성장률(CAGR) 8.67%로 가장 높은 성장률을 보일 전망입니다. 비교 연구에 따르면, 자가 팽창형 금속 스텐트는 응급 수술과 동등한 생존율 및 삶의 질(QOL) 결과를 가져오는 한편, 인공 항문 형성을 피할 수 있는 것으로 나타났습니다. 내부 플랩이 없는 췌장용 스텐트는 80.7%가 자연 이동을 보이기 때문에 제거 시술을 생략할 수 있으며, 외래 치료 프로토콜에도 적합합니다. 약물 방출형 스텐트의 개선은 현재 조직 침투 억제를 목표로 하고 있으며, 모든 제품군에서 새로운 가치 제안을 제시하고 있습니다.
자가 팽창형 금속 기기는 2025년 매출의 61.05%를 차지했으며, 그 방사형 강도와 유연성의 균형이 두드러집니다. 임상시험에서 회장-맹장부 폐색에 대해 100%의 기술적 성공률과 92.3%의 임상적 성공률이 확인되어, 기존의 좌측 결장 이외의 영역에서도 적용 가능성이 입증되었습니다. 레이저 절단을 통한 마이크로 메쉬 패턴을 포함한 첨단 니티놀 가공 기술로, 구부러진 해부학적 구조에서도 뛰어난 적합성이 향상되었습니다.
연평균 성장률(CAGR) 8.41%로 성장을 지속하고, 있는 생분해성 및 약물 방출형 제품은 제거가 필요 없는 일시적인 스캐폴드에 대한 수요를 충족시키고 있습니다. 철계 프로토타입은 기계적 예비 능력을 향상시키는 동시에, X선 불투과성으로 인한 추적이 가능합니다. 하이브리드 구조는 금속 백본의 신뢰성과 시간 제어형 분해성을 겸비하고 있어, 양성 질환 관리에서 적응 범위의 확대가 기대됩니다. 플라스틱 제품은 조기 제거가 계획된 경우의 단기 배액에 여전히 유용하며, 소화관 스텐트 시장에서 틈새 시장 지위를 유지하고 있습니다.
지역별 분석
북미는 확립된 보험 환급 경로와 높은 수준의 시술 전문 지식을 바탕으로 2025년 매출의 35.12%를 차지했습니다. 메디케어(Medicare)의 명확한 소화관 스텐트 삽입술 보험 적용 범위는 예측 가능한 지급 주기를 뒷받침하고 있으며, 제조업체 주도의 레지스트리는 보험사가 보험 적용 범위를 업데이트하는 데 가속도를 붙이는 실제 임상 데이터를 제공합니다. 미국의 의료 기관에서는 스텐트 삽입술, 화학요법, 수술을 통합한 다학제적 종양 위원회를 중시하고 있어 성숙한 수요를 유지하고 있습니다. 캐나다의 국민건강보험제도 역시 공평한 접근성을 보장하며, 안정적인 기준선 시술 건수를 촉진하고 있습니다.
아시아태평양은 고령화, 대장암 발병률 증가, 그리고 공적 보험의 확대에 힘입어 2031년까지 연평균 성장률(CAGR) 7.88%로 가장 높은 성장률을 보이고 있습니다. 중국의 병원 설비 갱신 프로그램과 지역별 대장암 검진으로 인해 시술 대상 범위가 확대되고 있습니다. 일본의 초고령화 사회에서는 저침습적 접근이 요구되고 있는 반면, 인도의 의료기기 마케팅 행동 강령은 상업적 인센티브와 윤리적 보급 활동 간의 균형을 모색하고 있습니다. 그러나 환급액의 편차와 가격 상한선은 여전히 도입을 가로막는 결정적인 요인으로 작용하고 있어, 합리적인 가격을 중시하는 단계적인 제품 포트폴리오 구축이 요구되고 있습니다.
유럽에서는 조화로운 MDR(의료기기 규정) 체계와 견고한 임상 네트워크에 힘입어 한 자릿수 중반대의 꾸준한 성장이 예상됩니다. ESGE(유럽 내시경 외과학회)가 표준화한 연수를 통해 시술자의 숙련도가 향상되고 있으며, 국경을 초월한 데이터 공유가 기술 평가 주기를 가속화하고 있습니다. 라틴아메리카 및 중동 및 아프리카는 신흥 시장으로, 인프라 확충과 민간 병원에 대한 투자가 첨단 내시경 검사 도입을 위한 기반을 마련하고 있지만, 환율 변동과 보험 제도의 파편화로 인해 당분간 시장 침투가 더딘 양상을 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the gastrointestinal stent market size was valued at USD 587.80 million in 2025 and estimated to grow from USD 617.84 million in 2026 to reach USD 792.64 million by 2031, at a CAGR of 5.11% during the forecast period (2026-2031).
This report is Segmented by Product Type (Biliary Stent, Colonic Stent and More), Material (Self-Expanding Metal Stent, Plastic Stent and More), Application (Biliary Disease, Colorectal Cancer and More), End User (Hospitals, Ambulatory Surgical Centers and More) and Geography (North America, Europe, Asia-Pacific and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Gastrointestinal Stent Market Trends and Insights
Rising Prevalence of GI Cancers
Colorectal cancer incidence in Asia climbed to 23.88 per 100,000 population in 2024, overtaking stomach cancer as the dominant GI malignancy and creating sustained demand for colonic stents as bridge-to-surgery aids. Self-expandable metal stents now achieve 89.7% clinical success for malignant gastric outlet obstruction, delivering durable patency and fewer emergency surgeries.Integration of neoadjuvant chemotherapy with stent placement optimizes tumor shrinkage and surgical outcomes, further strengthening procedure volumes. Broadening cancer screening initiatives coupled with improved survival rates sustains procedure frequency into follow-up and palliative contexts.
Ageing Population & Comorbid GI Disorders
Demographic ageing increases benign biliary strictures and pancreatitis-related complications, conditions often unsuitable for open surgery. Short fully covered metal stents resolve 99% of benign strictures in older cohorts, while lowering procedural risk and hospital stay relative to surgery.Enhanced anti-migration features address fragile tissue architecture common in geriatric patients. Health systems seeking value-based care favor these minimally invasive routes, reinforcing long-term utilization across mature markets.
Device-Related Adverse Events & Re-Interventions
FDA reports list stent positioning issues (35.6%) and migration events (12.4%) as leading device complaints, with hemorrhage and perforation topping patient-related events. Migration rates can approach 40%, raising cost and patient-safety concerns. Forgotten plastic biliary stents increase cholangitis risk and clogging incidents, prompting calls for automated retrieval reminders. Next-generation anti-migration fins and biodegradable formats aim to cut secondary procedures and enhance quality metrics.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Minimally Invasive Endoscopy
- Rapid Adoption of EUS-Guided Stenting
- Stringent Multi-Region Regulatory Pathways
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biliary stents held 36.82% share of 2025 revenues in the gastrointestinal stent market, reflecting their entrenched role in malignant and benign biliary obstructions. Laser-cut geometries, hydrophilic coatings, and low-profile delivery catheters foster accurate placement in narrowed ducts and complex hilar lesions. Esophageal and duodenal stents follow in volume, benefitting from improved anti-reflux valves that enhance dysphagia relief.
Colonic stents supply the fastest 8.67% CAGR through 2031. Comparative studies show self-expandable metal stents deliver survival and quality-of-life outcomes on par with emergent surgery while avoiding colostomy formation. Pancreatic designs without internal flaps record 80.7% spontaneous migration, sparing retrieval procedures and aligning with outpatient protocols. Drug-eluting refinements now target tissue in-growth inhibition, signaling new value propositions across all product classes.
Self-expanding metal devices captured 61.05% of 2025 revenue, underlining their balance of radial strength and flexibility. Clinical trials confirm 100% technical success for ileocecal obstruction and 92.3% clinical success, validating adaptability outside the traditional left-sided colon. Advanced nitinol processing, including laser-cut micro-mesh patterns, improves conformability across tortuous anatomy.
Biodegradable and drug-eluting formats, posting an 8.41% CAGR, answer the call for temporary scaffolding without removal. Iron-based prototypes enhance mechanical reserve while enabling radiopacity tracking. Hybrid constructs bring metallic backbone reliability alongside timed degradation, promising to shift indication boundaries for benign disease management. Plastic remains relevant for short-term drainage when retrieval is planned early, preserving a niche position in the gastrointestinal stent market.
Complete Report Scope:
- By Product Type
- Biliary Stent
- Esophageal Stent
- Duodenal Stent
- Colonic Stent
- Pancreatic Stent
- By Material
- Self-Expanding Metal Stent (SEMS)
- Plastic Stent
- Biodegradable / Drug-eluting Stent
- By Application
- Biliary Disease
- Colorectal Cancer
- Stomach Cancer
- Inflammatory Bowel Disease
- Other Applications
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 35.12% of 2025 turnover, buoyed by established reimbursement pathways and deep procedural expertise. Medicare's defined coverage for GI stenting underpins predictable payment cycles, while manufacturer-driven registries furnish real-world evidence that speeds payer updates. United States centers emphasize multidisciplinary tumor boards integrating stenting, chemotherapy, and surgery, sustaining mature demand. Canada's universal insurance similarly ensures equitable access, fostering stable baseline volumes.
Asia-Pacific delivers the fastest 7.88% CAGR through 2031, propelled by aging demographics, growing colorectal cancer incidence, and expanded public insurance. China's hospital upgrade program and regional CRC screening widen procedural addressability. Japan's super-aged population mandates minimally invasive approaches, while India's device-marketing code of conduct seeks to balance commercial incentives with ethical outreach. Reimbursement variability and price caps, however, remain decisive adoption throttles, compelling tiered product portfolios targeting affordability.
Europe displays steady mid-single-digit growth underpinned by harmonized MDR frameworks and robust clinical networks. ESGE-standardized training expands operator proficiency, while cross-border data sharing accelerates technology assessment cycles. Latin America and Middle East & Africa constitute emerging arenas; infrastructure expansion and private-sector hospital investment create runway for advanced endoscopy, yet currency volatility and fragmented insurance dampen immediate penetration.
- Boston Scientific
- Cook Group
- Beckton Dickinson
- Olympus Corp.
- Merit Medical Systems
- CONMED Corp.
- Micro-Tech (Nanjing)
- S&G Biotech
- ELLA-CS
- Hobbs Medical
- M.I. Tech
- Endo-Flex
- BVM Medical
- AMG International
- ENDOBASE (Spiggle & Theis)
- Bioring SA
- Medtronic
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence Of Gi Cancers
- 4.2.2 Ageing Population & Comorbid Gi Disorders
- 4.2.3 Shift Toward Minimally Invasive Endoscopy
- 4.2.4 Rapid Adoption Of Eus-Guided Stenting
- 4.2.5 Ai-Driven Stent Design & Customization
- 4.2.6 Technological Advancement And Increasing Adoption Of Biodegradable Stents
- 4.3 Market Restraints
- 4.3.1 Device-Related Adverse Events & Re-Interventions
- 4.3.2 Stringent Multi-Region Regulatory Pathways
- 4.3.3 Reimbursement Gaps In Emerging Markets
- 4.3.4 Nitinol Supply-Chain Volatility & Price Spikes
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Product Type
- 5.1.1 Biliary Stent
- 5.1.2 Esophageal Stent
- 5.1.3 Duodenal Stent
- 5.1.4 Colonic Stent
- 5.1.5 Pancreatic Stent
- 5.2 By Material
- 5.2.1 Self-Expanding Metal Stent (SEMS)
- 5.2.2 Plastic Stent
- 5.2.3 Biodegradable / Drug-eluting Stent
- 5.3 By Application
- 5.3.1 Biliary Disease
- 5.3.2 Colorectal Cancer
- 5.3.3 Stomach Cancer
- 5.3.4 Inflammatory Bowel Disease
- 5.3.5 Other Applications
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Specialty Clinics
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Boston Scientific Corp.
- 6.3.2 Cook Medical
- 6.3.3 BD
- 6.3.4 Olympus Corp.
- 6.3.5 Merit Medical Systems
- 6.3.6 CONMED Corp.
- 6.3.7 Micro-Tech (Nanjing)
- 6.3.8 S&G Biotech
- 6.3.9 ELLA-CS
- 6.3.10 Hobbs Medical
- 6.3.11 M.I. Tech
- 6.3.12 Endo-Flex GmbH
- 6.3.13 BVM Medical
- 6.3.14 AMG International
- 6.3.15 ENDOBASE (Spiggle & Theis)
- 6.3.16 Bioring SA
- 6.3.17 Medtronic plc
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


