

|
시장보고서
상품코드
2122725
의료용 레이저 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Medical Laser - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 의료용 레이저 시장 규모는 2025년 62억 달러로 평가되었고, 2026년에는 70억 1,000만 달러로 추정되고, 2026-2031년 CAGR 13.12%로 성장을 지속할 전망이며, 2031년에는 129억 9,000만 달러에 이를 것으로 예측됩니다.
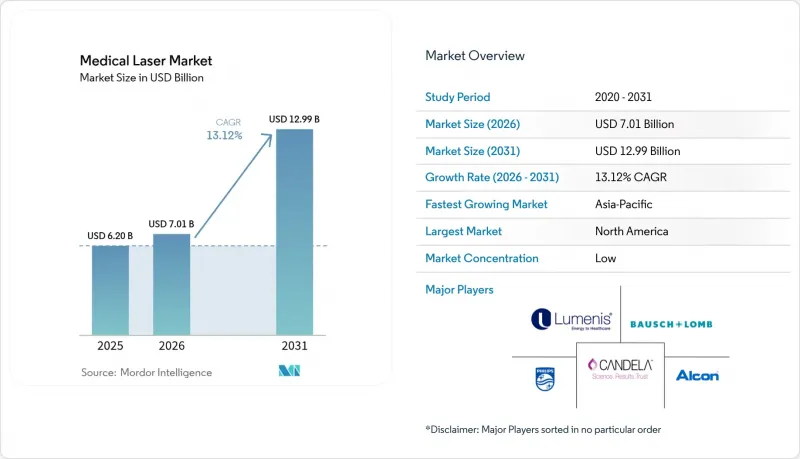
본 보고서는 제품 유형별(고체 레이저 시스템, 가스 레이저 시스템, 염료 레이저 시스템, 반도체 레이저 시스템), 용도별(안과, 피부과/미용, 산부인과 등), 최종 사용자별(병원, 외래수술센터(ASC) 등) 및 지역별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러)으로 표시되어 있습니다.
세계의 의료용 레이저 시장 동향 및 인사이트
저침습 수술에 대한 선호도 증가
현재 미국에서 시행되는 전체 수술의 72%가 외래수술센터(ASC)에서 이루어지고 있으며, 이로 인해 시설 비용이 45-60% 절감되는 동시에 회복 기간을 단축하는 레이저 기술로의 전환이 가속화되고 있습니다. 알콘(Alcon)사의 ‘Unity VCS’와 같은 펨토초 레이저 시스템은 백내장 초음파 유화 흡입술(파코에멀시피케이션)에 필요한 에너지를 줄여 안전성과 수술실 회전율을 향상시킵니다. 외래 진료에서 환자 만족도가 92%로 높은 점이 수요를 뒷받침하고 있으며, 의료 제공업체들은 레이저 플랫폼을 도입할 수밖에 없는 상황입니다. 그렇지 않으면 기동성이 더 뛰어난 경쟁사에게 환자 수를 빼앗길 위험이 있기 때문입니다. 상환 모델이 일시불로 전환되는 가운데, 임상의들은 합병증과 재입원을 줄이는 치료법을 선호하는 경향이 있어, 이는 의료용 레이저 시장에 지속적인 성장 동력을 제공합니다. 소매형 클리닉 체인의 확장으로 의료 접근성이 더욱 확대되면서, 일상적인 피부 및 안과 시술이 병원에서 클리닉으로 이동하고 있습니다.
안과 질환 부담 증가
미국의 녹내장 환자 수는 2025년 500만 명에서 2050년에는 630만 명으로 증가한 것으로 평가되었으며, 이에 따라 소량성형술 및 백내장 수술 건수가 증가할 전망입니다. LumiThera사의 광생물 조절 플랫폼 ‘Valeda’가 FDA 승인을 획득한 것은 노인성 황반변성(건성형)에 대한 최초의 승인 치료법이 된 것으로, 치료를 받은 눈의 58%에서 24개월 동안 시력이 5글자 이상 개선되었습니다. 아시아태평양은 생활 방식의 변화에 따른 당뇨병성 망막병증으로 인해 유사한 압박에 직면하고 있으며, 다이오드 및 솔리드 스테이트 안과용 레이저에 대한 투자가 지속되고 있습니다. 이러한 동향으로 인해 예산 제약이 있음에도 불구하고 의료용 레이저 시장은 정밀의료의 우선 순위와 계속해서 밀접하게 연계되고 있습니다.
높은 도입 비용과 유지비
펨토초 백내장 치료 플랫폼의 가격은 40만-50만 달러이며, 여기에 1회당 사용료로 300-400달러가 추가되므로 소규모 진료소에서는 예산 부담이 큽니다. 엑시머 레이저 시스템의 가격은 2만 4,011-19만 8,000달러 범위이며, 연간 유지보수 비용은 구매 가격의 평균 3.13%를 차지하고, 그 비용의 3분의 2는 인건비가 차지합니다. 리스는 현금 흐름 부담을 줄여주지만, 수명 주기 비용을 상승시키기 때문에 신흥국에서의 도입을 제한하고, 의료용 레이저 시장 전체의 성장을 둔화시키고 있습니다.
부문 분석
2025년에는 고체 레이저 플랫폼이 매출의 33.84%를 차지했으며, 고출력 절개 및 응고 분야에서 그 신뢰성이 입증되었습니다. 그러나 445nm 및 880nm 기종이 더 큰 규모의 설계와 동등한 성능에 도달함에 따라, 다이오드 시스템은 의료용 레이저 시장에서 가장 높은 연평균 성장률(CAGR) 14.03%를 나타낼 것으로 예측됩니다. 휴대용 핸드피스가 진료소에서의 수술 및 미용 시술에 대응할 수 있게 됨에 따라, 다이오드 기기의 의료용 레이저 시장 규모는 현저하게 확대될 것으로 예측됩니다.
다이오드는 냉각 요구 사항이 낮다는 장점이 있어, 원격 피부과 진료나 이동식 안과 클리닉에 적합한 배터리 구동형 옵션을 가능하게 합니다. 가스 레이저 및 염료 레이저는 얇은 빔이 필수적인 자외선 치료나 혈관성 병변 치료 분야에서 틈새 시장을 차지하고 있습니다. 희토류 공급망의 제약으로 인해 다이오드 채택이 일시적으로 주춤할 가능성은 있지만, 효율 향상과 대규모 공장 생산을 통해 다이오드는 의료용 레이저 시장에서 장기적인 비용 면에서의 우위를 유지하고 있습니다.
지역별 분석
2025년, 북미는 의료용 레이저 시장의 41.11%를 차지했으며, 견실한 보험 환급 제도와 밀집된 ASC(외래수술센터(ASC)) 네트워크에 힘입었습니다. 알콘(Alcon)이 고니오 렌즈 없이 120펄스를 조사할 수 있는 ‘Voyager DSLT’를 신속하게 출시한 것은 이 지역의 선구자적 문화를 상징합니다. 캐나다는 미국의 동향을 반영하고 있지만, 자본 사이클이 더 엄격하기 때문에 리스 모델이 선호되고 있습니다.
유럽은 혁신과 MDR(의료기기 규정)로 인한 비용 부담의 균형을 맞추면서 안정적인 상황을 유지하고 있습니다. 칼 자이스 메디텍은 굴절 교정 수술용 소모품의 호조에 힘입어 2025년 초 EMEA 지역에서 17.1%의 매출 성장을 기록했습니다. 그러나 인증 절차의 장기화는 중소 공급업체에 제약 요인이 되어, 의료용 레이저 시장이 기존 브랜드를 중심으로 재편될 가능성이 있습니다.
아시아태평양은 연평균 성장률(CAGR) 14.31%로 가장 빠르게 성장하는 시장입니다. 2024년 중국 레이저 분야의 10.2% 성장은 공립 병원의 현대화와 미용 수요 증가를 반영했습니다. 일본과 한국에서는 AI를 활용한 엑시머 레이저 시스템이 도입되고 있으며, 인도에서는 민관 협력을 통한 안과 의료 거점 구축이 진행되고 있습니다. 아세안(ASEAN) 국가들은 인프라 측면의 제약이 있음에도 불구하고 의료 관광을 유치하고 있어, 지역 의료용 레이저 시장 규모 확대에 기여하고 있습니다. 환율 변동과 수입 관세는 여전히 장벽으로 작용하고 있지만, 긍정적인 인구 동향에 힘입어 지속적인 성장이 예상됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the medical laser market size is expected to grow from USD 6.20 billion in 2025 to USD 7.01 billion in 2026 and is forecast to reach USD 12.99 billion by 2031 at 13.12% CAGR over 2026-2031.
This report is Segmented by Product Type (Solid State Laser Systems, Gas Laser Systems, Dye Laser Systems, and Semiconductor Laser Systems), Application (Ophthalmology, Dermatology/Aesthetics, Gynecology, and More), End User (Hospitals, Ambulatory Surgical Centers, and More), and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Medical Laser Market Trends and Insights
Rising Preference for Minimally-Invasive Procedures
Ambulatory surgery centers now conduct 72% of all US surgeries, cutting facility costs by 45-60% and accelerating the shift toward laser techniques that shorten recovery times . Femtosecond systems such as Alcon's Unity VCS reduce phacoemulsification energy, improving safety and operating-room turnover. High patient-satisfaction scores-92% in outpatient settings-reinforce demand, compelling providers to adopt laser platforms or risk losing volume to more agile competitors. As reimbursement models move toward bundled payments, clinicians favor modalities that lower complications and readmissions, giving the medical laser market sustained momentum. Expansion of retail-clinic chains further democratizes access, allowing routine skin and eye procedures to migrate away from hospitals.
Increasing Burden of Eye Disorders
Glaucoma incidence in the US is projected to climb from 5 million in 2025 to 6.3 million by 2050, raising procedure volumes for trabeculoplasty and cataract surgery. The FDA clearance of LumiThera's Valeda photobiomodulation platform marked the first approved treatment for dry age-related macular degeneration, with 58% of treated eyes gaining >=5 letters over 24 months. Asia-Pacific faces parallel pressure from diabetic retinopathy tied to lifestyle shifts, sustaining investment in diode and solid-state ophthalmic lasers. These dynamics keep the medical laser market firmly aligned with precision-medicine priorities despite budget constraints.
High Capital & Maintenance Costs
Femtosecond cataract platforms carry USD 400,000-500,000 price tags, plus per-use fees of USD 300-400, stretching budgets in smaller practices. Excimer systems range from USD 24,011 to USD 198,000, while annual maintenance averages 3.13% of purchase value, with labor forming two-thirds of expense. Leasing eases cash flow but boosts lifetime cost, limiting uptake in emerging economies and tempering overall medical laser market growth.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Aesthetic & Cosmetic Laser Treatments
- Technological Advances in Solid-State & Diode Platforms
- AI-Enabled Auto-Calibration & Beam-Shaping Software Adoption
- Expansion of Outpatient Laser Suites in Retail-Clinic Chains
- Stringent Safety & Operator-Training Regulations
- Rare-Earth Material Shortages for Diode Pump Modules
- Cyber-Security Vulnerabilities in Networked Laser Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solid-state platforms controlled 33.84% of revenue in 2025, validating their reliability for high-power cutting and coagulation. Yet diode systems are projected to post a 14.03% CAGR, the fastest within the medical laser market, as 445 nm and 880 nm variants reach performance parity with bulkier designs. The medical laser market size for diode devices is forecast to expand notably as portable handpieces support office-based surgery and aesthetics.
Diodes benefit from lower cooling demands, allowing battery-powered options that fit tele-dermatology and mobile ophthalmology clinics. Gas and dye lasers hold niche positions for ultraviolet treatments and vascular lesions where narrow lines are paramount. Supply-chain constraints in rare-earths may temper diode adoption briefly; however, efficiency gains and factory-scale production give diodes a long-term cost edge in the medical laser market.
Complete Report Scope:
- By Product Type
- Solid-state Laser Systems
- Diode (Semiconductor) Laser Systems
- Gas Laser Systems
- Dye Laser Systems
- By Application
- Ophthalmology
- Dermatology & Aesthetics
- Gynecology
- Dentistry
- Urology
- Cardiovascular
- Others (ENT, Oncology)
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty & Aesthetic Clinics
- Academic & Research Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- GCC
- South Africa
- Rest of Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 41.11% of the medical laser market in 2025, underpinned by robust reimbursement pathways and a dense ASC network. Alcon's rapid roll-out of the Voyager DSLT, which delivers 120 pulses without a gonio lens, typifies the region's first-mover culture. Canada mirrors US trends, albeit with tighter capital cycles that favor lease models.
Europe remains stable, balancing innovation with MDR-driven cost burdens. Carl Zeiss Meditec posted 17.1% revenue growth in EMEA in early 2025, buoyed by refractive-surgery consumables . However, extended certification timelines may constrain smaller vendors, potentially consolidating the medical laser market around established brands.
Asia-Pacific is the fastest-growing arena at a 14.31% CAGR. China's 10.2% 2024 laser-sector growth reflects public-hospital overhauls and rising aesthetic demand. Japan and South Korea deploy AI-enhanced excimer systems, while India advances through public-private ophthalmology hubs. ASEAN nations, though infrastructure-limited, attract medical tourism, adding volume to regional medical laser market size. Currency volatility and import duties remain hurdles, but demographic momentum signals sustained expansion.
List of Companies Covered in this Report:
- Alcon
- Lumenis (Boston Scientific)
- Candela Medical
- Carl Zeiss
- Bausch + Lomb
- BIOLASE
- Cutera
- IRIDEX
- Koninklijke Philips
- Alma Lasers
- Fotona
- Cynosure
- El.En Group
- Quanta System
- Coherent
- Dentsply Sirona
- Topcon
- Spectranetics
- Omnilux
- PhotoMedex
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising preference for minimally-invasive procedures
- 4.2.2 Increasing burden of eye disorders
- 4.2.3 Growing demand for aesthetic & cosmetic laser treatments
- 4.2.4 Technological advances in solid-state & diode platforms
- 4.2.5 AI-enabled auto-calibration & beam-shaping software adoption
- 4.2.6 Expansion of outpatient laser suites in retail-clinic chains
- 4.3 Market Restraints
- 4.3.1 High capital & maintenance costs
- 4.3.2 Stringent safety & operator-training regulations
- 4.3.3 Rare-earth material shortages for diode pump modules
- 4.3.4 Cyber-security vulnerabilities in networked laser systems
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Solid-state Laser Systems
- 5.1.2 Diode (Semiconductor) Laser Systems
- 5.1.3 Gas Laser Systems
- 5.1.4 Dye Laser Systems
- 5.2 By Application
- 5.2.1 Ophthalmology
- 5.2.2 Dermatology & Aesthetics
- 5.2.3 Gynecology
- 5.2.4 Dentistry
- 5.2.5 Urology
- 5.2.6 Cardiovascular
- 5.2.7 Others (ENT, Oncology)
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Specialty & Aesthetic Clinics
- 5.3.4 Academic & Research Institutes
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Alcon
- 6.3.2 Lumenis (Boston Scientific)
- 6.3.3 Candela Medical
- 6.3.4 Carl Zeiss Meditec
- 6.3.5 Bausch + Lomb
- 6.3.6 Biolase
- 6.3.7 Cutera
- 6.3.8 IRIDEX
- 6.3.9 Philips
- 6.3.10 Alma Lasers
- 6.3.11 Fotona
- 6.3.12 Cynosure
- 6.3.13 El.En Group
- 6.3.14 Quanta System
- 6.3.15 Coherent
- 6.3.16 Dentsply Sirona
- 6.3.17 Topcon
- 6.3.18 Spectranetics
- 6.3.19 Omnilux
- 6.3.20 PhotoMedex
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


