

|
시장보고서
상품코드
2122746
커넥티드 가로등 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Connected Street Lighting - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
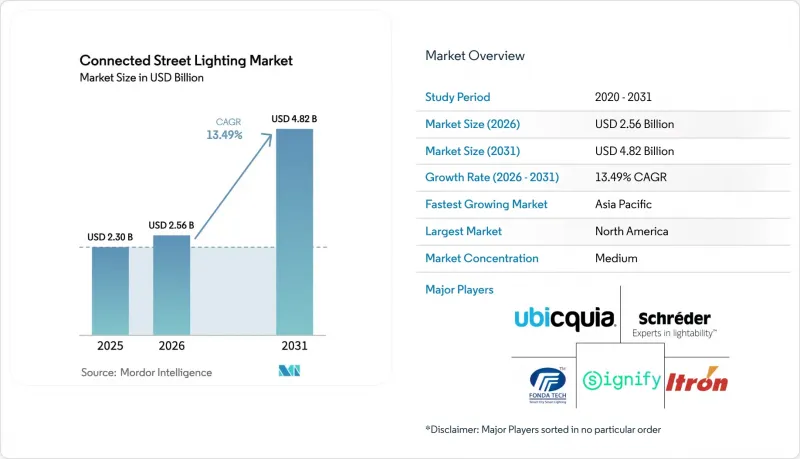
에 의하면, 커넥티드 가로등 시장 규모는 2026년 25억 6,000만 달러에 달하고 예측 기간 중에 CAGR 13.49%를 나타내며, 2031년까지 48억 2,000만 달러에 이를 것으로 예측됩니다.

본 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 연결성(RF 메쉬(Wi-SUN, IEEE 802.15.4g), 기타),용도(스마트 조광·정책 기반 스케줄링, 기타), 최종 사용자(지자체·지방 자치단체, 전력 회사·배전 시스템 사업자, 기타) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 커넥티드 가로등 시장 동향 및 인사이트
전기 요금 급등과 에너지 효율화 의무화가 개조의 경제성을 더욱 높이고 있습니다.
제어 기능을 갖춘 네트워크형 LED 가로등은 대규모 프로그램에서 에너지 소비 및 운영·유지보수(O&M) 비용 절감이라는 가시적인 성과를 가져오고 있으며, 이를 통해 규모 확대에 대한 비즈니스 타당성이 강화되고 있습니다. 시카고에서 29만 기의 가로등을 도입함으로써 연간 전기 요금이 870만 달러 절감되었고, 5년 동안 전력 회사로부터 3,700만 달러의 리베이트를 받았을 뿐만 아니라, 2022년 9월까지 총 13만 4,600톤의 이산화탄소 배출 감축을 달성했습니다. 스마트 조명 플랫폼의 수익 관리 수준 측정 기능은 규정 준수와 보고 업무의 효율화를 지원하며, 고가의 변전소용 계측 장비의 필요성을 없애줍니다. 온타리오주의 2025년 송전망 계획 지침은 프로젝트 선정 과정에서 ‘비송전선 전략’을 중시하며, 적응형 조명을 전력 회사 및 지자체에 있어 유연한 수요 반응 도구로 자리매김하고 있습니다. 조달 팀은 컨트롤러 지원 조명 기기를 리베이트 수령 자격 및 탈탄소화 진행 상황 추적과 연계하는 경향이 강해지고 있어, 지자체 에너지 정책에서 커넥티드 조명의 역할이 더욱 강화되고 있습니다. 도시들이 예산 확보와 기후 목표 달성을 목표로 하는 가운데, 이러한 동향이 스마트 가로등 관리 시스템 시장의 지속적인 수요를 뒷받침하고 있습니다.
스마트 시티 프로그램의 가속화와 PPP를 통한 조달로 지방자치단체의 재정적 위험 완화
민관 협력(PPP)을 통해 도시는 성과 위험을 이전하고, 에너지 절감 효과를 수년에 걸친 예측 가능한 결제로 전환할 수 있게 됩니다. 에너지 서비스 계약(ESCO)을 통한 세르비아의 포제가(Pozega) 프로젝트는 초기 투자 자금이 부족한 소규모 지자체에게 현대화와 검증 가능한 성과를 달성할 수 있는 실용적인 모델로 꼽히고 있습니다. 인도의 ‘스마트 시티 미션’은 주요 도로 조명, 지능형 교차로, 커넥티드 폴에 막대한 자금을 투입하고 있으며, 이를 통해 대규모 입찰이 지속되고 급성장하는 도시권의 디지털 인프라 구축이 가속화되고 있습니다. 이러한 모델은 검증된 에너지 절감 효과를 바탕으로, 장기적인 유틸리티과 같은 현금 흐름을 선호하는 인프라 펀드도 유치하고 있습니다. 다자간 계약이 성숙해짐에 따라 성능 보증, 원격 모니터링, 오픈 데이터 조항이 표준화되어 벤더 리스크에 대한 우려가 완화되고, 대출 적격성이 향상되고 있습니다. 이러한 구조적 변화는 재정적 제약으로 인해 업그레이드가 정체되는 상황에서도 스마트 가로등 관리 시스템 시장의 꾸준한 성장을 뒷받침하고 있습니다.
높은 초기 비용, 복잡한 입찰 절차, 자금 조달이 소규모 지자체에 과도한 부담을 주는
네트워크 지원 조명 기구 및 컨트롤러의 도입은 자본 집약도를 높이며, 소규모 도시가 하나의 예산 주기 내에서 이를 흡수하기는 어렵습니다. 성과 기반 계약이나 가동률 연동형 결제(Availability-Payment) 방식의 PPP는 에너지 절약 리스크를 민간 사업자에게 전가하지만, 검증 및 모니터링 요건으로 인해 조달 기간이 장기화될 가능성이 있습니다. 지자체는 초기 설비 비용을 배제하고, 정량화 가능한 운영·유지보수(O&M) 비용 절감에 기반한 예측 가능한 월정액 요금제로의 전환을 도모하기 위해 ‘LaaS(Lighting-as-a-Service)’ 도입을 검토하고 있습니다. 전력 회사의 무선 솔루션에 대한 지지로 인해, 본래라면 네트워크 업그레이드가 승인될 만한 장소에서도 적응형 조명의 도입이 더욱 매력적으로 변하고 있습니다. 다만, 필요한 서류 작성 및 부서 간 조정에 따라 승인 절차가 지연될 가능성이 있습니다. 장기적인 비용 절감이 기대됨에도 불구하고, 소규모 지자체는 입찰에 따른 부담이 증가하고 있으며, 이는 스마트 가로등 관리 시스템 시장의 단기적인 도입을 억제하는 요인이 되고 있습니다.
부문별 분석
2025년, 스마트 가로등 관리 시스템 시장에서 하드웨어가 62%를 차지한 반면, 소프트웨어 및 서비스는 연평균 성장률(CAGR) 13.65%로 성장하고 있습니다. 이는 각 도시가 원격 제어, 펌웨어 업데이트, 탄소 배출량 산정 대시보드를 가능하게 하는 중앙 관리 시스템을 도입하고 있기 때문입니다. Interact 및 유사한 SaaS 서비스와 같은 도시 플랫폼을 통해 지출 형태가 초기 투자에서 엔드포인트별 이용료로 전환되었으며, 보안이 강화된 API를 통해 교통 신호, 전기차 충전기, 공공 안전 정보와의 통합이 가능해졌습니다. 대규모 운영에서 사업자는 하루에 수백만 건의 텔레메트리 메시지를 관리하고 있으며, 이를 통해 각 조명 기구의 디지털 트윈 모델이 구축되어 조명 설비군 전체의 서비스 계획 및 가용성 지표 향상이 도모되고 있습니다. 소프트웨어 시장 점유율 확대는 도시의 지속가능성 계획에서 수익 등급 측정 및 검증 가능한 배출량 보고를 권장하는 정책도 반영하고 있습니다. ANSI C136.41 및 Zhaga Book 18에 따른 소켓 표준화가 진행됨에 따라 하드웨어 호환성이 높아지고 가격 경쟁이 심화되는 한편, 스마트 가로등 관리 시스템 시장에서 소프트웨어를 통한 차별화의 중요성이 더욱 커지고 있습니다.
턴키 방식의 PPP 계약에서는 설치, 시운전, 수년에 걸친 성과 의무가 패키지화되어 있기 때문에 서비스 부문이 여전히 큰 비중을 차지하고 있지만, 가치가 분석 및 자동화로 이동함에 따라 그 성장세는 소프트웨어 부문에 뒤처지고 있습니다. 예지 보전은 O&M(운영·유지보수) 비용을 측정 가능하게 절감하고, 사후 대응형 현장 출동을 예정된 개입으로 전환함으로써 작업을 통합하고 수리 소요 시간을 단축합니다. 스마트 가로등 관리 시스템 산업이 API 및 표준화된 데이터 모델을 활용하여 시 당국의 각 부서 간에 지식을 공유함에 따라, 이러한 동향은 계속해서 SaaS 및 통합 서비스에 대한 지출을 촉진하고 있습니다. 2026년부터 2031년에 걸쳐 소프트웨어 주도 성장은 계량 및 탄소 배출량 공개와 관련된 정책적 인센티브에 힘입어 가속화될 것이며, 이는 분석 기능의 프리미엄 가격 유지에 기여할 것입니다. 이러한 구성은 지속적인 수익을 강화하고, 스마트 가로등 관리 시스템 시장에서 하드웨어 이익률 하락으로부터 공급업체를 보호합니다.
Wi-SUN 및 IEEE 802.15.4g를 포함한 독자적인 사양의 RF 메시 네트워크는 2025년에 연결 점유율의 55.5%를 차지했으나, 도시들이 도입의 간소화와 캐리어 등급의 가동률을 중시함에 따라,셀룰러 제어는 연평균 성장률(CAGR) 13.73%를 나타낼 것으로 예측됩니다. 워싱턴 D.C.에서는 7만 5,000대의 램프 레벨 셀룰러 컨트롤러를 도입함으로써, 배포의 복잡성을 줄이면서도 실시간 모니터링을 가능하게 하고, 게이트웨이 설치 및 유지보수를 불필요하게 만들었습니다. LwM2M과 같은 표준 디바이스 관리 프레임워크는 대규모의 분산된 엔드포인트 그룹의 신뢰성과 수명 주기 관리를 향상시킵니다. LoRaWAN은 장거리·저처리량 통신으로 충분하며, 주파수 대역 관리가 현실적인 장소, 특히 배터리 소모가 적은 엔드포인트가 필요한 설치 공간이 제한된 지역에서 여전히 선호되고 있습니다. 프로젝트 소유자는 구독 요금과 게이트웨이 운영 비용을 비교 검토하고 있으며, 스마트 가로등 관리 시스템 시장에서 인력 제약이나 일정이 의사 결정의 주요 기준이 되는 경우, 많은 경우 셀룰러 방식이 선택되고 있습니다.
RF 메쉬는 결정론적인 작동과 다년간의 운영 실적을 갖춘 독자적인 관리 네트워크를 선호하는 유틸리티 부문에서 여전히 중요한 역할을 하고 있습니다. 틈새 시장 이용 사례로는 무선 성능이 저하되기 쉬운 배관 내의 전력선 통신, 가로등 규모의 통신 범위가 필요하지 않은 캠퍼스 환경용 Wi-Fi 및 단거리 통신 기술 등을 들 수 있습니다. 지역을 불문하고 여러 기술이 혼재하는 상황은 계속되고 있지만, 상호 운용성과 인증을 통해 잠금이 완화되어 단일 CMS를 통해 다양한 기기군을 관리할 수 있게 되었습니다. 규격이 성숙해짐에 따라, 벤더 선정 및 라이프사이클 업그레이드 시 선택지를 확보하기 위해 듀얼 소켓 컨트롤러를 채택하는 도시가 늘고 있습니다. 이로 인해 스마트 가로등 관리 시스템 시장에서의 조달 경쟁이 유지되고 있습니다. 이러한 균형을 통해 기존 RF 네트워크의 연속성이 확보되는 동시에, 총 소유 비용(TCO)을 최적화하는 ‘셀룰러 우선’ 방식의 스케일아웃이 가능해집니다.
지역별 분석
2025년 시점에서 유럽은 도입 기반 측면에서 65%의 선두를 유지했으며, 이는 지난 10년에 걸친 협력적인 개보수 및 정책 지원을 반영한 결과입니다. 이러한 노력을 통해 커넥티드 제어 시스템은 유틸리티체에게 규정 준수 도구이자 운영 기반으로서의 입지를 확고히 했습니다. 이 점유율은 스마트 가로등 관리 시스템 시장의 중요한 부분을 차지하고 있으며, 구매자들은 긴 자산 수명 동안 멀티 벤더 설비군을 관리하기 위해 TALQ 인증을 우선시하고 있습니다. 브뤼셀과 국도에서 진행된 프로젝트는 표준화된 인터페이스가 컨트롤러와 조명 기구 간의 CMS 상호 운용성을 확보하고 통합의 복잡성을 줄이는 방법을 보여줍니다. 유럽의 도입 실적을 통해, 커넥티드 LED 프로그램의 확대에 따라 상당하고 측정 가능한 에너지 절감 효과와 유지보수 부담 경감이 확인되었습니다. 진화하는 사이버 보안 및 데이터 접근 규제에 대한 준수가 조달 동향을 형성하고 있으며, 개방형 표준을 기반으로 구축된 플랫폼이 우선시되고 있습니다.
아시아태평양은 계속 확장되는 메가시티의 도시 개발 및 주요 도로 조명에 대한 정부 투자가 본격화됨에 따라 연평균 성장률(CAGR) 14.12%를 나타낼 것으로 예측되는 가장 빠르게 성장하는 지역입니다. 인도의 ‘스마트 시티 미션’은 커넥티드 조명에 막대한 자금을 투입하고 있으며, 이는 도시 차원의 조달과 다목적 이용 사례를 촉진하고 있습니다. 호주 및 뉴질랜드에서는 유틸리티체 주도의 도입이 진행되고 있으며, 주요 도시에서는 에너지 절감 효과를 더욱 높이고 운영을 개선하기 위해 스마트 제어와 결합된 2세대 LED로 교체할 계획을 세우고 있습니다. 각 벤더는 선택의 폭을 확보하기 위해 듀얼 소켓 컨트롤러를 사용하여 셀룰러 통신과 LPWAN의 커버리지 균형을 맞추고, 현지 요구 사항에 맞추어 제품 설계를 조정하고 있습니다. 이러한 정책과 기술의 조합을 통해 개보수 프로젝트와 신규 도입 프로젝트 모두에서 스마트 가로등 관리 시스템 시장의 보급이 촉진되고 있습니다.
북미에서는 대규모 지자체 및 전력 회사의 프로그램이 고장 감지, 출장 수리 감소, 분석을 통한 유지보수에 중점을 두면서, 메가 프로젝트에는 P3(민관 파트너십) 체계를 활용하고 있습니다. 시카고의 다년간에 걸친 프로그램에서는 CO₂ 감축 외에도 에너지 효율 및 리베이트의 성과가 강조되고 있으며, 이는 다른 도시들에게도 가치 제안을 뒷받침하고 있습니다. 워싱턴 D.C. 전역에 걸친 현대화 사업에서는 셀룰러 제어를 도입하고, 조명 인프라를 기반으로 디지털 서비스를 확충함으로써 형평성과 가동률 향상을 도모하고 있습니다. Off-grid 태양광 발전 시스템 역시 구리선 도난을 억제하고, 위험이 높은 도로 구간의 복구 작업을 신속히 진행하기 위한 수단 중 하나가 되고 있습니다. 중동에서는 가로등 업그레이드가 더 대규모의 스마트 인프라 프로그램의 기반이 되고 있으며, 새로운 계약에는 지능형 교통 기능과 AI를 활용한 자산 관리가 명시되어 있습니다. 두바이의 다년간에 걸친 지역별 조명 계획은 표준 규격에 부합하는 LED 및 제어 시스템을 대규모로 도입함으로써 에너지 효율과 신뢰성을 향상시키는 방법을 제시하고 있습니다. 이러한 추세는 다양한 자금 조달 모델과 정책 환경 속에서 스마트 가로등 관리 시스템 시장의 기반이 확대되고 있음을 보여줍니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.08According to Mordor Intelligence, the connected street lighting market size is projected to reach USD 4.82 billion by 2031, reflecting a 13.49% CAGR over the forecast period, from USD 2.56 billion in 2026.
This report is Segmented by Component (Hardware, Software, Services), Connectivity (RF Mesh - Wi-SUN and IEEE 802. 15. 4g, and More), Application (Smart Dimming and Policy-Based Scheduling, and More ), End User (Municipalities and Local Governments, Electric Utilities and Distribution System Operators, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Connected Street Lighting Market Trends and Insights
Rising Electricity Prices and Energy Efficiency Mandates Compound Retrofit Economics
Networked LED streetlights with controls have delivered measurable energy and O&M cuts in large programs, which strengthens the business case for scale. Chicago's 290,000 fixture rollout reduced annual electricity expenses by USD 8.7 million and generated USD 37 million in utility rebates over five years, while carbon reductions totaled 134,600 metric tons by September 2022. Revenue-grade metering in smart lighting platforms supports compliance and streamlined reporting, eliminating the need for costly substation instrumentation. Ontario's 2025 grid-planning guidance emphasizes non-wires strategies during project screening, positioning adaptive lighting as a flexible demand-response tool for utilities and municipalities. Procurement teams increasingly link controller-capable luminaires to rebate eligibility and decarbonization tracking, reinforcing the role of connected lighting in municipal energy policy. These dynamics underpin durable demand in the smart street lighting management systems market as cities aim to protect budgets and meet climate targets.
Acceleration of Smart City Programs and PPP Procurement De-Risks Municipal Balance Sheets
Public-private partnerships enable cities to shift performance risk and transform energy savings into predictable payments over multi-year terms. Serbia's Pozega project under an energy service structure is cited as a practical template for smaller municipalities that lack upfront capital but need modernization and verifiable outcomes. India's Smart Cities Mission directs sizable funding to corridor illumination, intelligent intersections, and connected poles, which sustains high-volume tenders and accelerates digital infrastructure in fast-growing urban clusters. These models also attract infrastructure funds that prefer long-duration, utility-like cash flows anchored in verified energy reductions. As multi-party agreements mature, performance guarantees, remote monitoring, and open-data clauses become standard, which reduces perceived vendor risk and advances bankability. This structural shift supports steady growth in the smart street lighting management systems market where fiscal constraints would otherwise stall upgrades.
High Upfront Costs, Complex Tendering and Financing Disproportionately Burden Smaller Municipalities
Network-ready luminaires and controller rollouts add capital intensity that is difficult for small cities to absorb within one budget cycle. Performance-based contracts and availability-payment PPPs move energy-savings risk to private operators, but they can extend procurement timelines due to verification and monitoring requirements. Municipalities evaluate Lighting-as-a-Service to eliminate upfront equipment costs and shift to predictable monthly fees backed by quantifiable O&M savings. Utility alignment around non-wires solutions makes adaptive lighting more attractive where network upgrades would otherwise be approved, although documentation needs and cross-department coordination can slow approvals. Even with long-term savings, smaller towns face elevated tendering overhead, which tempers near-term adoption in the smart street lighting management systems market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Shift to Cellular Controls for Plug-and-Play Deployments Sidesteps Mesh Gateway Overhead
- Interoperability via Zhaga-D4i, DALI-2, and TALQ Improving Vendor Neutrality Unlocks Multi-Decade Asset Life
- Cybersecurity, Data Governance, and Sovereignty Concerns Elevate Compliance Overhead and Slow Vendor Selection
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware captured 62% of the smart street lighting management systems market in 2025, while software and services are growing at 13.65% CAGR as cities adopt central management systems that enable remote control, firmware updates, and carbon-accounting dashboards. City platforms such as Interact and similar SaaS offerings have shifted spending from upfront capital to per-endpoint fees, allowing integration with traffic signals, EV chargers, and public safety feeds through secure APIs. At scale, operators manage millions of telemetry messages per day, which supports digital-twin models of each luminaire and improves service planning and availability metrics across fleets. Software's share expansion also reflects policy that favors revenue-grade metering and verifiable emissions reporting in city sustainability plans. As sockets standardize via ANSI C136.41 and Zhaga Book 18, hardware becomes more interchangeable, which pressures pricing and elevates the role of software differentiation in the smart street lighting management systems market.
Services remain substantial as turnkey PPP contracts bundle installation, commissioning, and multi-year performance obligations, though growth trails software as more value shifts to analytics and automation. Predictive maintenance drives measurable O&M savings, converting reactive truck rolls into scheduled interventions that consolidate tasks and reduce time to repair. These trends continue to draw spend toward SaaS and integration services as the smart street lighting management systems industry uses APIs and standardized data models to share insights across city departments. Over 2026 to 2031, software-led gains are reinforced by policy incentives tied to metering and carbon disclosure, which helps sustain premium pricing for analytics features. This mix strengthens recurring revenue and cushions vendors against hardware margin compression in the smart street lighting management systems market.
Proprietary RF mesh, including Wi-SUN and IEEE 802.15.4g, held a 55.5% connectivity share in 2025, while cellular controls are forecast to grow at a 13.73% CAGR as cities value simpler rollouts and carrier-grade uptime. In Washington, D.C., 75,000 lamp-level cellular controllers reduced deployment complexity while enabling real-time monitoring, eliminating gateway installation and maintenance. Standard device-management frameworks like LwM2M improve reliability and lifecycle control for large distributed endpoint fleets. LoRaWAN remains favored where long-range, low-throughput links are sufficient, and spectrum management is practical, particularly in site-constrained corridors that need battery-friendly endpoints. Project owners weigh subscription fees against gateway overhead, with many choosing cellular when workforce constraints and timelines dominate decision criteria in the smart street lighting management systems market.
RF mesh retains a role in utilities that prefer privately managed networks with deterministic behavior and long operational experience. Niche use cases include power-line communication in conduits where wireless performance is impaired, and Wi-Fi or short-range variants for campus settings that do not require street-scale range. The mix of technologies persists across regions, but interoperability and certification reduce lock-in and allow mixed fleets to be managed via a single CMS. As standards mature, more cities adopt dual-socket controllers to preserve choice in vendor selection and lifecycle upgrades, which keeps procurement competitive in the smart street lighting management systems market. This balance ensures continuity for existing RF networks while enabling cellular-first scale-outs that deliver the best total cost of ownership.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Connectivity
- RF Mesh (Wi-SUN, IEEE 802.15.4g)
- Cellular (NB-IoT, LTE-M, 4G/5G)
- LoRaWAN
- Power-Line Communication (PLC)
- Wi-Fi and IEEE 802.15.4
- By Application
- Smart Dimming and Policy-Based Scheduling
- Adaptive and Autonomous Lighting (Sensor-Driven)
- Traffic and Safety Analytics Enablement
- Energy Analytics and Asset Management
- Environmental and Microclimate Monitoring
- Public Wi-Fi and Communications Backhaul
- By End User
- Municipalities and Local Governments
- Electric Utilities and Distribution System Operators
- Energy Service Companies (ESCOs)
- Public-Private Concessionaires (PPP Models)
- Private Campuses and Industrial Parks
- By Deployment Model
- Cloud
- On-Premises
- Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Kenya
- Rest of Africa
- North America
Geography Analysis
Europe held a 65% installed-base lead in 2025, reflecting a decade of coordinated retrofits and policy support that elevated connected controls as a compliance tool and operational backbone for utilities. This share underscores a significant portion of the smart street lighting management systems market, with buyers prioritizing TALQ certification to manage multi-vendor fleets over long asset lives. Projects in Brussels and on national highways demonstrate how standardized interfaces ensure CMS interoperability across controllers and luminaires, reducing integration complexity. Field results from European deployments show large and measurable energy savings and maintenance reductions as connected LED programs scale. Compliance with evolving cybersecurity and data access rules is shaping procurement, which favors platforms built on open standards.
Asia-Pacific is the fastest-growing region at a projected 14.12% CAGR as governments align investment for urban upgrades and corridor illumination across expanding megacities. India's Smart Cities Mission channels significant funding to connected lighting, which stimulates city-scale procurement and multi-application use cases. Australia and New Zealand continue utility-led rollouts, with major cities planning second-generation LED replacements combined with smart controls to deepen savings and improve operations. Vendors adapt product designs to local requirements by balancing cellular and LPWAN coverage with dual-socket controllers to preserve vendor choice. This policy and technology mix strengthens adoption in the smart street lighting management systems market across both retrofit and greenfield deployments.
In North America, large municipal and utility programs focus on fault detection, truck-roll reduction, and analytics-driven maintenance while tapping P3 structures for megaprojects. Chicago's multi-year program highlights energy and rebate outcomes alongside CO2 reductions, which reinforces the value proposition for other cities. Washington, D.C.'s citywide modernization uses cellular controls and expands digital services on top of the lighting backbone to improve equity and uptime. Off-grid solar systems are also part of the toolkit to deter copper theft and speed restoration in high-risk corridors. In the Middle East, street lighting upgrades anchor larger smart infrastructure programs, with new contracts specifying intelligent transportation features and AI-enabled asset management. Dubai's multi-year district lighting plan demonstrates how standards-based LED and controls are applied at scale to deliver energy and reliability gains. These patterns together indicate a broadening base for the smart street lighting management systems market across varied funding models and policy environments.
- Signify N.V.
- Itron, Inc.
- Fonda Technology Co., Ltd.
- Flashnet S.A. (Lucy Group)
- Ubicquia, Inc.
- Schrader S.A.
- Dimonoff Inc.
- LED Roadway Lighting Ltd.
- Rongwen Energy Technology Group Co., Ltd.
- ST Engineering Telematics Wireless Ltd.
- Lucy Zodion Ltd.
- Trilliant Networks, Inc.
- CIMCON Lighting, Inc.
- Sensus USA Inc. (Xylem)
- LACROIX Group SE (Citylone)
- Umpi S.r.l.
- Current Lighting Solutions, LLC
- Telensa Ltd.
- Tvilight B.V.
- Quantela Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Electricity Prices and Energy Efficiency Mandates
- 4.2.2 Acceleration of Smart City Programs and PPP Procurement
- 4.2.3 Rapid Shift to Cellular Controls for Plug-and-Play Deployments
- 4.2.4 Interoperability via Zhaga-D4i, DALI-2, and TALQ Improving Vendor Neutrality
- 4.2.5 Data-Driven Operations, Fault Localization, and Predictive Maintenance
- 4.2.6 Lamp-Post-as-a-Platform for 5G, Sensing, and City Services
- 4.3 Market Restraints
- 4.3.1 High Upfront Costs, Complex Tendering and Financing
- 4.3.2 Legacy Infrastructure Integration and Multi-Vendor Interoperability Gaps
- 4.3.3 Cybersecurity, Data Governance, and Sovereignty Concerns
- 4.3.4 Standards Fragmentation and Spectrum Constraints in Dense Urban RF
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value / Supply-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE AND VOLUME)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Connectivity
- 5.2.1 RF Mesh (Wi-SUN, IEEE 802.15.4g)
- 5.2.2 Cellular (NB-IoT, LTE-M, 4G/5G)
- 5.2.3 LoRaWAN
- 5.2.4 Power-Line Communication (PLC)
- 5.2.5 Wi-Fi and IEEE 802.15.4
- 5.3 By Application
- 5.3.1 Smart Dimming and Policy-Based Scheduling
- 5.3.2 Adaptive and Autonomous Lighting (Sensor-Driven)
- 5.3.3 Traffic and Safety Analytics Enablement
- 5.3.4 Energy Analytics and Asset Management
- 5.3.5 Environmental and Microclimate Monitoring
- 5.3.6 Public Wi-Fi and Communications Backhaul
- 5.4 By End User
- 5.4.1 Municipalities and Local Governments
- 5.4.2 Electric Utilities and Distribution System Operators
- 5.4.3 Energy Service Companies (ESCOs)
- 5.4.4 Public-Private Concessionaires (PPP Models)
- 5.4.5 Private Campuses and Industrial Parks
- 5.5 By Deployment Model
- 5.5.1 Cloud
- 5.5.2 On-Premises
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 France
- 5.6.3.3 United Kingdom
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Egypt
- 5.6.6.3 Kenya
- 5.6.6.4 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Signify N.V.
- 6.4.2 Itron, Inc.
- 6.4.3 Fonda Technology Co., Ltd.
- 6.4.4 Flashnet S.A. (Lucy Group)
- 6.4.5 Ubicquia, Inc.
- 6.4.6 Schrader S.A.
- 6.4.7 Dimonoff Inc.
- 6.4.8 LED Roadway Lighting Ltd.
- 6.4.9 Rongwen Energy Technology Group Co., Ltd.
- 6.4.10 ST Engineering Telematics Wireless Ltd.
- 6.4.11 Lucy Zodion Ltd.
- 6.4.12 Trilliant Networks, Inc.
- 6.4.13 CIMCON Lighting, Inc.
- 6.4.14 Sensus USA Inc. (Xylem)
- 6.4.15 LACROIX Group SE (Citylone)
- 6.4.16 Umpi S.r.l.
- 6.4.17 Current Lighting Solutions, LLC
- 6.4.18 Telensa Ltd.
- 6.4.19 Tvilight B.V.
- 6.4.20 Quantela Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


